

US‑Iran tensions stay high with both sides continuing belligerent rhetoric. Spot gold traded within recent lows overnight and closed at $4448.88 per ounce, down 0.18%. Spot silver finished at $66.489 per ounce, up 0.27%.
During Tuesday’s ASIan session, spot gold opened at $4448.04 per ounce and traded in a narrow range between $4461.30 high and $4427.68 low. At press time, gold hovers near $4432, down 0.38%.
The US Dollar Index extended its overnight decline to a low of 99.39 and closed at 99.42, down 0.27%. The 2‑year US Treasury yield slipped 0.6 bASIs points to 4.344%; the 10‑year yield rose 3 bASIs points to 4.752%; the 30‑year yield climbed 3.5 bASIs points to 5.243%.
Global crude benchmarks held overnight gains. WTI crude closed at $86.35 per barrel (+3.45%); Brent crude settled at $90.82 per barrel (+2.83%). US natural gas CFD closed at $2.93 per MMBtu, up 1.842%.

All three major US equity indices closed lower. The Dow Jones Industrial Average fell 373.85 points (-0.70%) to 53186.14; the S&P 500 lost 25.42 points (-0.33%) to 7686.34; the Nasdaq Composite dropped 31.53 points (-0.12%) to 26370.89.
Major European equity markets finished in negative territory. Germany’s DAX 30 declined 1.17% to 26258.11; France’s CAC 40 fell 0.79% to 8334.50; Spain’s IBEX 35 eased 0.34% to 19974.10; Italy’s FTSE MIB edged‑0.01% to 52612.69; the Euro Stoxx 50 dropped 1.01% to 6420.16.
On the Shanghai Gold Exchange, Au(T+D) closed‑1.16% at 957.7 yuan per gram; Ag(T+D) finished‑1.78% at 16150.0 yuan per kilogram. Early‑Tuesday trade saw Au(T+D) down 0.72% at 961.99 yuan per gram, while Ag(T+D) fell 0.98% to 16281.0 yuan per kilogram.
Holdings of SPDR Gold Trust, the world’s largest gold‑backed ETF, were unchanged at 1042.357 tonnes. iShares Silver Trust, the world’s largest silver ETF, maintained its position at 15359.92 tonnes.
Today’s official FX mid‑points: USD‑CNY 6.7809 (-19 pips, CNY appreciation); EUR‑CNY 7.8406 (+62 pips); HKD‑CNY 0.86498 (-1.2 pips); GBP‑CNY 9.1431 (-99 pips); AUD‑CNY 4.8373 (-37 pips); CAD‑CNY 4.8687 (+87 pips); 100JPY‑CNY 4.2301 (+16 pips); CNY‑RUB 12.8255 (+1016 pips); NZD‑CNY 3.9928 (-66 pips); CNY‑MYR 0.59617 (+8.4 pips); CHF‑CNY 8.3532 (-71 pips); SGD‑CNY 5.3115 (+75 pips).
Overnight data releases: Germany’s August preliminary MoM CPI printed at 0.2% vs expectation 0.25%, prior 0.80%. US August Dallas Fed Manufacturing Activity Index came in at 11.6, prior 1.3.
German inflation edged higher to its highest since April. With a Middle‑East peace deal still distant, energy prices have re‑emerged as a key inflation driver. Earlier French and Spanish figures also showed rising oil‑gas costs lifting regional inflation, reinforcing expectations for another European Central Bank rate hike on September 10.
The US 10‑year Treasury yield broke above 4.75% overnight, hitting its highest level since January 2025, as higher oil prices boosted Fed‑hike expectations. Yields across other US tenors moved higher. US President Trump stated the United States will respond to Iranian attacks on US forces with further strikes. Last Friday, Federal Reserve Chair Warsh delivered remarks at Jackson Hole signalling increased odds of additional rate increases.
Previously, 172 million barrels of crude oil released from the US Strategic Petroleum Reserve were loaned to commercial firms. Borrowers are required to repay roughly 40 million additional barrels as interest, with full repayment not completed until late‑2028. Trump said the US will replenish SPR using oil obtained under the recent energy agreement with Venezuela. Analysts note America’s domestic energy emergency buffer is strained amid ongoing Middle‑East turmoil.
US Treasury Secretary Bessent stated there is no defined timeline for an Iranian economic collapse and Washington will keep applying pressure; an Iranian economic breakdown could take weeks or months. He also shared common ground with Fed Chair Warsh on bond‑market issues, arguing economic growth is the only path out of debt burdens.
US President Trump said the US will retaliate against Iran’s latest strikes and warned “we will hit them hard”. A senior Iranian military commander said Iran’s primary strategic objective amid ongoing confrontation is building maximum deterrence rather than initiating new military conflict or negotiating with adversaries. He added weapons‑production facilities damaged in recent hostilities have been rebuilt in highly secure locations and are now operating at higher output with advanced new technologies.
Iranian Foreign Minister Araghchi blamed US violations of the Islamabad Memorandum of Understanding for current tensions. He argued the path toward de‑escalation requires the United States to honour commitments made by its President to restore normal conditions.
Chinese President Xi Jinping met with Russian President Vladimir Putin on the sidelines of the 2026 Shanghai Cooperation Organisation Summit in Bishkek. President Putin stated that amid turbulent and complex international circumstances, Russia is ready to maintain high‑level exchanges with China and strengthen cooperation in trade, energy, industry, transport, science and technology.
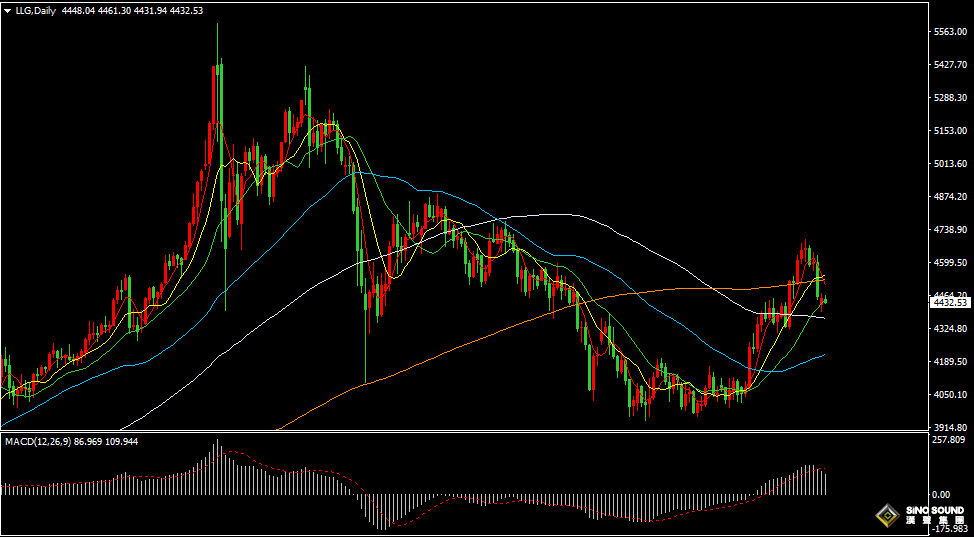
On the daily chart, gold stabilised and rebounded overnight yet lacked strong upward momentum. Prices have broken below the 5‑day, 10‑day and 200‑day moving averages and currently fluctuate around the 20‑day MA. Daily indicators show shrinking positive MACD histogram while RSI flattens near 53.
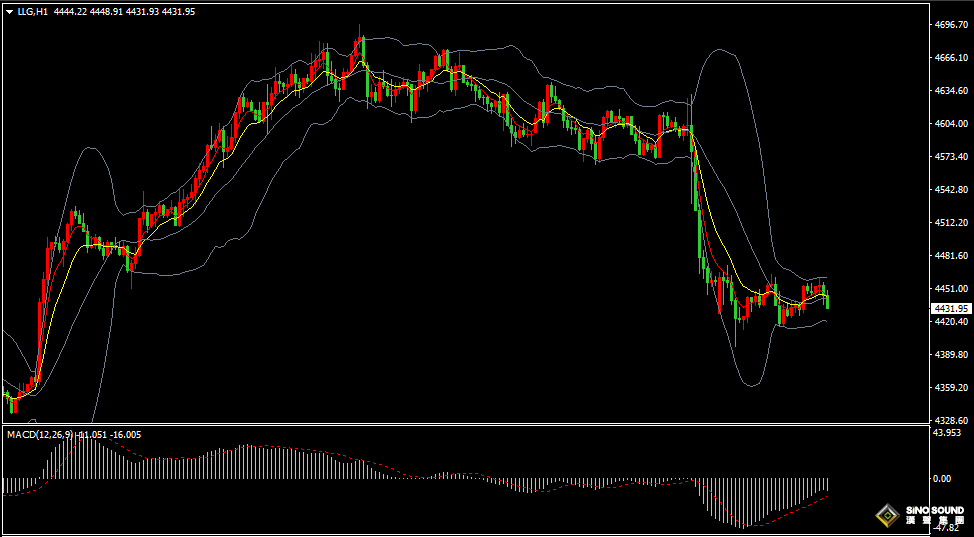
On the 1‑hour chart, BOLLinger Bands have narrowed and flattened. Short‑term EMA5 and EMA10 converge sideways. Negative MACD histogram keeps shrinking and RSI rebounds toward 43. Intraday strategy: watch consolidation within $4420‑4470. A breakout higher targets $4480‑4495 or $4505. A breakdown lower targets $4410‑4400 or $4390.
Key economic releases and events for today:
14:00 UK August Nationwide House Price Index MoM
14:30 Switzerland July Real Retail Sales YoY
15:50 France August Final Manufacturing PMI
15:55 Germany August Final Manufacturing PMI
16:00 Eurozone August Final Manufacturing PMI
16:30 UK August Final Manufacturing PMI
16:30 UK July Bank of England Mortgage Approvals
17:00 Eurozone August Preliminary CPI YoY
17:00 Eurozone August Preliminary CPI MoM
17:00 Eurozone July Unemployment Rate
21:05 Fed’s Barr Speaks
21:45 US August Final S&P Global Manufacturing PMI
22:00 US August ISM Manufacturing PMI
22:00 US July JOLTS Job Openings
22:00 US July Construction Spending MoM
04:30 (Next Day) US API Weekly Crude Oil Stock Change for week ending August 28
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.