

Before last night's US session, the US dollar continued to strengthen, pressuring spot gold to slide briefly and break below the $4,100/oz level, hitting a two-month low of $4,066.23/oz. It then rebounded and closed at $4,110.65/oz, down 1.28%; spot silver closed at $59.741/oz, down 2.55%.
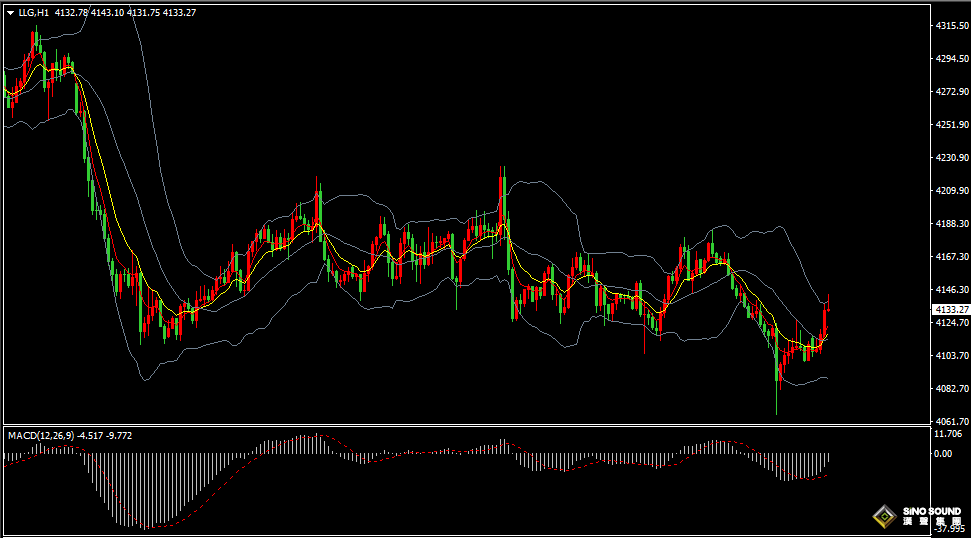
During Thursday's ASIan session, spot gold opened at $4,114.72/oz, dipped to a low of $4,103.23/oz in early trading, and then oscillated higher to a peak of $4,143.10/oz. At press time, gold traded around $4,133/oz, up 0.54% on the day.
At the start of last night's US session, the US Dollar Index rallied to an intraday high of 102.50 before retreating to close at 102.28, up 0.43%. The 2-year US Treasury yield fell 3.1 bASIs points to 4.77%; the 10-year US Treasury yield rose 0.8 bASIs points to 5.286%; the 30-year US Treasury yield climbed 1.3 bASIs points to 5.673%.
International crude oil hit an intraday high last night and then pulled back. WTI crude closed at $88.86 per barrel, down 1.18%; Brent crude closed at $100.80 per barrel, down 0.36%. US natural gas CFD rose 3.239% to settle at $3.219 per million British thermal units.

The three major US stock indexes closed lower overnight. The Dow Jones Industrial Average fell 341.41 points, or 0.66%, to 51,179.87. The S&P 500 dropped 17.20 points, or 0.22%, to 7,801.73. The Nasdaq Composite lost 61.20 points, or 0.22%, to 27,538.69.
European stock markets all closed in negative territory. Germany's DAX 30 fell 1.26% to 25,129.11. The UK FTSE 100 dropped 0.74% to 10,464.18. France's CAC 40 declined 1.22% to 7,769.21. The Euro Stoxx 50 fell 1.39% to 6,185.15. Spain's IBEX 35 lost 1.63% to 19,127.54. Italy's FTSE MIB tumbled 2.44% to 50,011.50.
Holdings of SPDR Gold Trust, the world's largest gold ETF, increased by 1.14 tonnes from the previous session to 1,061.113 tonnes. Holdings of iShares Silver Trust, the world's largest silver ETF, decreased by 19.66 tonnes to 15,311.57 tonnes.
In early morning trading on the Shanghai Gold Exchange, Au(T+D) fell 1.42% to 889.51 yuan per gram, while Ag(T+D) rose 0.67% to 14,890 yuan per kilogram.
The central parity rate of the RMB against major currencies today: USD/CNY at 6.7367, up 16 pips (RMB depreciation); EUR/CNY at 7.5404, down 811 pips; HKD/CNY at 0.85849, up 0.7 pips; GBP/CNY at 8.8972, up 54 pips; AUD/CNY at 4.6852, down 107 pips; CAD/CNY at 4.7209, down 132 pips; 100JPY/CNY at 4.2642, down 85 pips; CNY/RUB at 12.7353, up 2288 pips; NZD/CNY at 3.7693, down 206 pips; CNY/MYR at 0.60658, down 1.2 pips; CHF/CNY at 8.0849, up 241 pips; SGD/CNY at 5.2610, up 3 pips.
The State Administration of Foreign Exchange reported that China's foreign exchange reserves stood at USD 3.4003 trillion at the end of September, down USD 38.1 billion month-on-month. The People's Bank of China raised its gold reserves for the 23rd consecutive month, adding 740,000 ounces month-on-month.
Data from the New York Fed released overnight showed the median consumer inflation expectation for the next 12 months rose to 3.9% from 3.6% in August, the highest level since May 2023. The three-year inflation expectation edged up from 3.2% to 3.3%, while the five-year expectation remained unchanged at 3%.
Analysts noted that US households expect spending to rise by 5.5% over the next year, 0.3 percentage points higher than August, also the highest reading since May 2023. Consumers still anticipate spending growth will outpace income growth. Although price expectations keep rising, consumers maintain a relatively fast spending pace while income fails to keep up. More households believe their financial situation has worsened compared with one year ago and expect it to deteriorate further in the coming 12 months.
The minutes of the Fed's September meeting released overnight showed all 19 officials supported a 25-bASIs-point rate hike, and most believed further policy tightening would still be necessary before year-end. However, post-meeting remarks suggested the Fed is in no hurry to act again in October.
At the September meeting, the Fed raised its target federal funds rate range by 25 bASIs points to 3.75%-4.00%, marking its first rate hike since July 2023. Officials did not share identical reasons for supporting the hike; many worried inflation pressures could intensify further, while others viewed the rate increase as a necessary policy choice based on economic outlook assessments.
Analysts said recent Fed remarks have significantly cooled expectations for an October move. Forecasts point to one more rate hike across the remaining October and December meetings this year, while a small number of officials expect hikes at both meetings.
Friday's US non-farm payroll data showed the labor market remained stable without obvious overheating. Average hourly earnings rose 3% year-on-year, the lowest level in more than five years. An October rate hike has not been completely ruled out, and the US Consumer Price Index (CPI) due on October 14 may still shift market pricing.
A World Gold Council report said global gold ETFs attracted USD 10 billion in inflows in September, bringing Q3 inflows to a record USD 31 billion. Despite the gold price decline, global gold ETF holdings rose by 67 tonnes to an all-time high of 4,256 tonnes, while total AUM fell 7% month-on-month to USD 574 billion.
Reports indicate the EU is considering a general tax on large corporations targeting major US tech firms. To avoid strong pushback from the Trump administration, the EU is exploring new taxation methods.
At a meeting of EU member state officials yesterday, following the G7 announcement last week of plans to release 100 million barrels of crude oil and diesel, EU countries will not need to release additional oil reserves. No EU nation made a firm commitment to release supplies within the 20-day window. France and Italy may consider releASIng extra diesel beyond the amounts pledged in March.
On international affairs, Naghdi, advisor to the commander of Iran's Islamic Revolutionary Guard Corps, stated yesterday that the Strait of Hormuz has been closed and will remain so until Iran's legitimate demands are met. There are currently no negotiations between Iran and the US regarding Tehran's nuclear program, and Washington's stance on Iran's nuclear program diverges from Iran's requirements.
Reports say the US government has ordered US Central Command to complete preparations to resume major military operations against Iran, though Trump has not made a final decision or set a strike date. Should operations resume, they could occur before the US midterm elections on November 3, and even before Israel's general election on October 27.
With Houthi attacks escalating, Saudi Arabia has requested Syria consider deploying troops to strike Houthi forces. Damascus is evaluating options including defensive aid and ground combat participation. Syria stated its firm support for Saudi Arabia but denied it will be drawn into the Yemen conflict. Saudi Arabia is also seeking backing from the US, European and Middle Eastern nations.
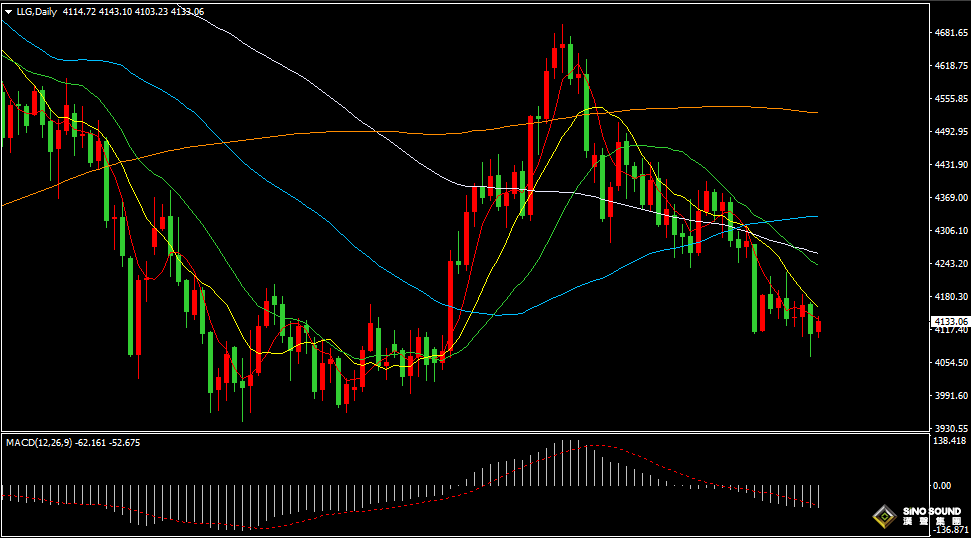
On the daily gold chart, gold fell briefly overnight and broke below the $4,100 level, piercing the bottom of its recent consolidation range. It found support near $4,066 and rebounded back to trade around the 5-day moving average. From daily indicators, the 10-day moving average continues to cap gold prices. The MACD histogram maintains peRSIstent negative momentum, and the RSI hovers near the 39 level.
On the 1-hour gold chart, gold bounced from the lower BOLLinger Band toward the upper BOLLinger Band. The short-term EMA5 and EMA10 have turned bullish upward. Negative MACD momentum continues to shrink, and the RSI has flattened near the 55 level. For intraday trading, expect gold to oscillate within the $4,100-$4,160 range. A breakout to the upside targets $4,175-$4,185 or near $4,195. Downside targets sit at $4,090-$4,080 or near $4,070.
Key economic data and events to watch today:
14:00 Germany August seasonally adjusted trade balance
19:30 ECB releases minutes of September monetary policy meeting
20:15 Bank of England Governor Bailey delivers speech
20:30 US Initial Jobless Claims for the week ending October 3
22:00 US August Wholesale Sales MoM
22:30 US EIA Natural Gas Inventories for the week ending October 2
01:40 (next day) Fed's Musalem speaks
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.