

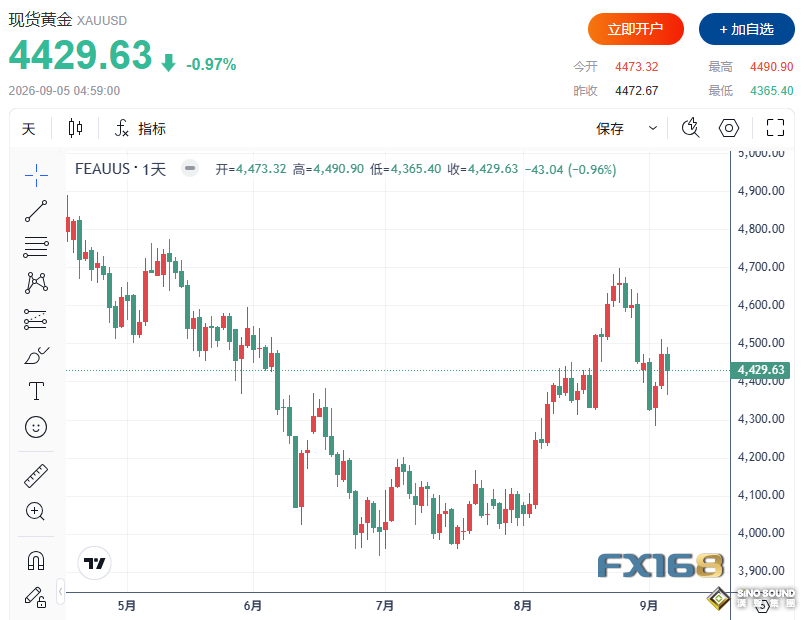
Spot gold witnessed sharp swings again this week: bolstered by falling U.S. Treasury yields, a weaker U.S. dollar and dovish signals from Fed officials, gold staged a strong rebound mid‑week. However, after U.S. August non‑farm payrolls came in stronger than expected, market bets for a September Fed rate hike surged rapidly. Gold gave up most of its gains on Friday and closed slightly lower on the weekly chart.
Spot gold opened at $4439.15 per ounce on Sunday evening. It then came under pressure as traders continued digesting the prior‑week plunge, peRSIstently high U.S. Treasury yields, plus inflation concerns stemming from oil prices and U.S.‑Iran tensions. Gold’s decline accelerated early Tuesday, briefly breaking below $4300 and hitting the weekly low of $4282.61 before bargain‑hunting buying emerged.
Gold began its recovery on Wednesday. It rallied further on Thursday following soft U.S. private‑sector employment figures, retreating Treasury yields and less‑hawkish remarks from Fed Governor Christopher Waller. Spot gold climbed back above $4500 at one point and touched the weekly peak of $4511.08 on Thursday.
Nevertheless, this rebound suffered a heavy setback early Friday. The U.S. Labor Department reported 162,000 new non‑farm jobs in August, well above market consensus, with the unemployment rate holding at 4.1%. Robust employment lifted the U.S. dollar and short‑term Treasury yields and reignited September rate‑hike trades. Gold tumbled within minutes after the release, dropping to an intraday low of $4365.57.

By Friday afternoon, spot gold had recouped part of its post‑payroll losses but failed to retake $4500, trading at $4429.63, with a modest weekly loss overall.
(Source: FX168)
Widening Divide Between Wall Street and Retail Investors
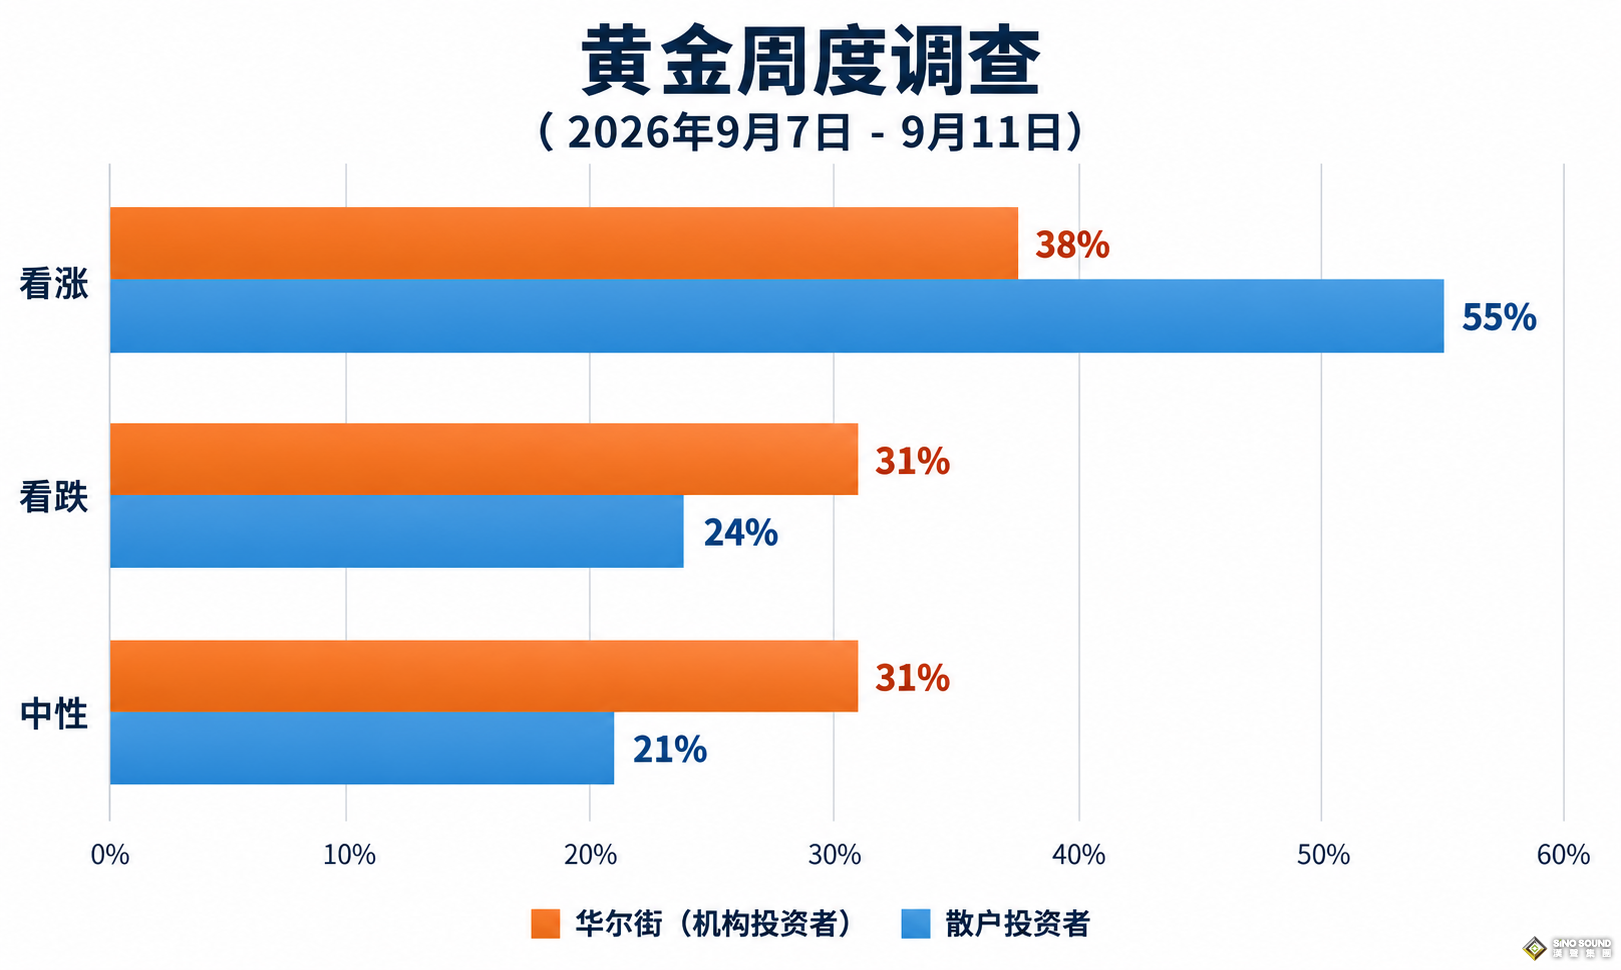
The latest Kitco News weekly gold survey shows sharp divergence among Wall Street analysts after wild price swings, with bulls, bears and neutrals nearly evenly split. Retail investors also trimmed bullish exposure following gold’s failed attempt at another rally.
For investment outlook, 16 analysts took part in this week’s Kitco gold survey. 6 analysts (38%) predicted higher gold prices next week, 5 (31%) expected further declines, and another 5 (31%) forecast choppy sideways trading. Meanwhile, 220 votes were collected in the online poll. Retail bullish sentiment fell to 55%, with 120 traders calling for higher prices; 53 respondents (24%) were bearish, while 47 (21%) anticipated consolidation or a directionless range‑bound market.
(Source: Kitco)
Marc Chandler, Managing Director at Bannockburn Global Forex, noted gold was already soft late the prior week and suffered a notable drop mid‑last week. Technical conditions remain weak with momentum indicators trending lower. He argued a break below the $4280 zone could trigger another leg lower targeting around $4200.
Darin Newsom, Senior Market Analyst at Barchart.com, holds a bearish bias. He said gold’s trajectory largely hinges on the magnitude of post‑payroll losses. August non‑farm payrolls printed 162,000, over 100,000 above pre‑release estimates, painting an overly rosy picture of the U.S. economy, yet he expects these figures will most likely get revised in coming months, limiting their long‑term significance. Newsom added that absent a further sharp sell‑off ahead of the U.S. three‑day holiday weekend, gold may retest this week’s low near $4396.40, while the 45‑day moving average sits well below current levels around $4320.
Adrian Day, President of Adrian Day Asset Management, believes gold will most likely stay range‑bound in the short run without a clear directional bias as markets await the Fed rate decision in less than two weeks. Although strong jobs bolster rate‑hike expectations, he stressed nothing is set in stone, as the Fed historically tends to avoid major policy moves ahead of elections. Day also stated upcoming economic releases, especially August Consumer Price Index (CPI) readings days before the Fed meeting, will shape rate decisions and in turn drive gold performance.
Rich Checkan, President and Chief Operating Officer at Asset Strategies International, takes the opposite view. While employment data temporarily pressured gold, plenty of supportive factors remain. Even as rate‑hike worries mount, debt levels keep expanding, so gold’s long‑term trajectory remains upward.
Market Focus on Interest Rates and Inflation
Kevin Grady, President of Phoenix Futures and Options, said gold and broader markets are almost entirely fixated on interest‑rate developments. Strong payrolls reduce odds for “rates on hold”, and markets are pricing in higher interest rates. Grady argued if the Fed intends to raise rates this autumn, it must act at the upcoming meeting. He added markets will keep monitoring economic indicators and energy markets, given energy prices are a key inflation driver.
Grady also pointed out Waller’s Thursday remarks represented his personal opinion rather than the collective stance of the Federal Open Market Committee (FOMC). Beyond next Friday’s CPI, energy markets, particularly crude oil prices, offer critical clues for Fed moves, since inflation dynamics are heavily influenced by energy.
He explained the Fed has previously viewed rising oil‑and‑gas prices as transitory. Once such pressures feed into broader inflation metrics, policymakers will have little choice but to adopt more aggressive responses.
Amid a U.S. holiday‑shortened trading week, economic data focus will centre on inflation prints. Markets will also track manufacturing and service‑sector surveys plus rate decisions from two central banks. On Thursday morning, the European Central Bank (ECB) will unveil its monetary‑policy statement, with markets pricing in a rate hike amid elevated energy costs lifting Euro‑area consumer prices. The same day will bring U.S. August Producer Price Index (PPI) and existing‑home sales figures. Friday features August CPI and the preliminary September UniveRSIty of Michigan Consumer Sentiment Index.
Divergent Institution Views: Bears, Bulls and Neutrals Coexist
David Morrison, Senior Market Analyst at Trade Nation, is short‑term bearish on gold, saying momentum indicators suggest a potential test of support near $4200. He recalled gold was struggling to break $3500 around this time last year, while $2000 was once seen as an ambitious level even earlier. Gold continues to battle against the U.S. dollar underpinned by rate‑hike expectations; should rate‑hike bets get priced out again, dollar‑driven pressure on gold will ease.
Adam Button, Chief Forex Strategist at investingLive, said every data print between now and this month’s rate decision will shape Fed expectations, and Friday’s payrolls are no exception. Markets remain uncertain how the Fed under Warsh will act. After Jackson Hole, a near‑term hike seemed imminent, yet Waller pushed back forcefully, keeping hike probabilities hovering roughly between 40% and 60%.
Button believes the largely flawless payrolls report gives Fed officials worried about labour‑market strength enough justification for a rate increase. Markets are now highly focused on the September 16 Fed meeting. The Labor Day holiday weekend may affect Friday trading flows, with some short‑term traders choosing to square positions ahead of the break.
Gold will keep swinging on rate‑hike expectations until the Fed delivers clear guidance. A rate hike would hurt gold, while holding rates steady would benefit gold, a straightforward logic. Friday’s robust jobs report amplifies the importance of next week’s CPI; even a 0.1 percentage‑point deviation in inflation could trigger drastically different market reactions.
Button noted gold rallied on Waller’s Thursday comments, sold off Friday and then partially recovered, signalling underlying buying interest is emerging. He also referenced discussions over Norway’s U.S. Treasury sales, arguing the era of “infinite demand” for U.S. Treasuries may be over. Central‑bank gold accumulation will remain a long‑run trend for the rest of the century, varying only in pace.
Alex Kuptsikevich, Senior Market Analyst at FxPro, forecasts higher gold prices next week. Gold has suffered setbacks on two consecutive Fridays due to repricing of key Fed rate expectations. Waller previously voiced inflation concerns, and subsequent FOMC speakers helped gold recoup some ground. However, strong August payrolls plus substantial upward revisions to July’s soft figures revived odds for September tightening.
Kuptsikevich pointed out gold dropped 5% over seven days and fell back below the 200‑day moving average, without dismantling the upward trend built over the past six weeks. Since early this month, dips have attracted buying support, and the 50‑day moving average has acted as support. Strong economic data are not gold’s biggest threat. After short‑term shocks, solid data may strengthen gold’s fundamental case over the medium term. Bond sell‑offs and uncertain equity‑market outlooks may also push investors to seek alternatives beyond dollar‑denominated assets.
CPM Group issued a “Stand ASIde” recommendation for gold on Friday, projecting a trading range of $4320‑$4670 for September 7‑16. The institution stated extreme volatility in gold and other precious metals will likely peRSIst over the next two weeks amid shifting market views on U.S. interest rates. Next‑week markets will hinge on August PPI and CPI: cooling inflation would reduce odds for a September 16 rate hike, while sticky inflation will boost hike expectations.
CPM Group also expects heightened volatility around the September 16 Fed rate announcement and Warsh’s press conference. Markets are roughly split 50‑50 between a 25‑bASIs‑point hike and unchanged rates. Analysts noted a 25‑bp increase would not meaningfully curb inflation but signal the new Fed Chair’s hawkish stance and pressure precious‑metal prices in the short run.
Even so, CPM Group maintains a medium‑term bullish outlook for gold, citing multiple political and economic tailwinds for precious metals. It warns of further near‑term downside risks as higher‑rate expectations weigh on gold, favouring a stand‑ASIde approach with stop‑loss risk management. Without stop‑loss protection, prices could retest lower levels multiple times in the coming two weeks from an ultra‑short‑term perspective.
Michael Moor of Moor Analytics projects gold will climb again next week. His technical analysis lays out key levels plus “OFF HOLD” and “ON HOLD” signals across multiple timeframes. Higher‑time‑frame charts show signs of a bounce off lows and renewed strength. If the current phase is a genuine bullish correction, medium‑ and short‑term charts still allow for further upside potential. Multiple key breakout and reversal triggers have recently fired bullish or bearish signals, confirming large near‑term volatility for gold.
As of press time, spot gold traded at $4429.83 per ounce, down 0.36% on the week and 0.96% on the day.
Markets will now turn focus to next week’s U.S. inflation data, especially whether CPI will reinforce or ease September rate‑hike bets. Hot inflation could underpin the dollar and short‑term Treasury yields and keep gold under pressure. By contrast, cooling inflation may draw buying interest back to gold.