

US Treasury yields remained high and volatile yesterday, the US Dollar Index edged down, spot gold first dipped to a low of $4104.97 per ounce and then rebounded to a high of $4184.15 per ounce, finally closing at $4163.74 per ounce, up 0.57%; spot silver closed at $61.302 per ounce, rising 0.58%.
During Wednesday's ASIan session, spot gold opened at $4165.99 per ounce, hit a high of $4169.75 per ounce, then fluctuated lower in early trading to a low of $4140.12 per ounce. At press time, gold was trading near $4142, down 0.52% on the day.
The US Dollar Index surged to 102.29 in short-term trading last night, then EUR and GBP rebounded, pulling the US Dollar Index down to a low of 101.76, and it finally closed at 101.84, down 0.26. The 2-year US Treasury yield fell 1.3 bASIs points to close at 4.801%; the 10-year US Treasury yield dropped 3 bASIs points to 5.278%; the 30-year US Treasury yield edged down 0.5 bASIs points to 5.66%.
International crude oil prices halted their decline and rebounded last night. WTI crude oil closed at $89.92 per barrel, up 0.76%; Brent crude oil closed at $101.17 per barrel, gaining 0.90%; US natural gas CFD rose 1.234% to settle at $3.118 per MMBtu.

The three major US stock indices strengthened overnight, with the Nasdaq and S&P 500 notching fresh closing highs. The Dow Jones Industrial Average rose 253.32 points, or 0.49%, to 51521.22; the S&P 500 gained 45.03 points, or 0.58%, to 7818.98; the Nasdaq Composite climbed 122.48 points, or 0.45%, to 27599.79.
European major stock markets closed higher across the board. Germany's DAX 30 rose 0.78% to 25452.19; UK FTSE 100 advanced 0.41% to 10541.27; France's CAC 40 increased 0.40% to 7865.07; Euro Stoxx 50 rose 0.49% to 6272.95; Spain's IBEX 35 gained 0.73% to 19439.68; Italy's FTSE MIB climbed 0.84% to 51243.50.
Holdings of SPDR Gold Trust, the world's largest gold ETF, increased by 3.707 tons from the previous session, with total holdings at 1059.973 tons. Holdings of iShares Silver Trust, the world's largest silver ETF, remained unchanged at 15345.27 tons.
Fresh data released last night showed US ADP private payrolls changed by 23,750 in the week ending September 19, compared with a prior reading of 20,000. The US August trade deficit stood at $105.6 billion, versus an expectation of -$102.0 billion; the prior figure was revised from -$88.6 billion to -$92.8 billion. The US September Global Supply Chain Pressure Index was 1.28, versus a prior reading of 1.06.
The US August trade deficit widened sharply to its highest level since early 2025. A surge in imports of capital goods pushed total US imports to a record high. Meanwhile, supply chain challenges and heavy investment in AI that relies on imported technology and equipment also boosted import growth.
Remarks from Fed officials overnight were generally hawkish, though there were no surprisingly aggressive statements. Kansas City Fed President Schmid said the rebound in inflation is frustrating. If inflation fails to fall back to the 2% target, the Fed will need to keep raising interest rates. Energy prices are the biggest inflation challenge right now. He does not believe current policy is sufficiently restrictive and remains highly alert to inflation risks. San Francisco Fed President Daly stated that whether another rate hike is needed depends on three variables: tariff impacts, upside oil price risks stemming from Middle East conflicts, and the peRSIstence of AI-related demand.
Russia's Ministry of Finance announced it will expand foreign exchange and gold purchases from October 7 to November 6. The gold purchase volume will be five times that of September, with an allocation of 279.42 billion rubles. The excess oil and gas revenues will be transferred to the National Wealth Fund. This continues the global central bank gold-buying trend and offers bottom support for gold prices.
Institutional analysis notes that the recent surge in US 10-year and 30-year Treasury yields to 24-year highs is mainly driven by market concerns over inflation and high fiscal deficits. If tech stocks are sold off or US economic growth slows in the future, bonds will still hold investment value. Under such scenarios, bond assets may play a more obvious allocation and defensive role.
Supply pressure in the global diesel market may be far from over. Analysts estimate that the average crack spread for global diesel and jet fuel will remain above $40 per barrel in 2027, more than double the normal level of roughly $20 per barrel. Diesel prices may stay elevated through 2027. Even if crude oil shipments through the Strait of Hormuz gradually resume and Brent crude stabilizes around $80 per barrel, refined product markets will remain markedly tight.
It is reported that the International Energy Agency Governing Board is scheduled to hold a meeting on October 14–15. Previously, G7 member states agreed to release a total of 100 million barrels of diesel and crude oil from emergency reserves, and pledged not to impose energy export restrictions under pressure from Trump.
On international affairs, early voting for the US midterm elections kicked off in Ohio yesterday. This state that has voted heavily for Trump in the past three presidential elections has now become one of the key targets the Democrats hope to flip. The Republican Party currently controls both the White House and Congress, yet its majority is not solid.
Reports state that as Iran intensifies attacks on vessels, shipowners and seafarers willing to sail through the Strait of Hormuz demand an unprecedented "danger premium". Tanker captains can earn $100,000 per month plus a $50,000 bonus per voyage. Ordinary sailors earn four to six times their normal wages. Freight, insurance and fuel costs are all rising simultaneously.
The Federal Reserve will release the minutes of its monetary policy meeting tonight. A 25-bASIs-point rate hike was delivered at the September meeting, and the key focus of this set of minutes will be the degree of disagreement among FOMC members over whether to hike rates again in December. Current CME FedWatch data shows a roughly 77% probability that the Fed will keep rates unchanged in October and only a 22% chance of a rate hike; expectations for a December rate hike stand near 68%, indicating markets have heavily priced in a year-end rate increase. The Fed meeting minutes tonight are likely the biggest market trigger this week. Hawkish Fed rhetoric would lift Treasury yields and the US Dollar and pressure gold; dovish comments would be bullish for gold prices.
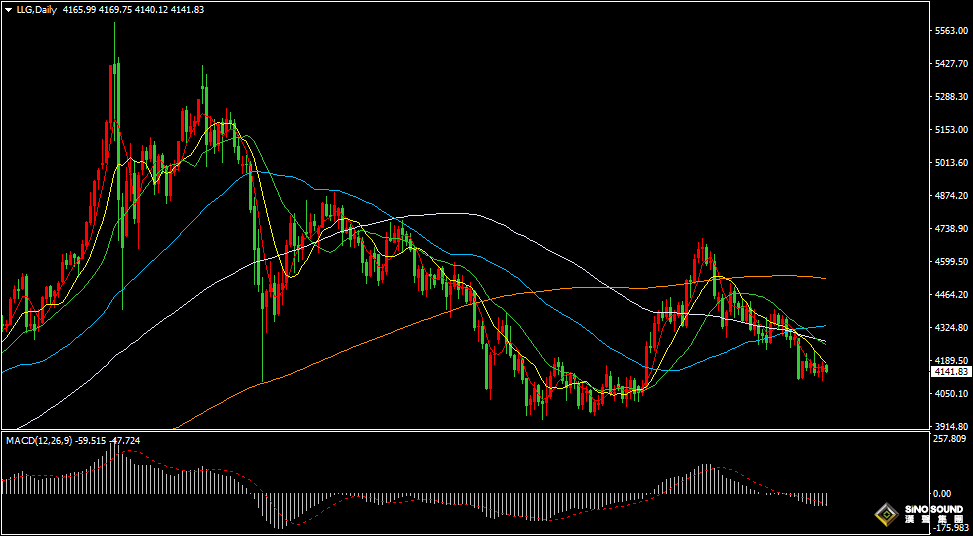
On the daily gold chart, gold closed higher in a bullish candle yesterday and has been consolidating in a low range recently. Gold is hovering near the 5-day moving average, with short-term resistance around the 10-day moving average and key support near the $4100 level. From daily indicators, the 5-day and 10-day moving averages maintain a bearish arrangement. The MACD negative momentum histogram peRSIsts, and the RSI indicator lingers near the 39 level.
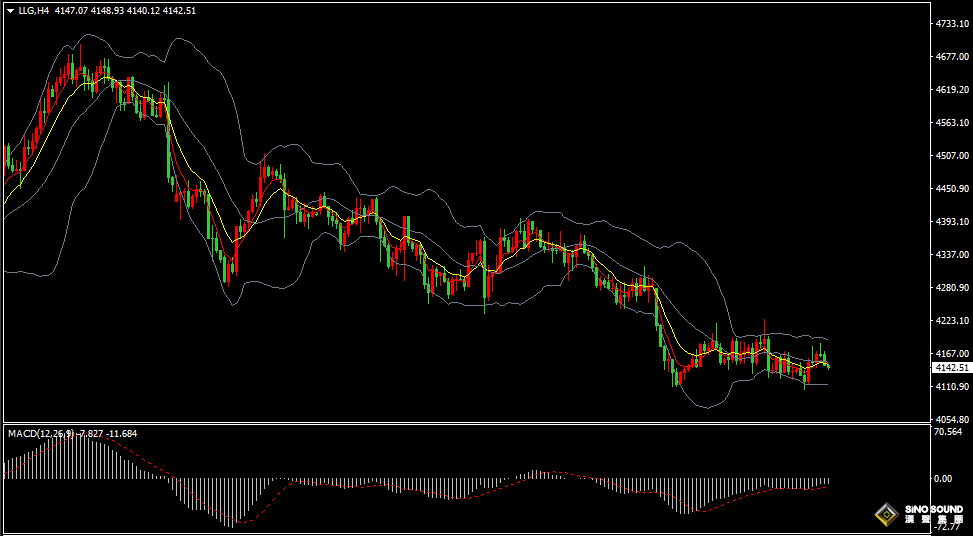
On the 4-hour gold chart, the three BOLLinger Bands are flattening. The short-term EMA5 and EMA10 are intertwined and flat. The MACD negative momentum histogram has narrowed, and RSI oscillates around the 45 level. For short-term trading, watch the impact of the Fed meeting minutes tonight as volatility is set to pick up. Intraday, gold is expected to trade within the $4125-$4185 consolidation range. A break to the upside would target $4195-$4205 or near $4220; a downside break would target $4115-$4110 or near $4100.
Key economic data and events to watch today:
14:00 Germany August seasonally adjusted industrial output MoM
14:00 UK September Halifax seasonally adjusted house price index MoM
14:45 France August trade balance
22:30 US EIA crude oil inventories for the week ending Oct 2
22:30 US EIA Cushing crude oil inventories for the week ending Oct 2
22:30 US EIA Strategic Petroleum Reserve inventories for the week ending Oct 2
23:00 US September NY Fed 1-year inflation expectations
01:00 (next day) US 10-year Treasury auction high yield for Oct 7
01:00 (next day) US 10-year Treasury auction bid-to-cover ratio for Oct 7
02:00 (next day) Federal Reserve releases monetary policy meeting minutes
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.