

Spot gold opened at $4116.11 per ounce in Tuesday’s ASIan session, hitting an intraday low of $4113.32 per ounce. It kept oscillating higher and peaked at $4148.80 per ounce. At press time, gold traded around $4140 per ounce, up 0.61% for the day.
The US Dollar Index climbed during the session and was last quoted at 101.39, rising 0.20%, approaching its highest level since July 29 this year. The 2-year US Treasury yield edged up by 0.5 bASIs points to 4.938%; the 10-year US Treasury yield rose and stayed near 5.243%; the 30-year US Treasury yield increased by 0.3 bASIs points to 5.553%.
International crude oil rose first then fell. WTI crude was last at $92.74 per barrel, down 0.35%; Brent crude stood at $97.91 per barrel, down 0.45%. US Natural Gas CFD was quoted at $3.103 per MMBtu, a drop of 1.367%.
In today’s stock market, the three major A-share indices in China fluctuated throughout the day. The combined turnover of the two markets reached 1.41 trillion yuan, a decrease of 293.6 billion yuan from the previous trading day. At the close, the Shanghai Composite Index gained 6.83 points or 0.18% to 3830.45; the Shenzhen Component Index rose 43.19 points or 0.34% to 12901.95; the ChiNext Index climbed 2.74 points or 0.09% to 3142.56.

Hong Kong stocks fluctuated at low levels throughout the day, and the Hang Seng Tech Index hit an intra-year low during the session. The total market turnover of the Hang Seng Index reached HK$184.63 billion. At the close, the Hang Seng Index fell 118.94 points or 0.48% to 24523.57; the Hang Seng Tech Index dropped 46.38 points or 1.08% to 4249.62; the Hang Seng China Enterprises Index lost 38.03 points or 0.46% to 8178.81; the Hang Seng China Red Chip Index rose 17.41 points or 0.43% to 4057.26.
European stock markets opened in the afternoon. France’s CAC40 opened 0.05% higher, Spain’s IBEX35 opened 0.26% higher, Italy’s FTSE MIB opened 0.30% higher, the UK FTSE 100 opened 0.24% higher, Germany’s DAX30 opened 0.13% lower, and the Euro Stoxx 50 opened 0.28% higher.
In the afternoon, Shanghai Gold Exchange’s Au(T+D) closed down 1.12% at 897.15 yuan per gram; Ag(T+D) closed down 2.09% at 14801.0 yuan per kilogram.
The latest data released during the session showed Switzerland’s September KOF Economic Barometer came in at 109.1, versus an expectation of 106.1. The prior reading was revised from 106.7 to 107.5. Spain’s preliminary September CPI YoY stood at 4.9%, compared with a forecast of 4.6% and the previous reading of 4.30%. Spain’s preliminary September Harmonized CPI YoY was 5%, versus an estimate of 4.9% and the prior value of 4.60%.
UK August Bank of England mortgage approvals reached 54,918, below the forecast of 56,100. The prior figure was revised from 56,053 to 55,928. Eurozone September Industrial Sentiment Index was -3.8, better than the expectation of -4.7. The previous reading was revised from -5.3 to -5. Eurozone September Economic Sentiment Index printed at 97.9, lower than the forecast of 99 and the prior reading of 98.4.
Spain’s inflation grew faster than expected, with consumer prices rising 5% year-on-year in September, up from 4.6% in August. This marked the highest level since February 2023 and was well above the European Central Bank’s 2% target, reinforcing market expectations for further interest rate hikes. Other Eurozone member states may also release higher inflation figures.
UK mortgage approvals for August fell for the second consecutive month, hitting the lowest level since December 2023. Major mortgage rates have now approached 6%, showing the growing impact of borrowing costs and adding further pressure to the real estate market.
Early this morning, the Reserve Bank of Australia lifted its cash rate by 25 bASIs points to 4.60%, the highest level in roughly 15 years, and signaled that further rate hikes may still be needed. The rate hike was in line with market expectations. It was the RBA’s fourth rate increase this year, bringing the total tightening to 100 bASIs points.
RBA Governor Bullock stated that the board considered both keeping rates unchanged and raising rates by 25 bASIs points at this meeting. The board will raise rates again if necessary. If inflation declines, further hikes may no longer be required.
According to comments, global bond markets are undergoing a new round of repricing. Rising energy prices push up inflation pressure, and the AI investment boom strengthens growth expectations. Investors are rebalancing asset allocations and betting on a new environment of higher interest rates for longer.
In September, major global sovereign bond markets are heading for one of their worst months in years. The 2-year US Treasury yield has risen by nearly 60 bASIs points in September, marking its largest monthly gain since early 2023. Short-term bond yields in major economies including France, Germany, the UK and Australia have also seen their biggest monthly increases since the energy shock triggered by the Iran conflict.
Statistics show Saudi Arabia’s annualized crude oil export revenue this year stands at approximately $210 billion, up 40% from $150 billion before the conflict. Although export volumes have not fully recovered, high oil prices have delivered a sizeable windfall of oil revenue for Saudi Arabia.
The speaker of Iran’s parliament warned that if Iran cannot sell oil, no country in the region should be allowed to sell oil. If Iran lacks security guarantees, regional infrastructure will also be unsafe.
Reports say US troops will withdraw from their last remaining bases in Iraq by this Wednesday, ending more than 20 years of military presence since the 2003 invASIon of Iraq. Reportedly, this withdrawal plan was agreed between the US and Iran in 2024 and continued by the Trump administration. As the US and Iran remain in a state of conflict, Iran and its allies have viewed the US troop pullout as a strategic victory.
A spokesperson for the Commander-in-Chief of the Iraqi Armed Forces stated that US and coalition forces will complete their withdrawal from Iraq by September 30 in accordance with the previously agreed timetable. There are no foreign military bases left on Iraqi territory. With the conclusion of the coalition mission in Iraq, security cooperation between Iraq and relevant countries will shift to a new bilateral partnership framework.
In the international gold market, precious metals were previously sold off as US Treasury yields climbed to multi-decade highs and crude oil advanced. Meanwhile, the Federal Reserve will keep interest rates higher for longer, dampening market appetite for non-yielding assets. Gold remains near its lowest level since early August.
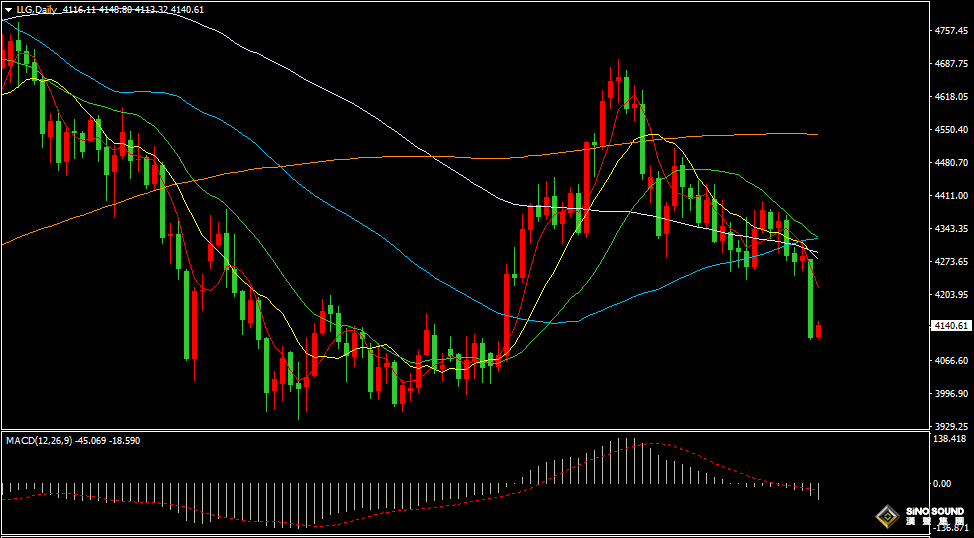
On the daily gold chart, after a sharp drop yesterday, gold rebounded slightly today, yet the overall trend remains weak and choppy. From daily indicators, the 5-day and 10-day moving averages have crossed below the 100-day moving average. MACD negative momentum bars are gradually expanding, while the RSI hovers around the 36 level.
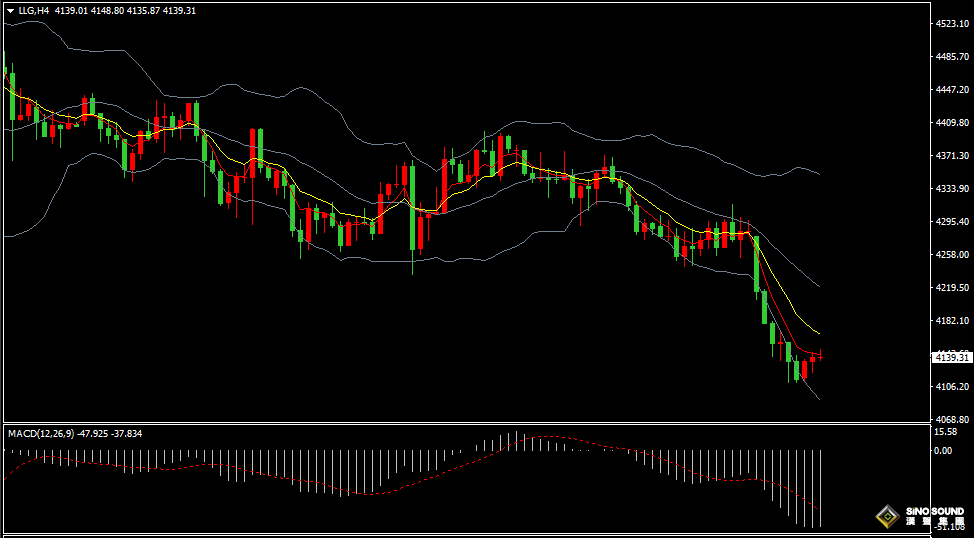
On the 4-hour gold chart, gold rebounded from the lower BOLLinger Band. The short-term moving averages EMA5 and EMA10 remain in a bearish arrangement, yet their downward momentum has slowed. MACD negative momentum bars stay at high volume, and RSI has rebounded to near the oversold level of 30. For short-term evening trading, gold is expected to oscillate within the 4110-4165 range. A breakout to the upside will target 4185-4200 or near 4220; downside targets are 4100-4085 or near 4070.
Key financial data and events to watch tonight:
20:30 Canada July GDP MoM
21:00 US July FHFA House Price Index MoM
21:00 US July S&P/CS 20-City Composite Home Price Index YoY
22:00 US August JOLTS Job Openings
22:00 US September Conference Board Consumer Confidence Index
01:00 (Next Day) Fed’s Goolsbee Speaks
01:00 (Next Day) OpenAI CEO Altman Speaks
01:30 (Next Day) Fed’s Musalem Speaks
02:00 (Next Day) Fed’s Williams Speaks
04:30 (Next Day) US API Weekly Crude Oil Stock Change for the week ending Sep 25
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.