

During Monday’s ASIan trading session, spot gold opened at $4278.38 per ounce with an intraday high of $4278.57 per ounce. Gold remained under pressure throughout the early session and broke below the $4200 threshold, hitting a low of $4140.43 per ounce. At press time, gold was consolidating near $4143, down more than 3% on the day. Spot silver also slumped sharply in tandem, currently trading around $61.10 per ounce with an intraday drop exceeding 5%.
The U.S. Dollar Index edged higher at the start of the session, peaking at 101.20. It then fell rapidly after the European market opened, bottoming out at 100.99, and was last quoted at 101.08 with its gain narrowed to 0.05%. U.S. Treasury yields surged across maturities. The 2-year Treasury yield rose 4.9 bASIs points to 4.913%; the 10-year yield climbed 6.4 bASIs points to 5.231%; the 30-year yield increased 3 bASIs points to 5.532%.
International crude oil gapped higher at the market open. WTI crude was last at $95.43 per barrel, up 3.35%; Brent crude stood at $100.65 per barrel, rising 3.41%. U.S. natural gas CFD prices gapped down to $3.111 per MMBtu, a drop of 4.424%.
In equities markets, China’s three major A-share indices opened lower and moved down, with a slight rebound late in the session. Total turnover on the Shanghai and Shenzhen markets reached 1.7 trillion yuan, an increase of 49.4 billion yuan from the previous trading day, and more than 4,500 stocks across the market closed lower. At the close, the Shanghai Composite Index fell 64.75 points, or 1.67%, to 3823.62. The Shenzhen Component Index dropped 458.22 points, or 3.44%, to 12858.75. The ChiNext Index shed 149.12 points, or 4.53%, to 3139.82.

Hong Kong stocks traded in a volatile range for the whole day, with Hang Seng Index turnover hitting HK$177.482 billion. At the close, the Hang Seng Index rose 132.42 points, or 0.54%, to 24642.51. The Hang Seng Tech Index fell 15.78 points, or 0.37%, to 4296.0. The Hang Seng China Enterprises Index gained 51.06 points, or 0.63%, to 8216.84. The Hang Seng China Red-Chip Index climbed 52.33 points, or 1.31%, to 4039.85.
European stock indices opened in the afternoon. Germany’s DAX 30 opened 0.34% higher, UK FTSE 100 up 0.40%, France CAC 40 up 0.45%, Euro Stoxx 50 up 0.18%, Spain IBEX 35 up 0.17%, and Italy FTSE MIB down 0.05%.
Shanghai Gold Exchange’s Gold T+D closed down 2.88% at 900.35 yuan per gram. Silver T+D closed down 5.0% at 14853.0 yuan per kilogram.
Latest data shows the People’s Bank of China conducted 139 billion yuan in 7-day reverse repos, 661 billion yuan in overnight reverse repos and 300 billion yuan in 14-day reverse repos. With 600 billion yuan of 1-year Medium-term Lending Facility (MLF) and 660.3 billion yuan of 7-day reverse repos maturing on the day, a net liquidity withdrawal of 160.3 billion yuan was realized.
Data from the National Bureau of Statistics shows that the operating revenue of industrial enterprises above designated size rose by 6.6% year-on-year in the January-August period, driving industrial profit growth of 15.7% year-on-year. The cumulative growth rate has maintained a double-digit rise since the start of this year.
After U.S. President Trump rejected Iran’s latest proposal to reopen the Strait of Hormuz, oil prices advanced during Monday’s ASIan session, stoking inflation fears and triggering fresh selling in U.S. Treasuries. Rate-sensitive 2-year Treasury yields rose 5 bASIs points to 4.90%, while the 10-year yield climbed 4 bASIs points to 5.20%. Prior to this, U.S. Treasury yields across all maturities had surged to multi-year highs last week.
On the other hand, eurozone government bond yields edged lower. Multiple eurozone nations will hold bond auctions this week: Belgium on Monday, the Netherlands and Italy on Tuesday, Germany on Wednesday, Spain and France on Thursday. Analysts note the eurozone bond market remains fragile, and economic data and bond supply scheduled for this week may amplify current market anxiety.
Major economic data due this week are headlined by U.S. non-farm payrolls, with core PCE and ADP serving as leading indicators. The U.S. August core PCE price index annual rate, August personal spending monthly rate, final Q2 real GDP annualized rate, final Q2 real personal consumption expenditures annualized rate and final Q2 core PCE annualized rate will be released on Wednesday evening. U.S. September seasonally adjusted non-farm payrolls, unemployment rate and average hourly earnings will come out on Friday evening.
Market expectations point to 100,000 new jobs added in September, lower than August’s 162,000. The unemployment rate is projected to hold at 4.1%, and average hourly earnings are expected to rise 0.3% month-on-month. Markets expect August core PCE to increase 3.4% year-on-year, higher than July’s 3.3%. Personal spending is forecast to rise 0.4% month-on-month, and personal income up 0.45%. Analysts say the U.S. labor market has not shown a marked slowdown entering September and remains expanding, with resilient employment underpinned by still-strong economic demand.
On international developments, reports state the Iranian delegation’s agenda does not include plans for a new round of negotiations with the U.S. The Iranian foreign minister will return to Iran on Tuesday after finishing his scheduled itinerary.
U.S. President Trump said he spoke with Ukrainian President Zelensky and told him to "ease up" on attacks against oil refineries. He blamed diesel shortages on Ukraine’s strikes on Russian refineries. The U.S. is considering a ban on diesel exports, which pushed gasoline prices slightly higher today.
Gold fundamentals: Higher oil prices have aggravated inflation concerns and reinforced market bets on further Fed rate hikes. The combination of elevated bond yields and high oil prices continues to weigh on gold. Spot gold dropped nearly 3% while spot silver slumped 5% during the session.
A string of U.S. employment and inflation data will be in focus this week. Figures stronger than expected may keep pushing Treasury yields higher and further suppress gold prices.
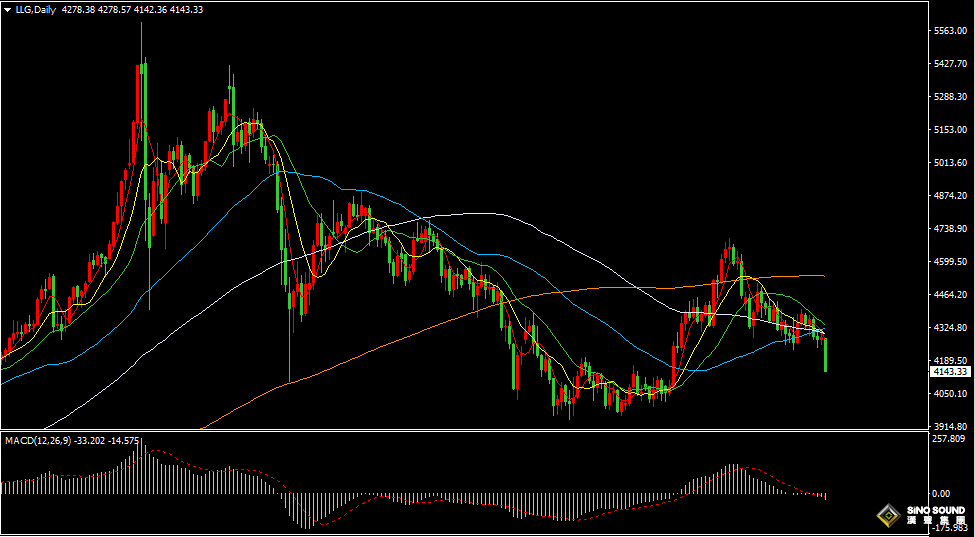
On the daily chart, gold plunged sharply and broke below $4200, hitting a low near $4142, the weakest level since August 6. Daily indicators show gold has fallen below all short, medium and long-term moving averages. The 5-day MA and 100-day MA are gradually forming a death cross. The MACD histogram for negative momentum is expanding, and the RSI has slid to around 35.
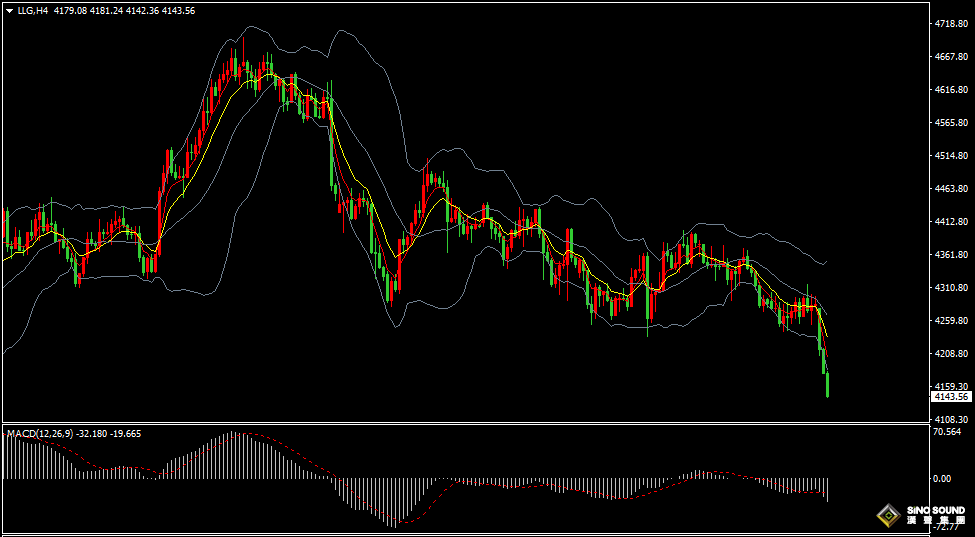
On the 4-hour chart, gold has been sliding along the lower BOLLinger Band. Short-term EMA5 and EMA10 form a downward bearish arrangement. The MACD negative histogram keeps growing, and RSI has crossed below the oversold line to around 25. For short-term trading, gold is expected to fluctuate within the 4115–4200 range. A breakout upward would target 4215–4225 or near 4235. Downside targets lie at 4105–4100 or near 4085.
Key financial events and data to watch tonight:
TBC: ECB President Lagarde testifies
18:00: Bank of England Deputy Governor Ramsden speaks
22:30: U.S. September Dallas Fed Manufacturing Index
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.