

Overnight, strong US PMI data coupled with hawkish remarks from Federal Reserve officials further reinforced market expectations for monetary policy tightening. The US dollar strengthened and US Treasury yields moved higher, pressuring spot gold to trend downward. Gold prices broke below the $4,300 threshold, hitting a low of $4,275.05 per ounce and finally closing at $4,287.18 per ounce, down 1.63%. Spot silver fell in tandem to settle at $64.40 per ounce, a drop of 3.89%.
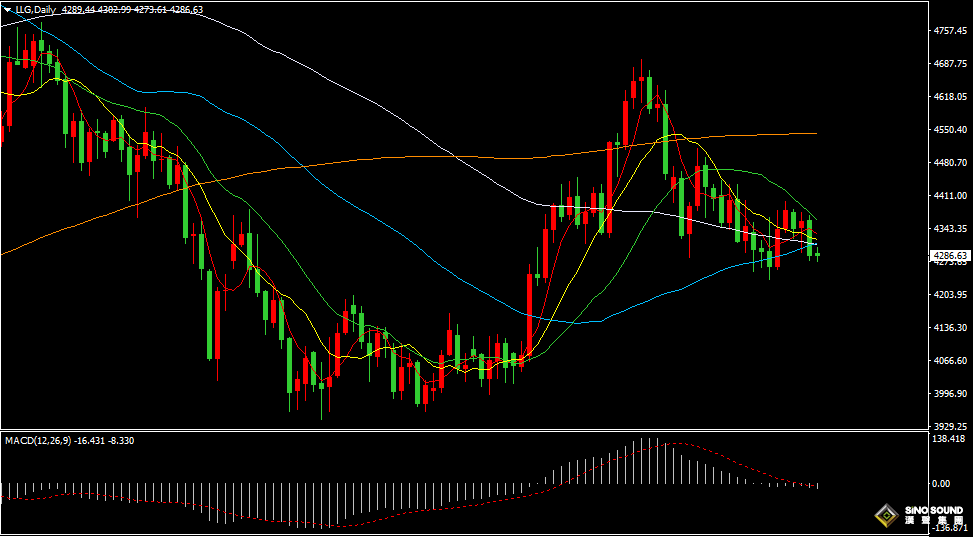
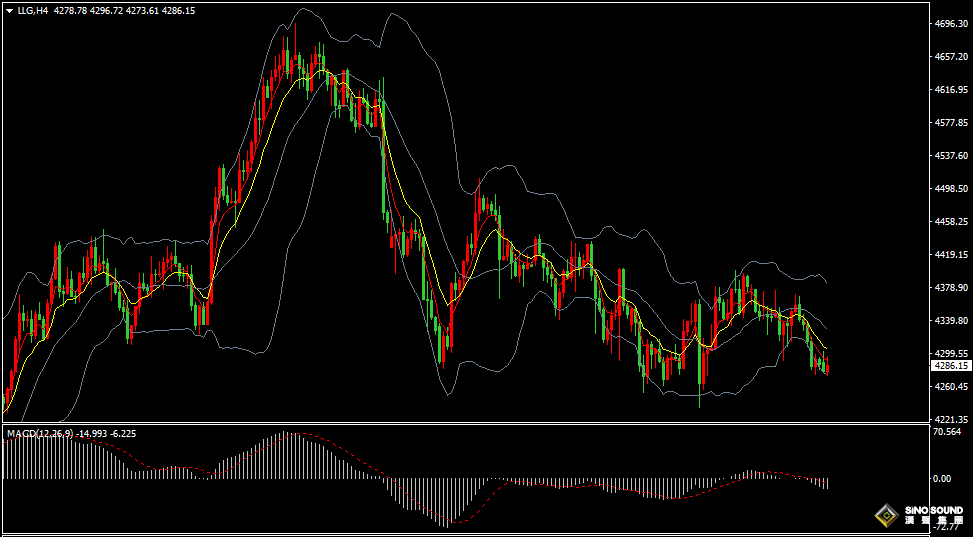
During Thursday’s ASIan session, spot gold opened at $4,289.44 per ounce. It hit an intraday high of $4,302.99 per ounce and a low of $4,273.61 per ounce. Gold was trading near $4,286 at press‑time.
The US Dollar Index surged overnight, breaking above the 101 level to hit a two‑month high of 101.23. It closed at 101.13, gaining 0.59%. US Treasuries faced heavy selling pressure, with yields jumping across the board and approaching multi‑year highs not seen since 2007. The 2‑year Treasury yield rose 14.5 bASIs points to close at 4.901%; the 10‑year yield climbed 15.3 bASIs points to 5.116%; the 30‑year yield advanced 9.6 bASIs points to 5.399%.
Iran stated it would not reopen the Strait of Hormuz until its conditions are met. International crude oil halted a six‑day losing streak and turned higher. WTI crude settled at $92.75 per barrel overnight, up 3.33%. Brent crude closed at $98.43 per barrel, rising 3.91%. US natural gas CFDs finished at $3.177 per million British thermal units, an increase of 0.443%.

All three major US stock indices closed lower overnight. The Dow Jones Industrial Average fell 351.27 points or 0.68% to 51,512.42. The S&P 500 dropped 58.25 points or 0.75% to 7,706.39. The Nasdaq Composite lost 308.24 points or 1.13% to 26,936.04.
Major European equity markets ended in negative territory. Germany’s DAX 30 fell 0.73% to 25,411.85. The FTSE 100 in the UK edged up 0.02% to 10,710.25. France’s CAC 40 slipped 0.39% to 8,123.41. The Euro Stoxx 50 declined 0.38% to 6,300.85. Spain’s IBEX 35 lost 0.81% to 19,631.33. Italy’s FTSE MIB fell 0.15% to 52,016.50.
Gold T+D on the Shanghai Gold Exchange closed down 0.96% at RMB 926.76 per gram overnight. Silver T+D fell 2.66% to RMB 15,701.0 per kilogram. In Thursday’s early session, Gold T+D opened 0.78% lower at RMB 928.44 per gram, while Silver T+D was down 2.66% at RMB 15,701.0 per kilogram.
Holdings of SPDR Gold Trust, the world’s largest gold ETF, rose by 0.855 tonnes from the previous session to 1,056.836 tonnes. iShares Silver Trust, the world’s largest silver ETF, saw its holdings decrease by 25.28 tonnes to 15,350.6 tonnes.
The People’s Bank of China set the following central parity rates for foreign exchange today: USD/CNY at 6.7489, up 21 points (CNY depreciation); EUR/CNY at 7.6631, down 304 points; HKD/CNY at 0.86054, up 3.9 points; GBP/CNY at 8.9153, down 527 points; AUD/CNY at 4.7387, down 408 points; CAD/CNY at 4.7735, down 21 points; 100JPY/CNY at 4.2590, down 164 points; CNY/RUB at 12.6264, up 605 points; NZD/CNY at 3.8219, down 234 points; CNY/MYR at 0.60657, up 14 points; CHF/CNY at 8.1662, down 268 points; SGD/CNY at 5.2598, down 125 points.
The People’s Bank of China conducted RMB 51.5 billion in 7‑day reverse repos today. With RMB 162 billion of 7‑day reverse repos maturing, a net liquidity withdrawal of RMB 110.5 billion took place for the day. A net liquidity injection of RMB 19.5 billion has been recorded for this week.
Latest overnight data showed the preliminary September S&P Global US Manufacturing PMI printed at 57 versus an expected 53.6 and a prior reading of 53.9. The preliminary September S&P Global US Services PMI stood at 58.7, compared with a forecast of 56 and a prior reading of 56.5. The S&P Global US Composite PMI preliminary reading came in at 58.4, hitting a five‑year high from the prior 56.
According to market commentary, surging new orders pushed US business activity in September to its highest level in more than five years. Nevertheless, robust demand has put pressure on supply chains and driven prices higher. The PMI readings are consistent with the US economy growing at an annualized pace of roughly 5%.
Fed Governor Barr stated overnight that risks to achieving the inflation target have risen and further interest‑rate hikes may be necessary. The CME FedWatch Tool showed market odds of a rate hike at the Fed’s October 27‑28 meeting rose from around 50% to 73%.
The Fed’s latest quarterly survey found that surveyed firms’ average expected price hikes for this year climbed to 5.3%, up from 4.6% in the second quarter and 3.6% at the start of the year. Average expected price increases for next year also advanced to 4.5% from 4.1% in Q2 and 3.6% at the beginning of the year. Monetary policy has become the top concern among corporate finance officers, with small‑and‑medium‑sized enterprises particularly affected by tightening financing conditions.
The Secretary‑General of the International Gas Union stated that global gas markets are pricing in tight supply conditions potentially peRSIsting well beyond winter, as the Iran‑related conflict disrupts liquefied‑natural‑gas exports from the Gulf region and complicates Europe’s efforts to replenish gas inventories. Europe is competing for ASIan LNG cargoes at higher prices amid the need to rebuild storage levels.
US Secretary of State Rubio said talks between the United States and Iran held at the United Nations yielded no breakthroughs and negotiations will require more time. The United States will continue taking measures to keep the Strait of Hormuz open.
Iranian President Pezeshkian addressed the UN General Assembly, accusing Trump of resorting to threats and coercion and making clear that Iran will not yield under such pressure. US representatives walked out during his speech.
The Secretary of Iran’s Supreme National Security Council said Iran is in no rush for negotiations. The Strait of Hormuz will remain closed and no talks will proceed until Iran’s stated conditions are satisfied. Iran warned neighbouring countries against complying with US‑imposed restrictions on airlines.
Chinese President Xi Jinping arrived in Washington onboard a special aircraft yesterday afternoon for a state visit to the United States at the invitation of US President Donald Trump. Upon President Xi and Madam Peng Liyuan’s arrival at Andrews Air Force Base, President Trump and his wife Melania gave them a warm welcome. President Trump described President Xi as a great leader and called it a great moment, voicing anticipation for advancing bilateral relations. President Xi noted that China and the United States are both great nations with deeply intertwined interests and ought to be partners rather than rivals. He looked forward to in‑depth exchanges with President Trump on major issues bearing on bilateral ties and the global situation, and to expanding exchanges and cooperation across various sectors.
From the daily chart perspective, gold closed with a bearish candle to a new weekly low, breaking below the 5‑day, 10‑day, 50‑day and 100‑day moving averages. On daily indicators, MACD negative momentum bars are expanding, while the RSI is flat near the 44 level.
On the 4‑hour chart, all three BOLLinger Bands slope downward, with gold oscillating near the lower band. Short‑term EMA5 and EMA10 are pointing bearishly lower. MACD negative momentum bars keep growing, and RSI flattens after slipping to the 40 level. For intraday short‑term trading, gold is expected to consolidate within the range of 4260‑4305. A breakout to the upside would target 4315‑4320 or near 4325. Downside targets sit at 4250‑4240 or near 4230.
Key economic data and events for today:
15:30 SNB Interest Rate Decision
16:00 Germany September IfO Business Climate Index
16:10 Fed’s Williams participates in a discussion
18:00 UK September CBI Distributive Trades Survey‑Retail Sales Balance
20:00 Fed’s Barkin takes part in a discussion
20:30 Canada July Monthly Retail Sales
20:30 US Initial Jobless Claims for the week ending September 19
20:30 US Q2 Current Account Balance
20:50 Fed’s Halmack delivers a speech
22:00 US August Annualized New Home Sales
22:10 Fed’s Paulson gives a speech
22:30 US EIA Natural Gas Stocks for the week ending September 18
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.