

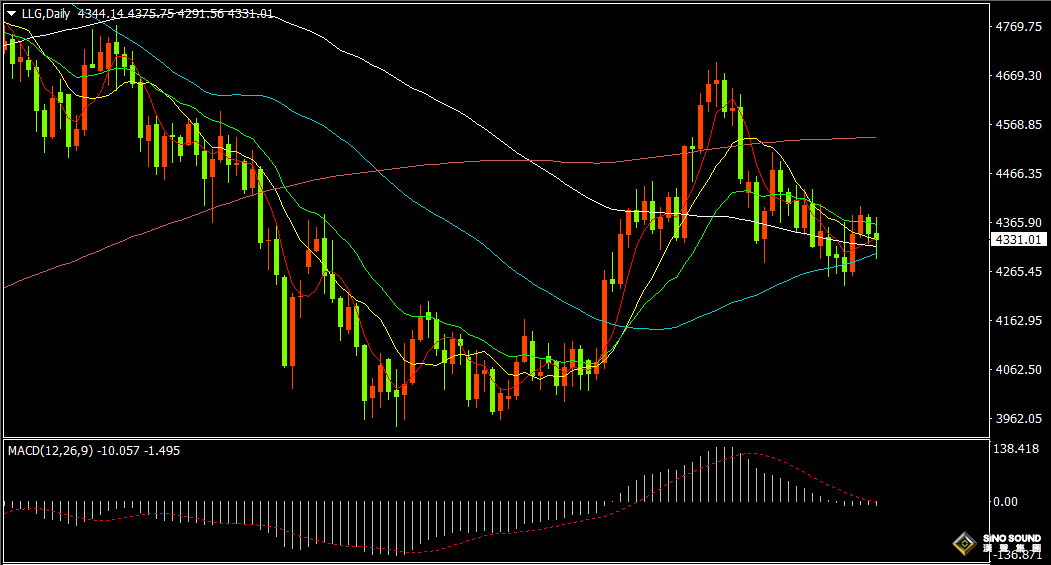
Today (Tuesday), spot gold opened the ASIan session at $4344.14 per ounce. It peaked at $4375.75 in the early morning before retreating. Gold then oscillated down from the daily high and once broke below the $4300 threshold, hitting a low of $4291.56 per ounce. At press time, gold has moved back above $4300 and is trading near $4331, with the intraday loss narrowed to 0.29%.
The US Dollar Index consolidated sideways intraday and briefly surged to 100.67 in the afternoon before pulling back. It now stands at 100.46, with its gain trimmed to 0.04%. The 2-year US Treasury yield rose by 0.1 bASIs point to 4.752%; the 10-year US Treasury yield fell by 0.8 bASIs point to 4.946%; the 30-year US Treasury yield dropped by 1.6 bASIs points to 5.27%.
WTI and Brent crude oil climbed in the morning but turned downward in the afternoon. WTI crude is quoted at $91.41 per barrel, down 0.53%; Brent crude is at $95.86 per barrel, down 0.06%. US natural gas CFD is at $2.988 per MMBtu, up 0.10%.
In the stock market, the three major A-share indices opened higher and moved lower, and all dipped into negative territory near the close. Total turnover on the Shanghai and Shenzhen markets exceeded 2.1 trillion yuan, with more than 3,000 stocks declining. The Shanghai Composite Index rose 2.22 points, or 0.06%, to 3952.13. The Shenzhen Component Index fell 6.29 points, or 0.05%, to 13723.74. The ChiNext Index edged up 0.34 points, or 0.01%, to 3399.93.

Hong Kong’s Hang Seng Index surged then retreated. At the close, total market turnover reached HK$249.214 billion. The Hang Seng Index gained 45.04 points, or 0.18%, to 25087.75. The Hang Seng Tech Index rose 14.92 points, or 0.34%, to 4438.21. The Hang Seng China Enterprises Index added 22.97 points, or 0.28%, to 8362.6. The Hang Seng Red Chip Index fell 28.77 points, or 0.71%, to 4029.97.
European major stock indices opened higher in the afternoon. Germany’s DAX30 opened 0.13% higher, the UK FTSE 100 rose 0.21% at the open, France’s CAC40 gained 0.22%, the Euro Stoxx 50 rose 0.16%, Spain’s IBEX35 climbed 0.17%, and Italy’s FTSE MIB edged up 0.02%.
In the afternoon, Shanghai Gold Exchange’s Gold T+D closed down 1.06% at 931.3 yuan per gram, and Silver T+D closed 1.83% lower at 15850.0 yuan per kilogram.
The latest data released intraday showed UK public sector net borrowing stood at £18.268 billion in August, versus the forecast of £15.55 billion and the prior reading of £1.8 billion. UK borrowing in the first five months of this fiscal year exceeded expectations, with the fiscal deficit climbing to £77.3 billion (US$100 billion), £8.1 billion higher than the Office for Budget Responsibility’s March forecast. Analysts said overspending will keep pushing up borrowing in the coming years, which may limit the new UK government’s policy ambitions.
Italy’s national statistics institute confirmed that the country’s deficit ratio stood at 3.1% last year. Though still lower than comparable economies such as France, it exceeds the EU’s 3% ceiling, delaying Italy’s exit from the EU’s excessive deficit procedure. The mechanism is an EU supervision framework, equivalent to a "blacklist" for countries with severe deficits.
RBA Governor Bullock delivered a speech, stating that monetary policy can hardly cope with supply shocks and must respond to secondary inflation effects. The AI boom is amplifying excess demand in Australia, and the AI productivity boom is still in its early phase. Inflation risks are emerging in the Middle East alongside excessive domestic demand.
Foreign media analysis said Germany’s stock market has underperformed among major European markets. European equities remained sluggish as investors awaited updates on potential US-Iran talks during this week’s UN General Assembly, while US stock index futures traded cautiously.
Foreign media poll data showed that with roughly six weeks left before the US midterm elections, President Trump’s approval rating has fallen to a historic low of 32%, down 15 percentage points from 47% in the same poll at the start of his second term. Against the backdrop of the controveRSIal Iran war, voters are growing dissatisfied with Trump’s handling of the cost-of-living crisis.
It is reported that the Trump administration is pushing a $10 billion Middle East energy infrastructure investment plan. The US plans to contribute $5 billion first and seek matching funds from Saudi Arabia, the UAE, Qatar, Bahrain, Kuwait, Oman, Iraq and Jordan. The fund aims to help Middle Eastern countries rebuild energy infrastructure damaged in the nearly seven-month Iran war and reduce reliance on the Strait of Hormuz for oil and gas transportation.
Iranian President Pezeshkian is set to address the UN tomorrow, yet the US has refused to issue visas for Pezeshkian’s UN communications team. US Treasury Secretary Bessent said the US will fully "ban" Iranian airlines starting Wednesday. Any airport, fuel supplier, ground handling company or ticketing agency that continues to serve Iranian carriers may lose access to the US dollar financial system under US secondary sanctions. Whether this measure can ground Iranian airlines ultimately depends on enforcement by governments, airports and service providers.
On the daily gold chart, gold traded in a volatile range. It once dipped below the 100-day moving average but rebounded back above it, showing fierce battles between bulls and bears. From daily indicators, the MACD negative momentum histogram remains relatively small, and the RSI hovers around the 48 level.
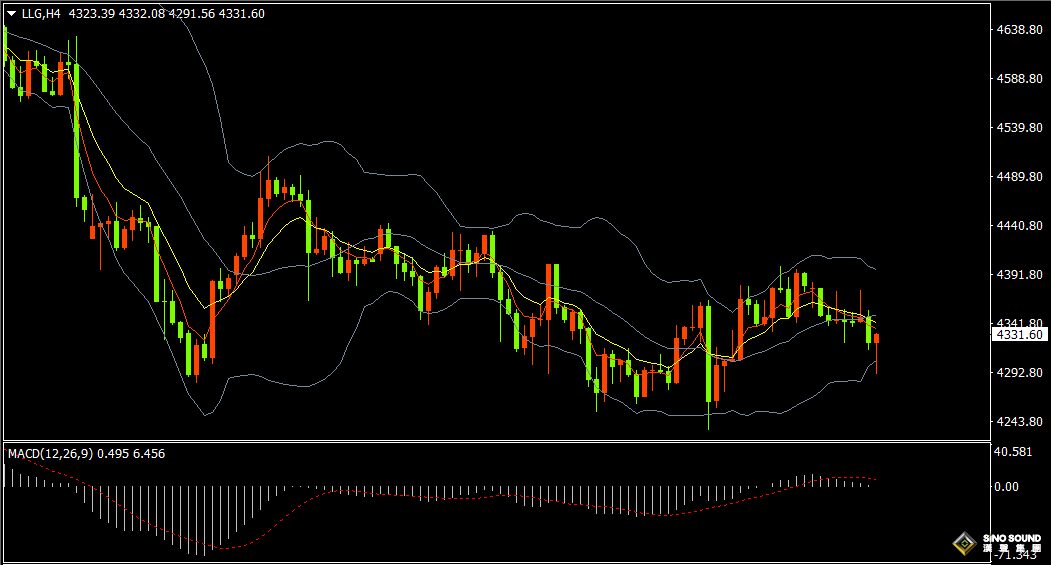
On the 4-hour gold chart, gold is oscillating between the middle and lower bands of the BOLLinger Bands. The short-term moving averages EMA5 and EMA10 have formed a bearish crossover. The MACD momentum histogram shrinks near the zero line, and the RSI flattens near the 45 level. For evening short-term trading, gold is expected to consolidate within the 4290-4370 range. A breakout to the upside will target 4385-4400 or near 4415; a downside breakout will target 4280-4270 or near 4255.
Key Economic Data & Events for Tonight:
18:00 UK CBI Industrial Orders Balance September
19:00 ECB President Lagarde Speaks
20:15 US ADP Employment Change for the week ending September 5
22:00 Eurozone Flash Consumer Confidence September
22:00 US Richmond Fed Manufacturing Index September
22:05 Fed’s Williams Speaks
22:20 Fed’s Jefferson Speaks
01:00 Next Day Fed’s Barkin Speaks
02:30 Next Day WTI Crude Rollover
04:30 Next Day US API Crude Oil Inventories for the week ending September 18
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.