

Spot gold trended lower overnight, hitting a low of $4322.78 per ounce and closing at $4343.44 per ounce, down 0.79%. Spot silver closed at $65.98 per ounce, a drop of 0.34%. During Tuesday's ASIan session, spot gold opened at $4344.14 per ounce. The price surged briefly to $4375.75 per ounce in early trading before retreating to a low of $4334.94 per ounce. At press time, gold was trading around $4343 per ounce.
The US Dollar Index continued to edge higher overnight, peaking at 100.45 and closing at 100.42, up 0.21%. The 2-year US Treasury yield rose by 0.8 bASIs points to settle at 4.751%. The 10-year US Treasury yield fell by 4.2 bASIs points to 4.954%. The 30-year US Treasury yield dropped by 4.1 bASIs points to 5.286%.
WTI and Brent crude posted losses for the fourth consecutive trading day. WTI crude closed at $91.90 per barrel overnight, down 3.68%. Brent crude settled at $95.93 per barrel, a decline of 2.80%. US natural gas CFD closed at $2.985 per million British thermal units, falling 1.647%.
The three major US stock indexes closed higher. The Dow Jones Industrial Average rose 367.08 points, or 0.71%, to 52049.72. The S&P 500 gained 114.26 points, or 1.49%, to 7764.76. The Nasdaq Composite climbed 599.55 points, or 2.26%, to 27122.09.

Major European stock markets all closed in positive territory. Germany's DAX 30 rose 1.14% to 25584.56. The UK FTSE 100 increased 0.78% to 10741.84. France's CAC 40 advanced 0.92% to 8138.94. The EURO STOXX 50 jumped 1.33% to 6318.85. Spain's IBEX 35 rose 1.09% to 19727.16. Italy's FTSE MIB gained 1.60% to 52369.50.
Gold T+D on the Shanghai Gold Exchange closed down 0.34% at 938.1 yuan per gram overnight. Silver T+D closed 0.65% lower at 16041.0 yuan per kilogram. In early trading today, Gold T+D on the Shanghai Gold Exchange fell 0.34% to 938.1 yuan per gram. Silver T+D dipped 0.04% to 16140.0 yuan per kilogram at the opening.
Holdings of SPDR Gold Trust, the world's largest gold ETF, decreased by 1.712 tonnes from the previous session, with total holdings standing at 1055.41 tonnes. Holdings of iShares Silver Trust, the world's largest silver ETF, rose by 202.28 tonnes, bringing total holdings to 15429.26 tonnes.
Today's central parity rate of the RMB in the foreign exchange market: USD/CNY at 6.7459, down 28 pips (RMB appreciation); EUR/CNY at 7.7059, down 133 pips; HKD/CNY at 0.85974, down 5.1 pips; GBP/CNY at 8.9863, down 181 pips; AUD/CNY at 4.7850, down 41 pips; CAD/CNY at 4.7871, down 152 pips; 100JPY/CNY at 4.2794, down 104 pips; CNY/RUB at 12.4576, down 1371 pips; NZD/CNY at 3.8376, down 83 pips; CNY/MYR at 0.60576, down 3.8 pips; CHF/CNY at 8.1925, up 116 pips; SGD/CNY at 5.2687, down 33 pips.
Chicago Fed President Goolsbee said overnight that if US inflation has spread further from tariff and energy price shocks to demand, the Fed must respond unequivocally with rate hikes. Even if current pressures mainly stem from supply shocks, monetary policy cannot simply "ignore" their impacts as long as these shocks peRSIst.
US Treasury Secretary Bessent stated that he has full confidence in Fed Chair Walsh and believes Walsh will make sound decisions for the Fed's mandate. US President Trump also expressed confidence in Walsh. He added that interest rates should decline once the Iran conflict ends.
CME FedWatch Tool showed overnight that the market priced in roughly a 53% probability of another rate hike at the next meeting. The market has not ruled out further rate increases, but it has not repriced the situation as a continuous, rapid tightening cycle. At least 10 Fed officials will deliver public speeches this week. The key focus ahead lies in whether policymakers will continue to back rate moves in October or December, and whether oil prices and inflation data can push long-end yields back above 5%.
Reports say US President Trump is deeply concerned about rising diesel prices and wants to ensure Russian diesel supplies can reach global markets to ease oil price gains. Trump keeps pressuring Zelenskyy to halt attacks on Russian refineries.
Sources revealed that as Ukraine continues to strike Russian refineries, cutting oil processing volumes to multi-year lows, Russia plans to extend most of its diesel export ban beyond the end of September. This amplifies the impact of supply disruptions in the Middle East and pushes prices higher. Nevertheless, even though Russia bans diesel exports to most overseas markets, its diesel shipments to Central ASIan nations surged in August.
On the other hand, international crude oil prices have fallen recently amid optimism that Saudi Arabia's damaged East-West pipeline will resume oil transportation soon and progress has been made in US-Iran negotiation efforts. It is reported that oil and cargo volumes passing through the Strait of Hormuz over the past two weeks hit a six-month high.
Latest analysis from the International Energy Agency shows the number of countries offering direct fuel subsidies has risen from 16 four months ago to 38. The count of nations cutting energy taxes increased from 40 to 57, and 94 countries have introduced some form of consumer energy support measures. Analysts note that broader subsidies raise the fiscal buffer costs borne by governments. In the event of sustained high oil prices, temporary measures can eASIly turn into long-term fiscal burdens.
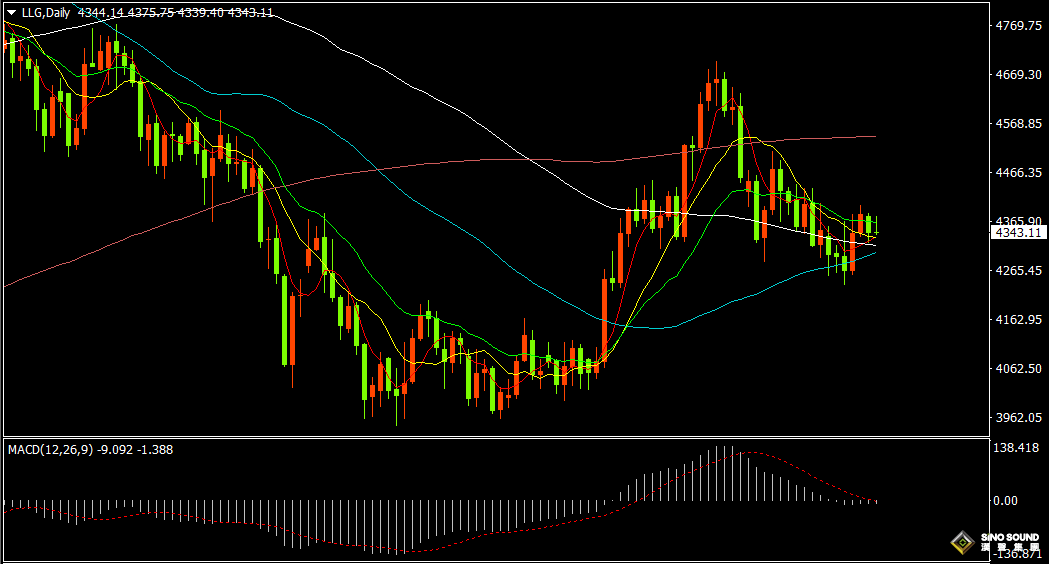
On the daily gold chart, prices pulled back for adjustment yesterday and are consolidating above the 100-day moving average at $4316, while resistance remains near the $4400 level. In terms of daily indicators, the negative MACD histogram is relatively small and the RSI indicator is hovering around the 48 level.
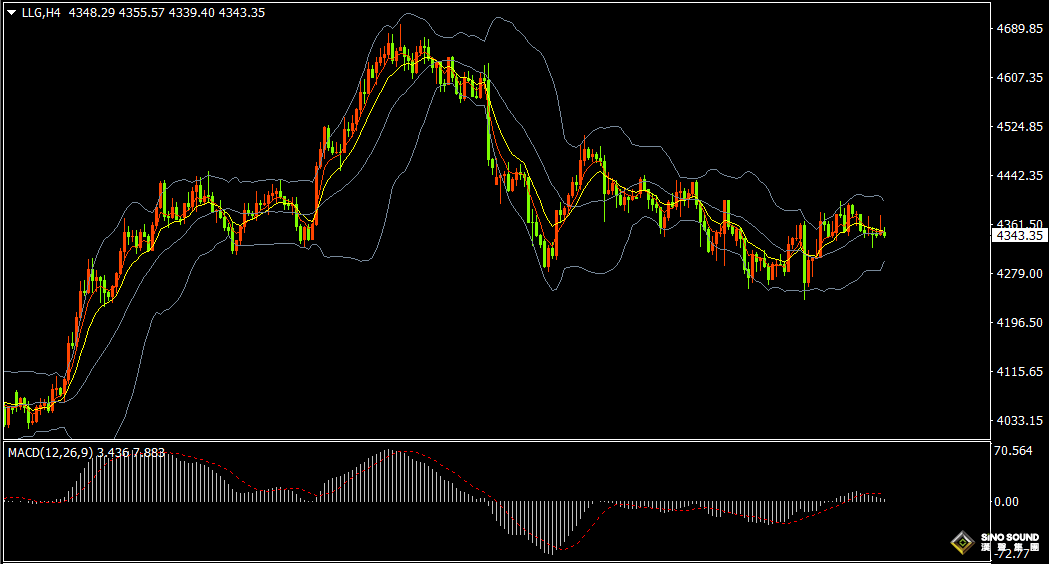
On the 4-hour gold chart, the BOLLinger Bands are starting to contract, with gold oscillating near the middle band. The short-term EMA5 and EMA10 are intertwined and flat. The positive MACD histogram is relatively small and RSI is flat around the 47 level. For intraday trading, gold is expected to trade sideways within the range of 4315-4380. A breakout to the upside would target 4395-4400 or near 4410, while a downside breakout would target 4305-4300 or near 4290.
Key economic data and events to watch today:
14:00 UK August Public Sector Net Borrowing
18:00 UK September CBI Industrial Orders Balance
19:00 ECB President Lagarde Speaks
20:15 US ADP Employment Change for the week ending September 5
22:00 Eurozone September Preliminary Consumer Confidence Index
22:00 US September Richmond Fed Manufacturing Index
22:05 Fed's Williams Speaks
22:20 Fed's Jefferson Speaks
01:00 (next day) Fed's Barkin Speaks
02:30 (next day) US Oil Contract Rollover
04:30 (next day) US API Crude Oil Inventories for the week ending September 18
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.