

Following last Friday’s US Non‑Farm Payrolls release, expectations for Federal Reserve rate hikes surged. Spot gold plunged more than $100 at one stage, hitting a low of $4365.81 per troy ounce before rebounding back above the $4400 threshold and closing at $4430.33 per troy ounce, down 0.95 %. Spot silver closed at $66.099 per troy ounce, down 1.20 %. Both gold and silver printed doji candles on their weekly charts.
Spot gold opened at $4427.17 per troy ounce during Monday’s ASIan session and reached $4435.03. It dipped to an intraday low of $4389.59 in early‑ASIan trade, then bounced back above $4400. At press time, gold consolidated near $4416.
Propelled by the blowout payroll print, the US Dollar Index spiked to 99.38 last Friday night before paring some gains and finishing at 99.15, up 0.16 %. The 2‑year Treasury yield rose 4 bASIs points to 4.379 %; the 10‑year yield climbed 1.4 bASIs points to 4.784 %; the 30‑year yield edged down 0.2 bASIs points to 5.246 %.
Amid renewed hostilities between the US and Iran, WTI and Brent crude rebounded off Friday’s intraday lows. WTI crude closed at $91.31 per barrel, trimming its loss to 0.55 % and logging a 9.40 % weekly gain. Brent crude settled at $95.89 per barrel, up 0.28 % on the day and 8.58 % week‑on‑week. US natural‑gas CFD closed at $2.936 per million British thermal units, up 0.479 % for the session and 2.051 % week‑on‑week, marking four consecutive weekly advances.

Boosted by robust payroll data, expectations for Fed rate‑hikes rose and the three major US equity indices closed lower last Friday. The Dow Jones Industrial Average fell 272.51 points or 0.51 % to 53413.60; the S&P 500 lost 29.29 points or 0.38 % to 7718.42; the Nasdaq Composite dropped 77.07 points or 0.29 % to 26506.99.
Major European equity indices traded mixed. At close, Germany’s DAX 30 rose 0.17 % to 26052.20; UK FTSE 100 was flat at 10831.77; France’s CAC 40 slipped 0.09 % to 8278.77; Euro Stoxx 50 gained 0.19 % to 6394.45; Spain’s IBEX 35 advanced 0.22 % to 20045.01; Italy’s FTSE MIB fell 0.27 % to 52105.50.
Last Friday on the Shanghai Gold Exchange, Au(T+D) closed down 1.24 % at RMB 954.77 per gram, while Ag(T+D) finished 1.27 % lower at RMB 16040.0 per kilogram. Early‑Monday trade saw Au(T+D) fall 1.61 % to RMB 951.16 per gram and Ag(T+D) drop 1.46 % to RMB 16010.0 per kilogram.
The world’s largest gold ETF, SPDR Gold Trust, saw its holdings decrease by 1.426 tonnes to 1052.056 tonnes last Friday. The world’s largest silver ETF, iShares Silver Trust, added 19.67 tonnes, with total holdings standing at 15339.36 tonnes.
Today’s central parity rates for RMB foreign‑exchange: USD‑CNY 6.7795 (+8 pips); EUR‑CNY 7.8337 (−60 pips); HKD‑CNY 0.86465 (+0.7 pips); GBP‑CNY 9.1158 (−37 pips); AUD‑CNY 4.8539 (+52 pips); CAD‑CNY 4.8713 (−136 pips); 100JPY‑CNY 4.3098 (−37 pips); CNY‑RUB 12.7929 (−1096 pips); NZD‑CNY 3.9638 (+11 pips); CNY‑MYR 0.59853 (+6.9 pips); CHF‑CNY 8.3329 (−172 pips); SGD‑CNY 5.3231 (+4 pips).
Latest figures released last Friday showed US August non‑farm payrolls added 162,000 jobs, far above the market consensus of roughly 56,000. July’s reading was also revised sharply from a previously reported loss of 23,000 to a gain of 21,000, while the unemployment rate held steady at 4.1 %.
US August unemployment stayed at 4.1 %, matching market expectations. Meanwhile, the labour‑force participation rate edged up to 61.6 %, and average weekly hours ticked higher to 34.4. Wage growth remained resilient: average hourly earnings rose 0.3 % month‑on‑month and 3.1 % year‑on‑year, signalling continued tightness in labour‑market supply‑demand dynamics.
Markets have now sharply lifted bets for a September Fed rate‑hike, with probability surging above 60 %, which will weigh on safe‑haven assets such as gold. Market focus will now shift fully to inflation data, which has become the core variable determining the Fed’s next policy move.
In response to the much‑stronger‑than‑expected August jobs report, US President Trump renewed pressure on the Federal Reserve to deliver aggressive rate cuts. He threatened to cut off trade ties with countries running trade deficits against the US should the Fed fail to comply.
Fed official Hassett noted that attention should centre on the upcoming August Consumer Price Index (CPI) print. He prefers assessing recent price momentum rather than relying solely on 12‑month year‑over‑year readings. Annualised CPI growth over the past three months stands at around 1.6 %. Should the next CPI report maintain this trend, he believes there will be solid grounds for the Fed to keep rates unchanged.
On geopolitical developments: US envoys Witkoff and Kushner held separate meetings with Putin and Zelensky. The US hopes to restart Russia‑Ukraine negotiations as soon as possible. Russian President Putin insists any peace settlement must require Ukraine to hand over all remaining territory in the Donetsk region, a position consistently rejected by Kyiv, which is unwilling to cede key fortified cities across Donbas. Russian forces have campaigned in those areas since 2014 yet have not captured those cities.
Iranian official sources stated yesterday that the Aerospace Force of the Islamic Revolutionary Guard Corps launched multiple ballistic missiles, striking one US aircraft carrier and one US destroyer. Damaged, the two US warships were forced to withdraw from the conflict zone. The targeted vessels had taken part in maritime blockades against Iran and interfered with Iranian shipping.
The Islamic Revolutionary Guard Corps stated it has taken decisive action and effective control over the Strait of Hormuz; any suspicious activity will become a target for strikes. The US represents the biggest threat to regional nations’ security and maritime trade; US claims of support and escort operations are nothing but falsehoods.
Rezaei, Secretary of Iran’s Supreme National Security Council, pointed out that the US must earn Iran’s trust for negotiations to proceed. He also noted that an agreement reached between Iran and Oman over vessel navigation in the Strait of Hormuz “will be signed in the coming days”.
Domestic news: China’s Ministry of Finance plans to issue RMB 300 billion in special treasury bonds in the near term. Eight central financial institutions including ICBC, ABC, the Export‑Import Bank of China, China Export & Credit Insurance Corporation, PICC, China Life Group, China Taiping and China Re have announced respective capital‑increase plans.
US and Canadian equity markets are closed today for the US Labor Day holiday. CME Group precious‑metal and US crude‑oil futures will close early at 02:30 Beijing Time on the 8th; equity index futures will close early at 01:00 Beijing Time on the 8th. ICE Brent crude‑oil futures will close early at 01:30 Beijing Time on the 8th. Investors are reminded to take note of the adjusted trading hours.
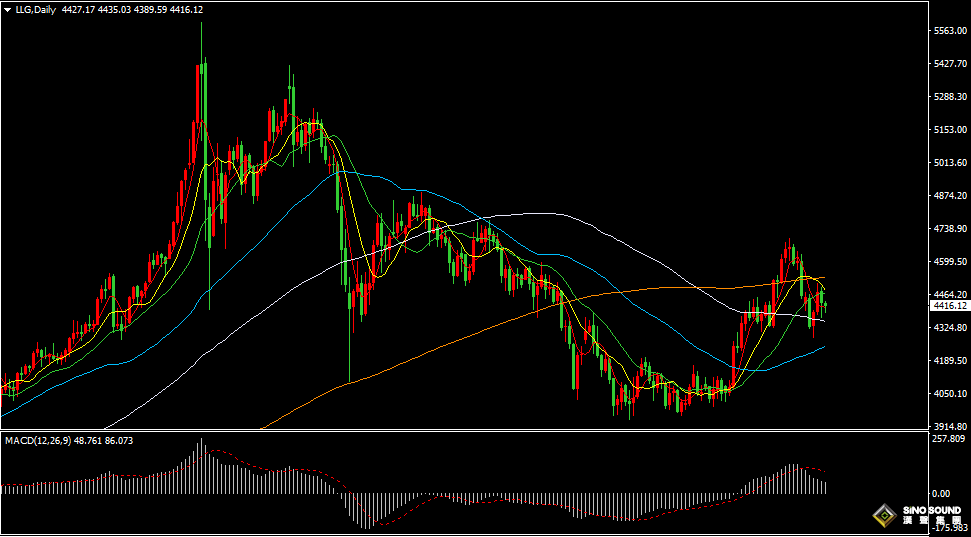
On the gold daily chart, prices dipped toward the 100‑day moving average last Friday and found some support. Fierce battles have repeatedly played out around the $4400 level, and gold is now consolidating above the 5‑day moving average. Among daily indicators, MACD positive histogram is shrinking, while RSI hovers near 51.
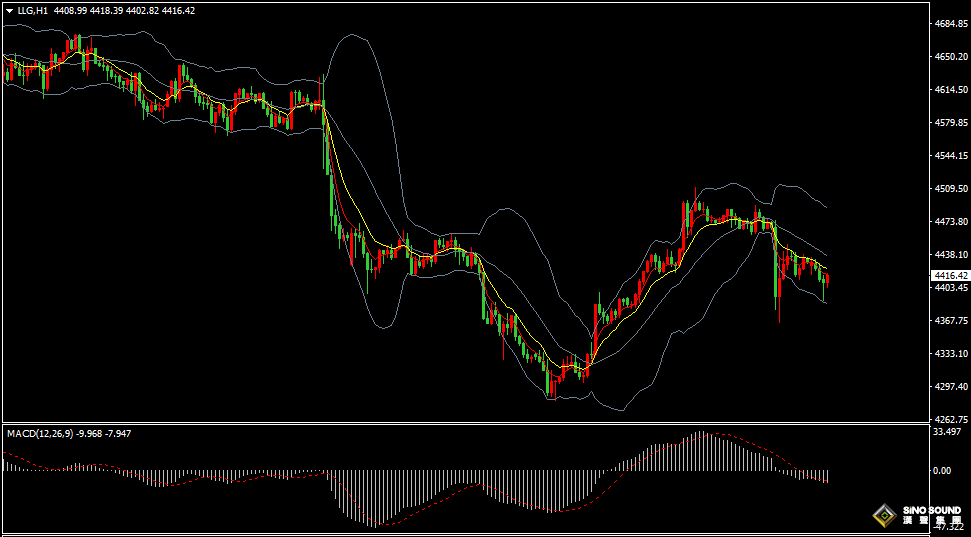
On the 1‑hour gold chart, all three BOLLinger Bands slope downwards, with prices consolidating between the middle and lower bands. Short‑term EMA5 and EMA10 maintain a bearish alignment. MACD negative histogram is expanding and RSI flattens near 40. Intraday trading outlook: gold is expected to range‑trade within $4380‑$4440. A breakout above this range opens upside targets at $4450‑$4465 or near $4480. Downside targets sit at $4370‑$4360 and near $4350.
Key economic data & events for today:
TBD China August Foreign Exchange Reserves
14:00 Germany July Seasonally‑Adjusted Industrial Output MoM
14:00 UK August Halifax Seasonally‑Adjusted House Price Index MoM
15:00 Switzerland August Seasonally‑Adjusted Unemployment Rate
16:30 Eurozone September Sentix Investor Confidence Index
17:00 Eurozone Q2 GDP Annualised Final
17:00 Eurozone Q2 Seasonally‑Adjusted Employment Change Quarterly Final
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.