

Spot gold first drifted lower to $4565.88 per ounce overnight, then rebounded back above the $4600 mark and closed at $4601.66 per ounce, up 0.16%. Spot silver staged a strong recovery to an intraday high of $69.657 per ounce and finished at $69.201 per ounce, gaining 1.69%.
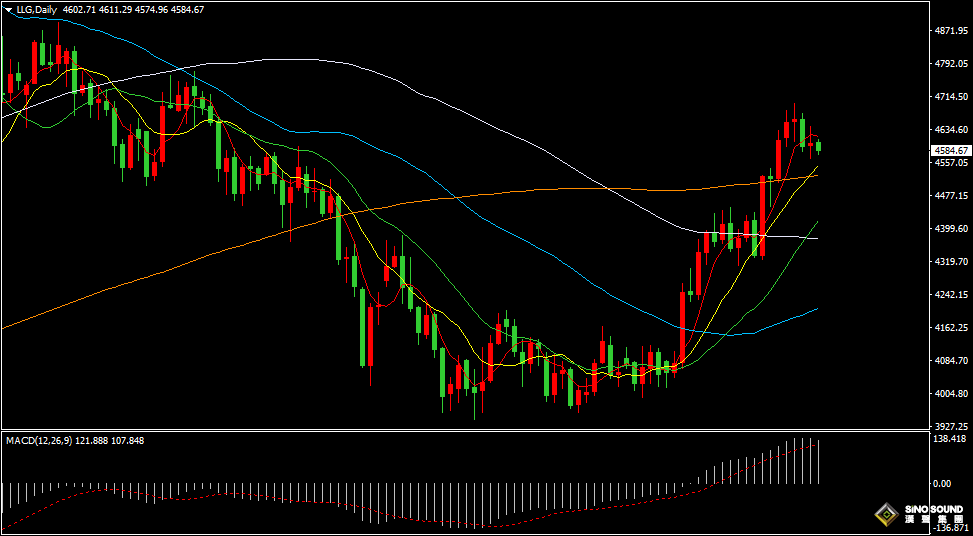
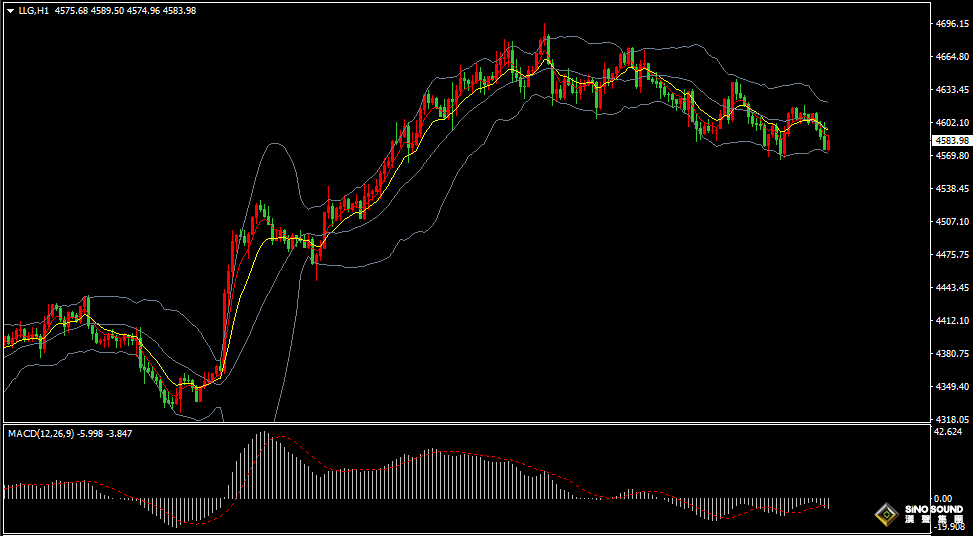
Spot gold opened at $4602.71 per ounce during Friday’s ASIan session, hitting an intraday high of $4611.29 per ounce before falling back to $4574.96 per ounce. At press time, gold hovers near $4584, down 0.38%.
The U.S. Dollar Index retreated from daily highs overnight, ranging between 99.26 and 99.07 and closing at 99.13, down 0.01%. The 2‑year U.S. Treasury yield rose 2 bASIs points to 4.234%; the 10‑year Treasury yield climbed 3.1 bASIs points to 4.68%.
Crude oil benchmarks advanced overnight. WTI crude closed at $83.60 per barrel (+1.90%); Brent crude settled at $88.62 per barrel (+2.15%). US Natural Gas CFD ended at $2.904 per MMBtu, down 0.103%.

Major US equity indices closed higher. Dow Jones rose 104.67 points (+0.20%) to 53568.55; S&P 500 gained 55.10 points (+0.72%) to 7730.80; Nasdaq Composite jumped 411.16 points (+1.57%) to 26541.35.
Most major European stock indices finished lower. DAX30 +0.19% at 26366.45; FTSE100 ‑0.75% at 10796.27; CAC40 ‑1.68% at 8319.87; Euro Stoxx 50 ‑0.70% at 6425.75; IBEX35 ‑0.93% at 19880.60; FTSE MIB ‑1.13% at 52286.00.
At the Shanghai Gold Exchange, Gold T+D closed ‑0.3% at 993.7 yuan/gram; Silver T+D rose 0.84% to 16856.0 yuan/kg. In early Friday trade, Gold T+D fell 0.6% to 990.72 yuan/gram; Silver T+D edged up 0.62% to 16820.0 yuan/kg.
Global largest gold ETF SPDR Gold Trust added 1.141 tonnes, holding 1046.636 tonnes. The world’s top silver ETF iShares Silver Trust reduced holdings by 16.87 tonnes to 15345.86 tonnes.
China’s central‑parity foreign‑exchange rates: USD‑CNY 6.7811 (-29 pips); EUR‑CNY 7.8683 (-56 pips); HKD‑CNY 0.86498 (-3.7 pips); GBP‑CNY 9.1819 (-40 pips); AUD‑CNY 4.8550 (+62 pips); CAD‑CNY 4.8716 (+64 pips); 100JPY‑CNY 4.2428 (-63 pips); CNY‑RUB 12.7890 (+2396 pips); NZD‑CNY 4.0208 (+31 pips); CNY‑MYR 0.5964 (+6.8 pips); CHF‑CNY 8.4056 (+69 pips); SGD‑CNY 5.3142 (-2 pips).
Latest US data: Initial Jobless Claims for the week ending Aug 22 printed 203,000 vs forecast 208,000; prior revised from 206,000 to 207,000. Canada Q2 Current Account posted a surplus of CAD 8.84 billion versus expectation of CAD‑2.0 billion; prior revised from CAD‑7.18 billion to CAD‑8.31 billion.
Falling US jobless claims signal low lay‑offs despite softer hiring momentum. The US unemployment rate ticked down to 4.1%, near historical lows. A resilient labour market may allow the Fed to remain focused on inflation control. Separately, the US July goods‑trade deficit widened to its largest since early last year, driven by surging capital‑goods imports.
Canada’s Q2 current‑account surplus far exceeded forecasts, swinging from deficit, powered by commodity exports. Crude‑oil and bitumen exports hit record highs, offering trade buffers amid escalating tariff disputes with the US.
ECB minutes showed policymakers saw strong grounds to hold rates steady at the latest meeting. Further rate hikes may still be needed without meaningful inflation improvement. Euro‑area inflation hovers around 3%, well above the 2% target, while economic growth beats expectations.
Fed’s Schmid said current rates are not restrictive for the US economy with inflation peRSIstently above 2%, and short‑term rates may remain accommodative. Fed’s Goolsbee noted price pressures from tariffs and wars create policy challenges; political interference in central banks tends to fuel inflation, and political pressure on the Fed is a source of concern.
Ahead of the November 3 US mid‑term elections, corporate political spending hit USD 646 million over 18 months, 40% higher than the full 2024 presidential cycle. Heavy corporate financing accompanies fierce partisan competition for congressional control. Forecasts assign Democrats a 57.2% chance of winning Senate control and an 84% chance for the House.
UK Labour MPs warned Prime Minister Burnham that planned UK trade sanctions over 1,200 new Israeli settlement homes in the West Bank could trigger US retaliation. Spain previously banned settlement‑origin imports; Trump threatened comprehensive trade sanctions against Spain.
Russian Foreign Ministry spokesperson Zakharova said French and British supplies of sensitive missile technology to Ukraine amount to “playing with fire”, bringing unpredictable consequences for Paris and London. Russia warned it may strike British military targets inside and outside Ukraine.
Qatar’s foreign ministry reported Qatar and Iran discussed agreements for joint projects to clear mines in the Strait of Hormuz, including a phased framework for a temporary shipping corridor through the strait.
Iran’s Secretary of the Supreme National Security Council Rezaei stated Iran has prepared a list of conditions for the United States. Vessels may temporarily use designated lanes through the strait for now, yet future passage will hinge on a memorandum of understanding with Washington.
On the daily chart, gold traded with wide swings between $4642.63 and $4565.88, with repeated battles around the $4600 mark. Daily indicators: MACD positive momentum keeps shrinking; RSI retreats near 65.
On the 1‑hour chart, swing action shows gradually lower highs and lows. Gold consolidates between the middle and lower BOLLinger Bands. Short‑term EMA5 and EMA10 form bearish alignment. MACD shows limited negative momentum, and RSI drifts near 44. Intraday range to watch: $4560‑$4625. Upside breakout targets $4635‑4645 or near $4655. Downside breakdown targets $4555‑4545 or near $4525.
Key economic releases & events for today:
14:45 France Aug CPI MoM Flash
14:45 France Q2 GDP YoY Final
15:00 Switzerland Aug KOF Leading Indicator
15:55 Germany Aug Seasonally‑Adjusted Unemployment Change
15:55 Germany Aug Seasonally‑Adjusted Unemployment Rate
17:00 Eurozone Aug Industrial Sentiment
17:00 Eurozone Aug Economic Sentiment
20:30 Canada Jun GDP MoM
21:45 US Aug Chicago PMI
22:00 US Aug UniveRSIty of Michigan Consumer Sentiment Final
22:00 US Aug 1‑Year Inflation Expectations Final
22:00 US 2026 Non‑Farm Payrolls Benchmark Revision Preliminary
22:00 Fed Chair Warsh Speech
01:00(next day) US Oil Rig Count week ending Aug 28
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.