

After the release of US PCE data last night, the US Dollar Index advanced, spot gold broke below the $4600 threshold and dipped to a low of $4583.16 per ounce, before settling at $4594.42 per ounce, down 1.38%. Spot silver closed at $68.051 per ounce, a drop of 0.79%.
Spot gold opened at $4596.32 per ounce during Thursday’s ASIan session and hit an intraday low of $4596.22 per ounce. It rebounded through morning trade to a high of $4642.63 per ounce. At press time, gold is hovering near $4633, up roughly 0.84% on the day.
Driven by US economic figures, the US Dollar Index trended higher overnight, peaking at 99.23 and finishing at 99.14 for a 0.23% gain. The 2‑year US Treasury yield rose 3.9 bASIs points to 4.214%, and the 10‑year US Treasury yield climbed 2.3 bASIs points to 4.649%.
Crude oil prices reversed higher at the start of US trading hours before giving back part of their advance. WTI crude closed at $82.04 per barrel (+1.25%), Brent crude settled at $86.76 per barrel (+1.13%). US Natural Gas CFD finished at $2.907 per million British thermal units, up 2.179%.

US major equity indices closed lower overnight. The Dow Jones fell 112.81 points or 0.21% to 53464.59; the S&P 500 slipped 1.46 points or 0.02% to 7675.82; the NASDAQ lost 21.10 points or 0.08% to 26130.20.
Most major European stock benchmarks ended higher. Germany’s DAX 30 +0.04% at 26296.59; UK FTSE 100 ‑0.07% at 10879.04; France CAC 40 +0.27% at 8462.39; Euro Stoxx 50 +0.24% at 6471.05; Spain IBEX 35 +0.04% at 20063.87; Italy FTSE MIB +0.33% at 52896.00.
On the Shanghai Gold Exchange, Gold T+D closed‑0.67% at 994.87 CNY/g, Silver T+D closed‑1.03% at 16540.0 CNY/kg. In early Thursday trade, Gold T+D fell 0.76% to 993.95 CNY/g, Silver T+D dropped 0.62% to 16609.0 CNY/kg.
SPDR Gold Trust, the world’s largest gold ETF, saw its holdings decrease by 2.853 tonnes to 1045.495 tonnes. iShares Silver Trust holdings remained unchanged at 15362.73 tonnes.
Today’s FX mid‑point rates: USD‑CNY 6.7840 (+11 pips, CNY weaker); EUR‑CNY 7.8739 (‑68 pips); HKD‑CNY 0.86535 (+1.2 pips); GBP‑CNY 9.1859 (‑268 pips); AUD‑CNY 4.8488 (+137 pips); CAD‑CNY 4.8652 (‑92 pips); 100JPY‑CNY 4.2491 (+41 pips); CNY‑RUB 12.5494 (+914 pips); NZD‑CNY 4.0177 (‑146 pips); CNY‑MYR 0.59572 (‑17.4 pips); CHF‑CNY 8.3987 (‑265 pips); SGD‑CNY 5.3144 (‑56 pips).
Latest US figures: Q2 Real GDP Annualized Revised 1.5%, matching preliminary reading and market consensus. July Durable Goods Orders MoM 1.1% (forecast 0.50%, prior 0.50%). July Personal Spending MoM 0.2% (forecast 0.1%, prior 0.30%).
July Core PCE Price Index MoM 0.2% (forecast 0.20%, prior 0.10%). July PCE Price Index YoY 3.7%, unchanged month‑over‑month versus an expected dip to 3.6%. July Core PCE Price Index YoY 3.3%, in line with expectations and flat from June.
Fed‑watched inflation metrics showed expanding monthly price pressures, with annual inflation staying elevated for a 65th straight month, well above the 2% objective. Month‑on‑month PCE rose 0.2%, topping economist estimates, while core‑PCE year‑on‑year held steady. The softer core‑CPI print is positive news for the Fed. Significant uncertainty remains over how Fed Chair Warsh will address the inherited inflation challenge.
US Q2 GDP expanded at an annualized 1.5%, with underlying details pointing to stronger‑than‑initially‑reported consumer spending and business investment. Market pricing has nudged higher the probability of a September Fed rate‑hike to roughly 42%, up from around 36% before the data release.
US President Trump has sought greater influence over monetary policy by replacing Fed officials to install his appointees. His efforts have met legal and Senate political pushback. Potential Fed personnel shifts remain on the table regarding Cook, Powell, Jefferson and the candidate for Atlanta Fed President.
Middle‑East updates: Iran stated it and Oman reached consensus over territorial demarcation and revenue allocation within the Strait of Hormuz, while blaming US obstruction for stalling implementation.
Trump said he has no timeline and is in no rush for Iran to return to negotiations. He assessed Iran’s supreme leader may have sustained serious injury rather than death. He noted the Strait of Hormuz remains operational with 10 million barrels of oil shipped yesterday, and reaffirmed US‑enforced blockade measures for the strait stay in effect.
Russia is preparing to escalate military strikes against Ukraine after deeming peace‑talks deadlocked, considering intensified attacks on infrastructure targets in Kyiv and other cities. Moscow views Ukrainian airstrikes enabled by NATO‑supplied weapons and intelligence as de‑facto NATO aggression.
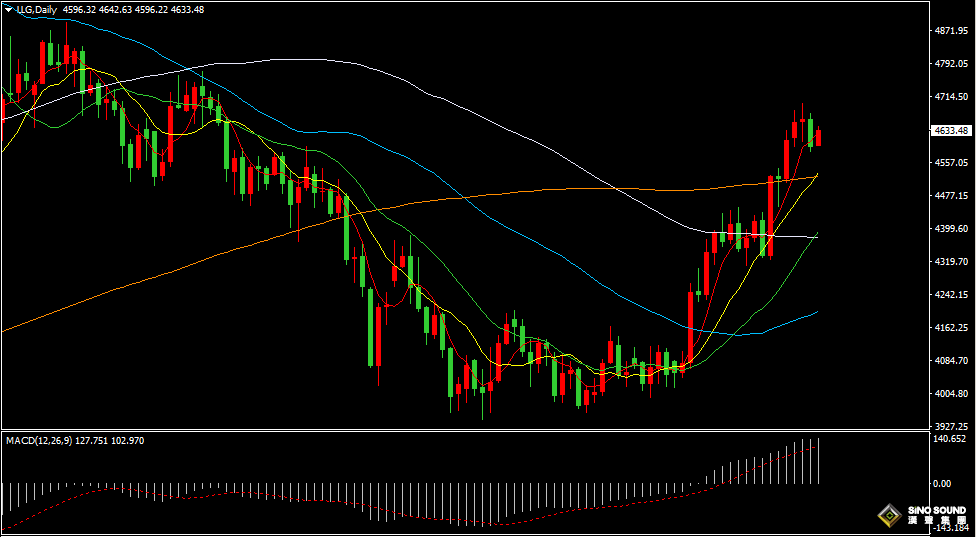
On the daily chart, gold fell and erased two‑day gains yesterday, then rebounded back above the 5‑day moving average in early Thursday trade. Near‑term price action is expected to stay range‑bound around recent highs. Daily indicators: MACD positive histogram peRSIsts; RSI has pulled back near 68.
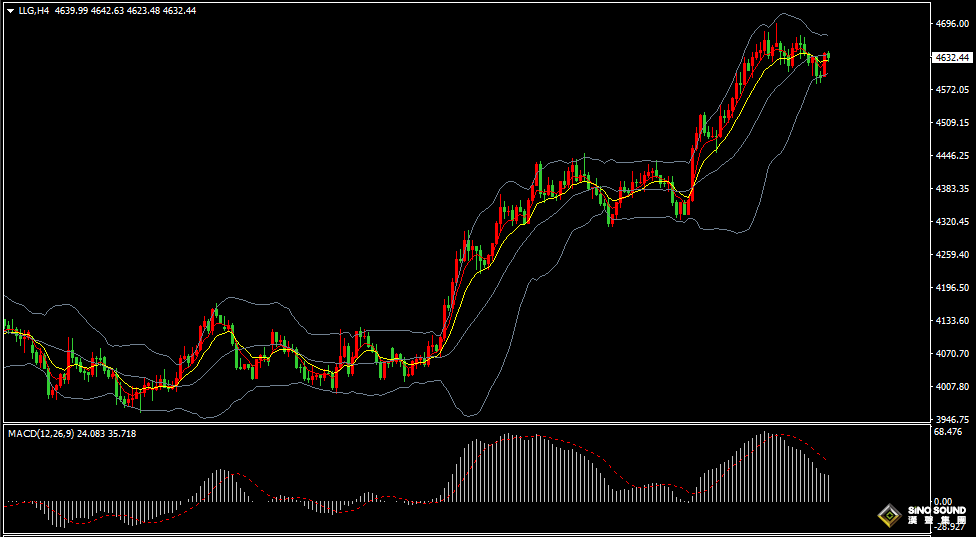
On the 4‑hour chart, BOLLinger Bands are contracting, price oscillates around the mid‑band. Short‑term EMA5 and EMA10 have flattened and intertwined. MACD positive momentum is fading, RSI hovers near 57. Intraday bias: expect consolidation within $4600‑4670. A breakout higher targets $4680‑4695 and then near $4705. On a downside break, targets lie at $4595‑4585 and then near $4580.
Key economic releases & events for today:
TBD Jackson Hole Global Central‑Bank Symposium
14:00 Germany September GfK Consumer Confidence
15:00 China Ministry of Commerce regular press briefing
19:30 ECB Monetary Policy Meeting Minutes
20:30 Canada Q2 Current Account
20:30 US Initial Jobless Claims week ending Aug 22
22:30 US EIA Natural Gas Storage week ending Aug 21
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.