

Spot gold bounced off the low of USD 4605.52 per ounce during last night’s US session, yet retreated again near USD 4670 and closed at USD 4658.58 per ounce, up 0.15%. Spot silver finished at USD 68.596 per ounce, down 0.43%.
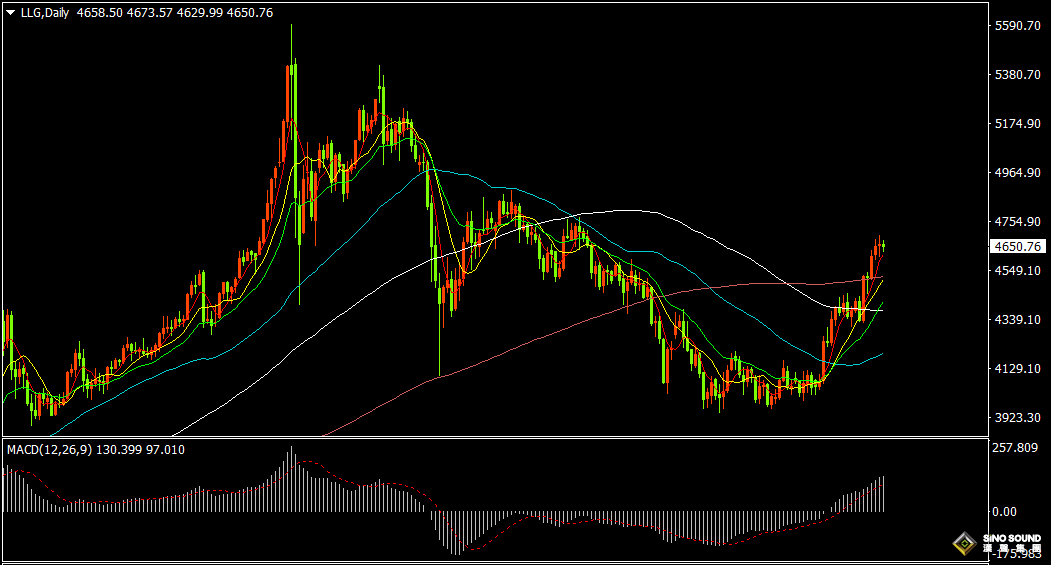
Spot gold opened at USD 4658.50 per ounce in Wednesday’s ASIan session. It dipped to an intraday low of USD 4629.99 early on, then rebounded to USD 4673.57. At press‑time, gold was trading around USD 4650.
The US Dollar Index drifted lower overnight, falling back below 99 and closing at 98.91, down 0.08%. The 2‑year US Treasury yield dropped 6.1 bASIs points to 4.175%; the 10‑year yield fell 7.1 bASIs points to 4.626%.
Crude oil extended intraday losses. WTI crude closed at USD 81.02 per barrel (-4.59%); Brent crude settled at USD 85.78 per barrel (-5.07%). US natural‑gas CFD closed at USD 2.845 per million British thermal units, up 1.535%.

US major equity indices closed higher. The Dow Jones added 160.07 points (+0.30%) to 53577.23. The S&P 500 rose 24.36 points (+0.32%) to 7677.22. The Nasdaq Composite gained 171.11 points (+0.66%) to 26151.30.
European equities finished mixed. Germany’s DAX 30 +0.60% to 26274.75; UK FTSE 100 +0.31% to 10887.92; France CAC 40 -0.16% to 8439.20; Euro Stoxx 50 +0.17% to 6458.75; Spain IBEX 35 -0.16% to 20065.59; Italy FTSE MIB +0.40% to 52752.00.
At the Shanghai Gold Exchange, Gold T+D closed -0.11% at RMB 1003.39 per gram; Silver T+D closed +0.72% at RMB 16749.0 per kilogram. In Wednesday’s early trade, Gold T+D fell 0.44% to RMB 1000.04 per gram; Silver T+D dropped 0.31% to RMB 16579.0 per kilogram.
The world’s largest gold ETF, SPDR Gold Trust, saw its holdings decrease by 1.141 tonnes to 1048.348 tonnes. The largest silver ETF, iShares Silver Trust, reduced holdings by 36.53 tonnes to 15362.73 tonnes.
Today’s central parity for RMB exchange rates: USD/CNY 6.7829 (-23 pips, RMB appreciation); EUR/CNY 7.8807 (+16 pips); HKD/CNY 0.86523 (-6.4 pips); GBP/CNY 9.2127 (+21 pips); AUD/CNY 4.8351 (+49 pips); CAD/CNY 4.8744 (-13 pips); 100JPY/CNY 4.2450 (-68 pips); CNY/RUB 12.4580 (+178 pips); NZD/CNY 4.0323 (+62 pips); CNY/MYR 0.59746 (-0.5 pips); CHF/CNY 8.4252 (+3 pips); SGD/CNY 5.3200 (+15 pips).
Latest US data: US ADP Employment Change (week ending Aug 8) 11,750 versus prior 9,500. August Conference‑Board Consumer Confidence 89.4 (exp 90.2, revised prior 90.2). August Richmond Fed Manufacturing Index 4 versus prior 5.
US June S&P/CS 20‑City Home Price Index YoY 2.1% (exp 1.7%, prior 1.63%). June FHFA House Price Index MoM 0% versus prior 0.30%. July New Home Sales Annualised 607,000 (exp 620,000, prior 628,000).
US consumer confidence in August fell to its lowest level since early this year amid worsening views over business conditions and labour‑market prospects. July new‑home sales dropped to a six‑month low, showing high mortgage rates are weighing on housing demand even as builders cut prices and offer incentives.
Fed’s Collins stated sustained evidence of falling inflation is needed to keep rates unchanged. Without peRSIstent cooling inflation, raising rates “as soon as appropriate” would be warranted. Inflation remains too high and the Fed must uphold price‑stability mandates. Given limited additional tariffs and progress on reopening the Strait of Hormuz, falling inflation remains the most plausible outcome.
Global central‑bank attention turns to Jackson Hole, Wyoming this Friday. Markets widely expect Warsh to deliver dovish signals and possibly propose an informal “new policy compact” for better coordination between authorities on bond‑market management.
Last week the Treasury ramped up bond‑buyback operations. Bessent said current yields have decoupled from fundamentals. Should the Fed keep balance‑sheet reduction in place, long‑term yields would face further upward pressure, exposing material divergence in market‑expectation management.
Reports say the US State Department prepares to redeploy diplomats to Middle‑East embassies evacuated during the Iran conflict, signalling the Trump administration believes hostilities are drawing to an end. Target missions include Israel, Lebanon, Saudi Arabia, Qatar, Jordan, Oman, Iraq and Kuwait.
President Trump said the US Navy has cleared or detonated all mines in international waters of the Strait of Hormuz. Iran has been warned that any vessel laying new mines will be swiftly and systematically destroyed. Iran dismissed US mine‑clearing claims as “propaganda lies” and threatened to target US mine‑countermeasure vessels operating in the strait.
On the daily chart, gold printed a doji candle reflecting fierce bull‑bear contention. Short‑term price action is expected to stay range‑bound between 4600‑4700. Daily indicators show MACD positive histogram stays elevated while RSI hovers near the 70 overbought threshold.
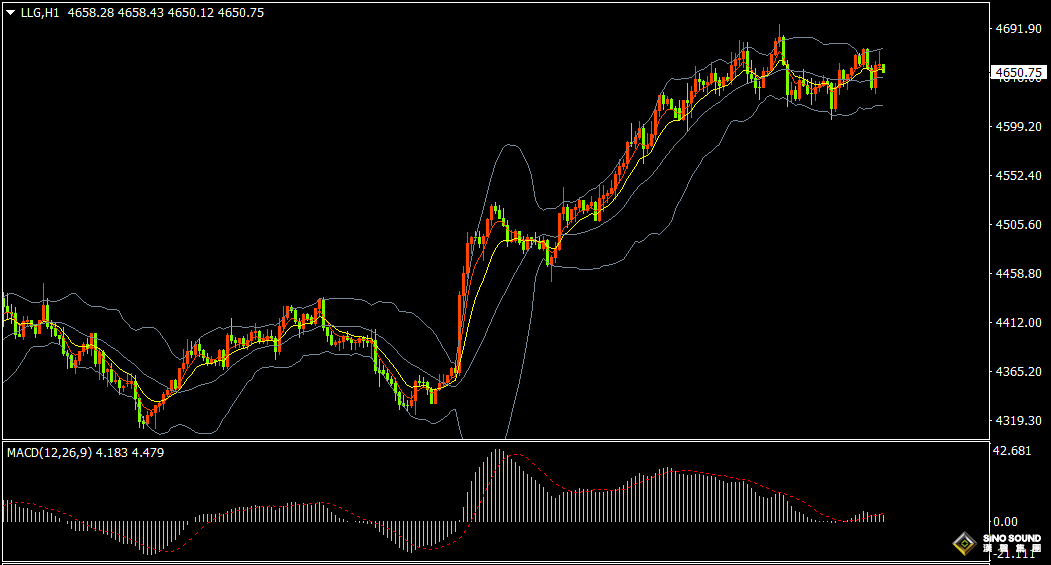
On the 1‑hour chart, BOLLinger Bands flatten out and gold oscillates around the mid‑band. Short‑term EMA5 and EMA10 are flattened and intertwined. MACD positive histogram remains thin, and RSI drifts near 50. Intraday bias: watch consolidation inside 4620‑4680. A breakout higher targets 4690‑4700 and then 4710; downside break targets 4610‑4600 and then 4590.
Key economic data & events for today:
16:00 Switzerland August ZEW Investor Confidence Index
18:00 UK August CBI Retail Sales Balance
20:30 US July Core PCE Price Index YoY
20:30 US July Personal Spending MoM
20:30 US Q2 Real GDP Annualised QoQ Revised
20:30 US July Core PCE Price Index MoM
20:30 US July Durable‑Goods Orders MoM
22:30 US EIA Crude Oil Inventories (week ending Aug 21)
22:30 US EIA Cushing Crude Oil Inventories (week ending Aug 21)
22:30 US EIA Strategic Petroleum Reserve Inventories (week ending Aug 21)
23:45 Fed’s Barkin participates in panel discussion
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.