

Spot gold opened at USD 4653.14 per ounce during Tuesday’s ASIan session. It spiked briefly to USD 4696.34 per ounce in early trading, then drifted lower to an intraday low of USD 4618.10 per ounce. At press‑time, gold traded near USD 4632, down roughly 0.42% on the day.
The US Dollar Index trended higher intraday, reclaiming the 99 level and touching 99.12; it last stood at 99.06, up 0.07%. The 2‑year US Treasury yield rose 0.7 bASIs points to 4.243%, while the 10‑year US Treasury yield gained 1.3 bASIs points to 4.71%.
Global crude oil prices advanced then retreated. WTI crude traded at USD 84.63 per barrel (-0.34%); Brent crude stood at USD 90.13 per barrel (-0.25%). US natural gas CFD was quoted at USD 2.801 per million British thermal units, down 0.036%.
In Chinese equities, the three major A‑share indices rallied in the afternoon and briefly turned positive across the board. Total market turnover reached only RMB 1,844.3 billion, a drop of RMB 176.9 billion from the previous session. The Shanghai Composite Index added 7.44 points (+0.19%) to 3889.44. The Shenzhen Component Index fell 48.42 points (-0.35%) to 13745.87. The ChiNext Index dropped 34.37 points (-1%) to 3397.52.

Hong Kong’s Hang Seng Index oscillated lower in the afternoon and closed slightly down. Total market turnover hit HKD 254.079 billion. The Hang Seng Index slipped 6.23 points (-0.02%) to 25511.1. The Hang Seng Tech Index lost 5.5 points (-0.12%) to 4588.54. The Hang Seng China Enterprises Index fell 25.99 points (-0.31%) to 8445.37. The Hang Seng China Red‑Chip Index declined 18.56 points (-0.44%) to 4229.07.
European equity markets opened in the afternoon: Germany’s DAX 30 +0.36%, UK FTSE 100 +0.21%, France CAC 40 +0.57%, Spain IBEX 35 +0.44%, Italy FTSE MIB +0.53%, Euro Stoxx 50 +0.55%.
At the Shanghai Gold Exchange, Gold T+D closed +0.13% at RMB 1001.14 per gram; Silver T+D closed -1.36% at RMB 16550.0 per kilogram.
Domestic retail gold jewellery prices climbed nearly RMB 20 per gram from the prior day, breaking above RMB 1400 per gram. Major brands including Chow Tai Fook, Tse Sui Luen and Chow Tai Seng quoted RMB 1410 per gram for pure‑gold ornaments.
Latest economic data: Germany’s final non‑seasonally adjusted Q2 GDP YoY printed at 1%, versus expectation 0.9% and prior reading 0.90%. Germany August Ifo Business Climate Index came in at 88.8, beating consensus 87.2 and prior 86.6.
Germany’s Federal Statistical Office stated the economy extended its growth momentum since early this year, with exports acting as the main growth driver. External demand remained the strongest contributor; goods‑and‑services exports rose 2.0% quarter‑on‑quarter while imports gained 1.5% QoQ. Nevertheless, consumption growth stayed muted: both household and government consumption edged up merely 0.1% QoQ, showing domestic demand still played a limited role in recovery. German business sentiment improved markedly in August, signalling strengthening recovery after months of gradual stabilisation.
As President Trump enters a critical phase of his second term, Treasury Secretary Bessent faces intense scrutiny from financial markets. Upon his nomination, Wall Street widely viewed him as an anchor capable of reining in the president’s aggressive fiscal expansion. Yet actual performance over the past two years has fallen short of those expectations, and market doubts over his policy credibility keep mounting.
Following Trump’s military campaign against Iran, diesel and fertiliser costs have surged. Research by the American Farm Bureau estimates that without government aid, US farmers planting nine major crops including corn would suffer combined losses of USD 31 billion this year. Heading into key mid‑term elections, such economic pressure is shaping voter sentiment across agricultural states.
The US keeps ramping up economic pressure on Iran; fuel shortages have emerged as a new strain on Iran’s economy. Though a major global oil producer, long‑running sanctions have left Iran’s refineries outdated and unable to produce sufficient gasoline. Long queues are reported at petrol stations nationwide, with a daily supply gap of roughly 14‑15 million litres of gasoline.
The US government announced a reward of up to USD 10 million for information on 14 senior Iranian military figures including Vahidi, Commander‑in‑Chief of the Islamic Revolutionary Guard Corps, Chief of General Staff Abdolrahim, and IRGC Drone Command Commander Aghajani.
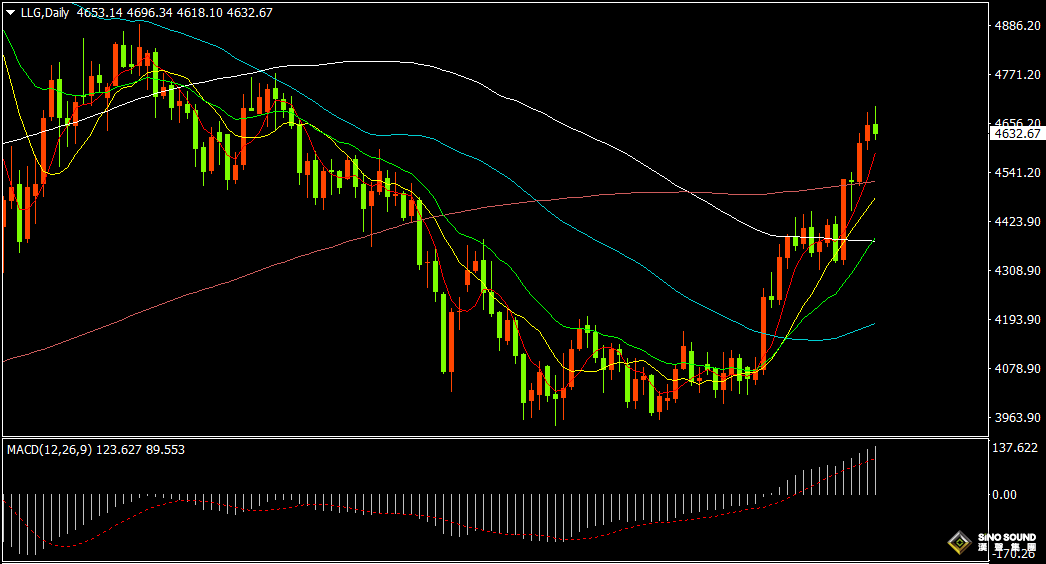
Markets now focus on two key events: tomorrow evening’s US PCE inflation release and Fed officials’ speeches at the Jackson Hole Symposium on Friday. Analysts note markets have not fully ruled out a September Fed policy adjustment. A hotter‑than‑expected inflation print may force a repricing of rate‑cut timelines and push gold lower toward the 200‑day moving average near USD 4520. By contrast, softer inflation alongside policy signals from Jackson Hole could send gold targeting USD 5000.
On the daily chart, gold faced resistance near the 4700 level and pulled back. It found near‑term support around USD 4618, yet the USD 4600 level will remain a key test during the US session. A break below 4600 would open a retest of the 5‑day moving average at 4586. On daily indicators, MACD positive histogram remains elevated, while RSI hovers near the 70 overbought threshold.
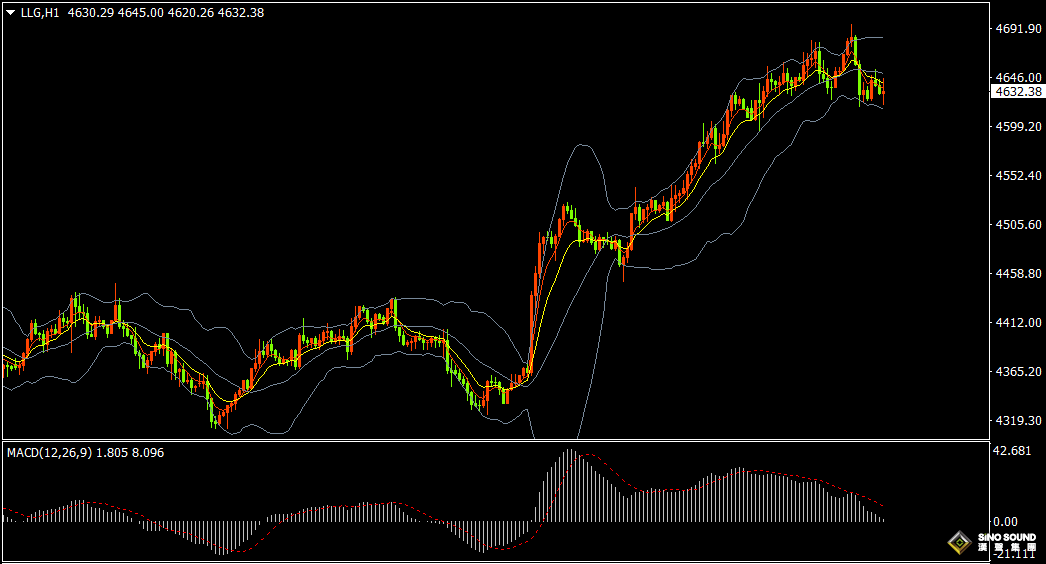
On the 1‑hour chart, gold consolidates between the middle and lower BOLLinger Bands. Short‑term EMA5 and EMA10 have formed a bearish alignment. MACD positive histogram has shrunk toward the zero‑line, and RSI flattens near 47. For tonight’s short‑term trading, we retain our morning outlook: watch price action within the 4600‑4680 range. A breakout higher targets 4690‑4700 and then 4720; a downside break looks toward 4590‑4580 and then 4565.
Key economic data & events for tonight:
20:00 Fed’s Barkin speaks
20:15 US ADP Employment Change (week ending Aug 8)
21:00 US June FHFA House Price Index MoM
21:00 US June S&P/CS 20‑City Composite Home Price Index YoY
22:00 US July New Home Sales (annualised)
22:00 US August Conference Board Consumer Confidence Index
22:00 US August Richmond Fed Manufacturing Index
04:30 (next day) US API Crude Oil Inventories (week ending Aug 21)
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.