

In Wednesday's ASIan session, spot gold opened at $4183.32 per ounce, with an intraday low of $4165.61 per ounce. Gold edged higher during the session and briefly broke the $4200 threshold, hitting an intraday peak of $4202.07 per ounce before pulling back for consolidation. At press time, gold was trading near $4196, up roughly 0.33% on the day.
The US Dollar Index spiked to 101.47 in the short term then retreated, now quoted at 101.24, down 0.14%. The 2-year US Treasury yield fell 1.2 bASIs points to 4.867%; the 10-year US Treasury yield dropped 2.4 bASIs points to 5.216%; the 30-year US Treasury yield declined 1.8 bASIs points to 5.55%.
International oil prices traded sideways for most of the day. WTI crude is quoted at $89.50 per barrel, up 0.65%; Brent crude stands at $96.49 per barrel, up 0.90%; US natural gas CFD is at $3.027 per MMBtu, up 0.498%.
In equities, China’s three major A-share indices traded in a narrow range throughout the day. Total turnover on the Shanghai and Shenzhen markets reached 1.44 trillion yuan, an increase of 28.8 billion yuan from the previous session. At the close, the Shanghai Composite Index rose 11.74 points, or 0.31%, to 3842.19. The Shenzhen Component Index fell 14.33 points, or 0.11%, to 12887.62. The ChiNext Index dropped 7.29 points, or 0.23%, to 3135.28.

Hong Kong’s Hang Seng Index opened lower then moved higher, with total market turnover of HK$187.158 billion. At the close, the Hang Seng Index gained 89.7 points, or 0.37%, to 24613.27. The Hang Seng Tech Index rose 4.27 points, or 0.1%, to 4253.89. The Hang Seng China Enterprises Index climbed 41.27 points, or 0.5%, to 8220.08. The Hang Seng China Red Chip Index added 12.85 points, or 0.32%, to 4070.11.
European stock indices opened in the afternoon. Germany’s DAX 30 opened 0.42% higher, the UK FTSE 100 rose 0.30%, France’s CAC 40 dipped 0.02%, Spain’s IBEX 35 gained 0.27%, Italy’s FTSE MIB rose 0.10%, and the Euro Stoxx 50 opened 0.19% higher.
In the afternoon, Shanghai Gold Exchange's Au(T+D) closed up 1.37% at 906.8 yuan per gram; Ag(T+D) closed up 0.67% at 14890.0 yuan per kilogram.
Latest domestic data shows China’s official September manufacturing PMI stood at 50.1, matching expectations and up from the previous reading of 49.8. Huo Lihui, chief statistician at the National Bureau of Statistics, said three key industrial sectors expanded rapidly in September. The PMIs for equipment manufacturing, high-tech manufacturing and consumer goods industries came in at 51.0%, 52.5% and 50.7% respectively, all above the threshold, indicating generally active production and operation at related enterprises.
Australia’s August unadjusted CPI rose 4% year-on-year, compared with expectations of 4.1% and the prior reading of 3.50%. Australia’s inflation remained elevated, with higher fuel prices adding to price pressures. PeRSIstent inflation forced the Reserve Bank of Australia to deliver its fourth rate hike of the year on Tuesday. Markets price the probability of another RBA rate hike at the November meeting at nearly 40%.
UK Q2 current account deficit came in at £19.932 billion, versus expectations of -£24.7 billion. The prior reading was revised from -£22.134 billion to -£21.12 billion. The final reading of UK Q2 GDP annual growth was 1.4%, above expectations of 1.2% and the prior figure of 1.20%.
France’s preliminary September CPI month-on-month fell 0.3%, compared with forecasts of -0.6% and the prior reading of 0.70%. France’s August PPI year-on-year was 4.8%, with the prior figure revised from 3.40% to 3.5%. Germany’s September seasonally adjusted unemployment rate was 6.4%, matching expectations and the prior value of 6.40%. Germany’s unadjusted September unemployed population stood at 2.994 million, down from 3.061 million previously. Seasonally adjusted unemployment change was +12,000, versus expectations of +1,000 and the prior reading of +4,000. Switzerland’s September ZEW investor confidence index was 2.6, down from 12.1.
UK economic growth in Q2 was stronger than previously estimated. Revised data showed the economy remained resilient before the sharp rise in energy prices and borrowing costs. Nevertheless, the UK economic outlook has deteriorated in recent weeks, and pressures on businesses and households are expected to intensify in the second half of the year.
France’s inflation climbed to its highest level in more than two years. As the euro zone’s second-largest economy, it adds pressure on the European Central Bank to keep raising rates. Still, shocks from the Middle East conflict have not triggered obvious second-round inflation effects.
Minutes from the Riksbank’s rate meeting showed that risks of inflation staying above the 2% target have increased. Therefore, there are solid grounds to lift the policy rate to 2% in the near term and upgrade projections for future policy rates.
The Swiss National Bank stated that safe-haven capital kept flowing into Switzerland during the Iran war, strengthening the Swiss franc and forcing the SNB to intervene. The central bank continued selling francs in Q2 to counter franc appreciation.
Data from the Bank of Korea showed it sold a net $9.612 billion via market intervention in Q2 this year to curb the depreciation of the Korean won. This marked the seventh consecutive quarter of USD selling intervention by the central bank. The Bank of Korea sold a net $13.628 billion in Q1.
Analysts say global government bond markets may remain under pressure in the short run as energy prices and economic data are unlikely to change. Under their baseline scenario, falling energy prices in 2027 will pull inflation expectations lower. This should support lower yields, especially for short-dated bonds. However, they see limited room for declines on the long end of the yield curve, and long-term yields may stay elevated.
Statistics show short positions in US Treasury futures keep rising, with open interest for 5-year and 10-year contracts hitting new highs. Crowded short positions lay the groundwork for a potential short squeeze. If US PCE or non-farm payroll data weakens, crowded shorts may cover positions en masse and send yields sharply lower. Sudden weak economic data or dovish remarks from Fed officials could trigger rapid covering of massive short positions and push yields down quickly in the short term.
Tonight, US ADP employment data will be released first, with market expectations for 70,000 new jobs. US August PCE figures will follow shortly after. Markets expect the core PCE annual rate at 3.4%, higher than July’s 3.3%. Monthly personal spending is forecast to rise 0.4%, and monthly personal income is projected to increase 0.45%.
Previously, Fed’s Williams unexpectedly delivered dovish remarks, pulling the probability of an October rate hike down to 50%. However, strong data tonight may rapidly lift market bets on a US rate increase.
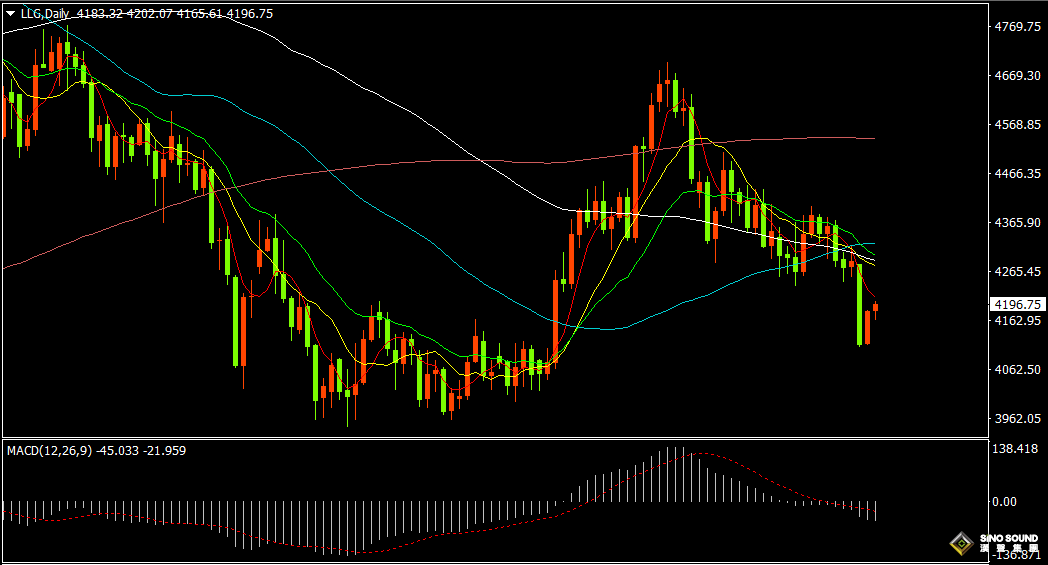
On the daily gold chart, upside room for the rebound is limited. As markets await key evening data, volatility is expected to pick up. Investors are advised to manage positions carefully and watch out for risks.
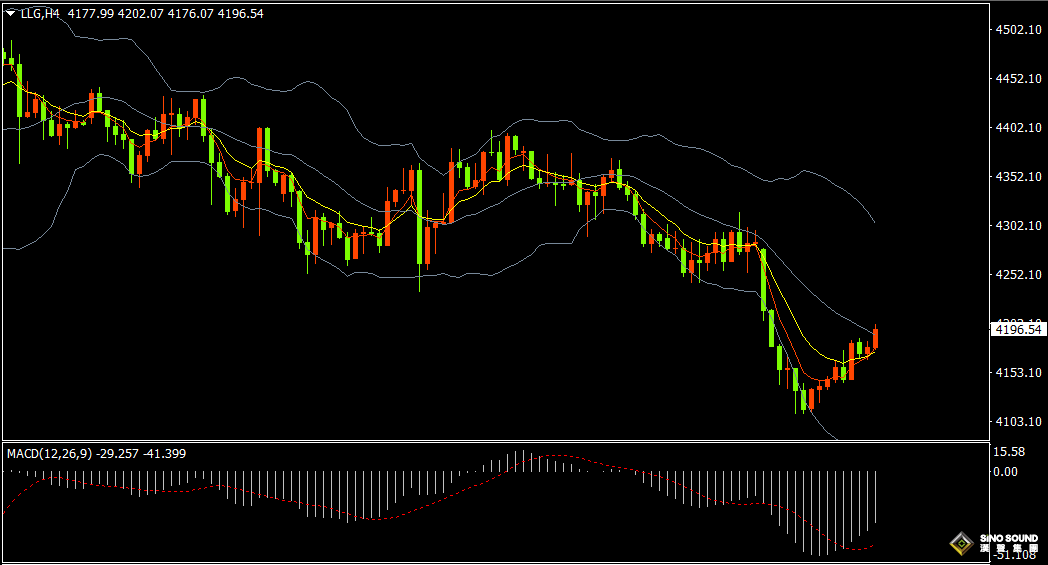
On the 4-hour gold chart, after rebounding toward the middle BOLLinger Band, bullish momentum appears weak. Short-term moving averages EMA5 and EMA10 are turning upward and converging. Negative MACD histogram continues to shrink, while RSI climbs to near the 46 level. For short-term trading tonight, key data will amplify gold volatility. The market is expected to trade within the 4100-4250 range. A breakout to the upside targets 4270-4300 or near 4320; downside targets are 4075-4050 or near 4025.
Key economic data and events to watch tonight:
20:00 Germany Preliminary September CPI MoM
20:15 US September ADP Employment Change
20:30 US August Core PCE Price Index YoY
20:30 US August Personal Spending MoM
20:30 US Q2 Final Real GDP Annualized QoQ
20:30 US Q2 Final Real Personal Consumption Expenditures QoQ
20:30 US Q2 Final Core PCE Price Index Annualized QoQ
20:30 US August Core PCE Price Index MoM
21:45 US September Chicago PMI
22:30 US EIA Crude Oil Stocks change for the week ending Sep 25
22:30 US EIA Cushing Crude Oil Stocks change for the week ending Sep 25
22:30 US EIA Strategic Petroleum Reserve Stocks change for the week ending Sep 25
01:30 (next day) Fed’s Barkin speaks at an event
03:25 (next day) Fed Governor Cook delivers remarks
05:10 (next day) Fed’s Goolsbee speaks
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.