

Spot gold opened at $4403.87 per ounce in Thursday’s ASIan session, with a low of $4389.69 per ounce. Gold rose oscillatingly to a high of $4434.38 per ounce in early trading, then fell back in the afternoon and erased all intraday gains. As of press time, gold is consolidating near $4402.
The US Dollar Index has been falling recently. It hit a high of 98.82 and a low of 98.71 today, and is now quoted at 98.77, down 0.03%. The 2-year US Treasury yield dropped by 0.7 bASIs points to 4.427%; the 10-year US Treasury yield edged down 0.1 bASIs points to 4.843%; the 30-year US Treasury yield climbed 0.9 bASIs points to 5.301%.
US WTI and Brent crude oil retreated in early ASIan trading before reveRSIng higher. WTI crude is now at $96.69 per barrel with its loss narrowed to 0.01%; Brent crude stands at $101.67 per barrel, up 0.04%. US natural gas CFD is quoted at $2.919 per MMBtu, up 3.99%.
In today’s stock market, the Shanghai Composite Index traded within a narrow range. The three major A-share indices closed lower collectively, and market turnover shrank again. This marked the fourth consecutive trading day with turnover below 2 trillion yuan. The combined turnover of Shanghai and Shenzhen markets reached only 1.65 trillion yuan, a decrease of 208.5 billion yuan from the previous session. At the close, the Shanghai Composite Index fell 17.1 points, or 0.43%, to 3934.4; the Shenzhen Component Index dropped 105.65 points, or 0.77%, to 13617.67; the ChiNext Index declined 16.55 points, or 0.49%, to 3338.42.

Hong Kong’s Hang Seng Index broke below the 25,000 mark, and all major indices declined across the board. Total market turnover for the Hang Seng Index hit HK$198.86 billion. At the close, the Hang Seng Index fell 320.49 points, or 1.27%, to 24954.47; the Hang Seng Tech Index dropped 90.3 points, or 2.04%, to 4330.49; the Hang Seng China Enterprises Index slipped 94.27 points, or 1.13%, to 8274.78; the Hang Seng Red Chip Index lost 59.99 points, or 1.41%, to 4203.42.
European stock markets opened in the afternoon: Germany’s DAX 30 opened 0.01% higher, UK FTSE 100 opened 0.01% lower, France’s CAC 40 opened 0.17% higher, Euro Stoxx 50 opened 0.07% higher, Spain’s IBEX 35 opened 0.51% higher, and Italy’s FTSE MIB opened 0.33% higher.
In the afternoon, Shanghai Gold Exchange’s Au(T+D) closed up 0.51% at 952.0 yuan per gram; Ag(T+D) closed up 1.41% at 16330.0 yuan per kilogram.
The latest intraday data shows Germany’s final August CPI month-on-month rate stood at 0.2%, matching market expectations and the previous reading. The European Central Bank will release its latest interest rate decision tonight, followed by a monetary policy press conference by ECB President Lagarde. Markets widely expect the ECB to raise interest rates again to counter rising energy prices triggered by the Iran conflict and their potential inflationary impact. The policy rate will likely be lifted from 2.25% to 2.50%, with signals that further tightening may follow if inflation prospects do not improve.
Last night, the US Treasury raised the cap for buybacks of its own long-term Treasury bonds to $6 billion to ease pressure on the bond market, yet the market did not respond positively. The US 10-year Treasury yield instead climbed to 4.84%, the highest level since November 2023.
Analysts said the US Treasury buyback aims to boost bond liquidity and ease Washington’s borrowing pressure. Nevertheless, the move failed to lift market confidence. Even as Treasury yields kept rising, the US dollar remained weak, showing that market worries over US debt and financing conditions have not eased.
Last Friday, US President Trump directly addressed Fed Chair Walsh, whom he appointed, urging him to make changes and act as a patriot. He stated high interest rates put the US at a very unfair disadvantage and he would not allow this to continue. He also warned that if the Fed did not cut rates, he would halt trade with countries running trade deficits with the United States.
The core economic pain point in the US now is that the Personal Consumption Expenditures (PCE) price index stands at 3.7%, nearly double the Fed’s 2% target. This core inflation gauge has overshot the target for five and a half consecutive years, and disinflation has bASIcally stalled since late 2024.
As intensifying Middle East conflicts fuel growing market concerns over regional oil supply, data shows that in the week before US-Iran hostilities resumed on August 30, daily oil flows through the Strait of Hormuz reached about 8 million to 9 million barrels, double the level of the prior week, but recently dropped below 2 million barrels per day. Brent crude has broken above $100 per barrel for the first time since July 24, indicating fading market hopes for a permanent solution to the US-Iran conflict.
Key data to watch tonight is US August Producer Price Index (PPI). US Consumer Price Index (CPI) will be released tomorrow evening. Both figures carry certain influence over next week’s Federal Reserve monetary policy meeting and will serve as critical catalysts for the next phase of international gold price movements.
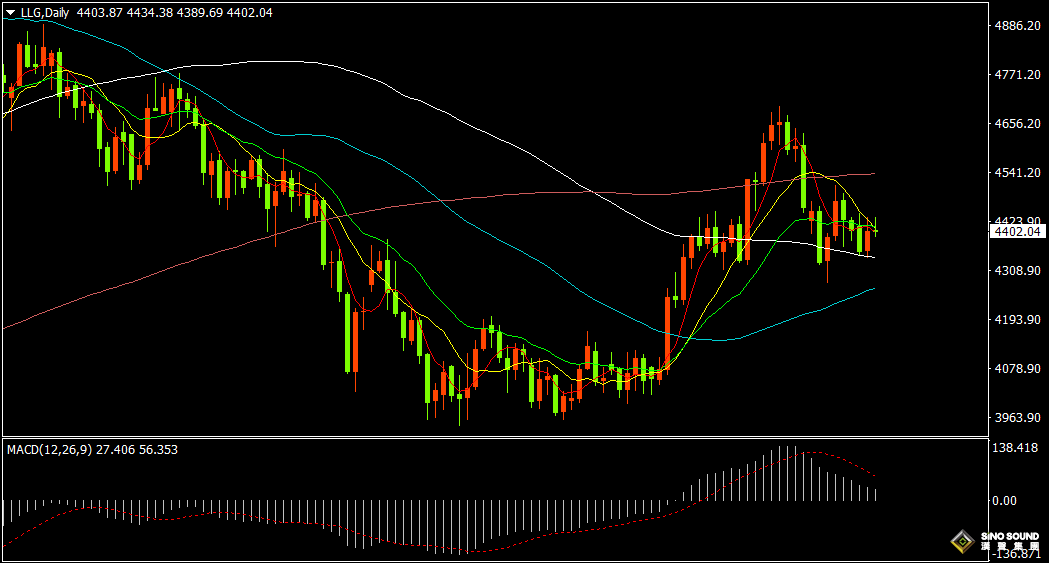
From gold’s daily chart, gold rallied to near $4434 intraday but then retreated after hitting the high. It is now consolidating around the intersection of the 5-day and 10-day moving averages and continues to fluctuate around the $4400 level. Daily indicators show the MACD positive momentum bar remains low, and the RSI flatlines near the 50 level, indicating balanced power between bulls and bears.
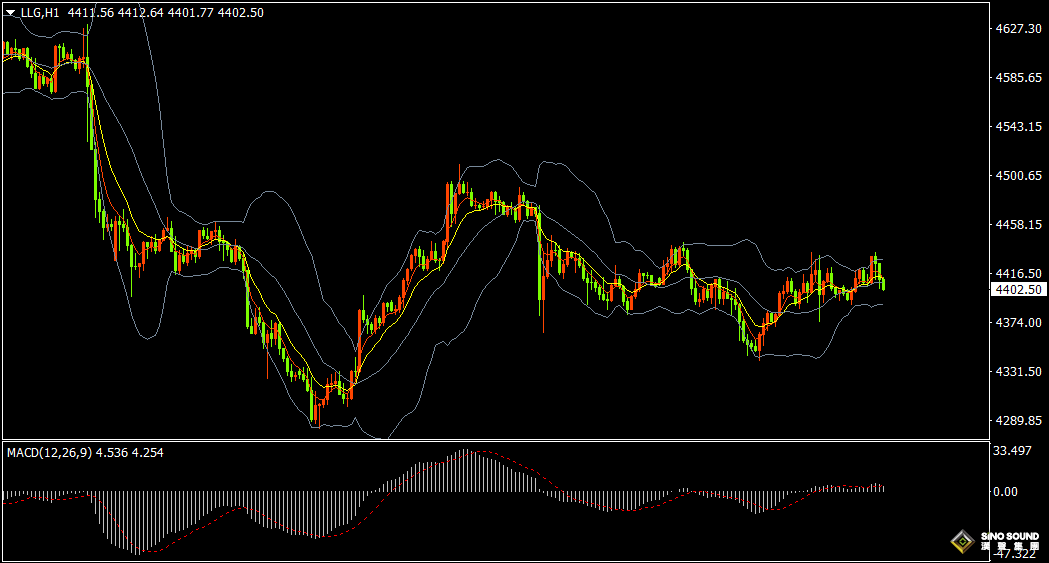
On the 1-hour gold chart, gold fluctuates near the middle BOLLinger Band. Short-term moving averages EMA5 and EMA10 have tangled. The MACD positive momentum bar is relatively small, while RSI has turned down to near the 45 level. For short-term trading tonight, expect gold to trade within the range of $4370-$4440. A breakout to the upside will target $4450-$4470 or near $4490; a downside breakout targets $4360-$4350 or near $4335. Therefore, ahead of the US inflation data release, gold will most likely maintain wide-range oscillation, and the breakout direction will depend on repricing of the US dollar and interest rate expectations triggered by the data.
Key financial data and events to watch tonight:
20:15 ECB Interest Rate Decision
20:30 US Initial Jobless Claims for the week ending September 5
20:30 US August PPI YoY
20:30 US August PPI MoM
20:45 ECB President Lagarde Press Conference
22:00 US Pending Home Sales Annualized for August
22:00 US July Wholesale Sales MoM
22:30 US EIA Natural Gas Inventory for the week ending September 4
00:00 (next day) US EIA Crude Oil Inventory for the week ending September 4
00:00 (next day) US EIA Cushing Crude Oil Inventory for the week ending September 4
00:00 (next day) US EIA Strategic Petroleum Reserve Inventory for the week ending September 4
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.