

Dovish remarks from Federal Reserve officials weighed on the US dollar and pushed Treasury yields across the curve lower overnight. Spot gold climbed 1.93 % to settle at $4472.87 per troy ounce. Spot gold opened at $4474.21 per troy ounce during Friday’s ASIan session. It drifted moderately lower in early‑ASIan trade to a session low of $4460.02, then rebounded at the start of European hours to hit $4490.88. Gold traded near $4478 at the time of writing.
Following a sharp drop in the US Dollar Index overnight, the index edged higher today, peaking at 99.09 and last quoted at 99.06, up 0.06 %. The 2‑year US Treasury yield rose 0.1 bASIs point to 4.34 %; the 10‑year yield fell 1.5 bASIs points to 4.755 %; the 30‑year yield dropped 1.3 bASIs points to 5.235 %.
Global crude oil benchmarks traded within a narrow range earlier today before turning lower in the afternoon. WTI crude stands at $90.59 per barrel, down 1.34 %; Brent crude is at $95.19 per barrel, down 0.45 %. US natural‑gas CFD closed at $2.928 per million British thermal units, up 0.205 %.
In equities, China’s A‑share major indices opened higher then drifted lower. Combined turnover on the Shanghai and Shenzhen bourses reached RMB 2.03 trillion, an increase of roughly RMB 271.8 billion versus the same period on the previous trading day. At close, the Shanghai Composite Index shed 11.97 points or 0.3 % to 3930.12; the Shenzhen Component Index fell 108.15 points or 0.79 % to 13516.97; the ChiNext Index lost 26.0 points or 0.78 % to 3286.55.
Hong Kong’s Hang Seng Index jumped at the open then pared gains in afternoon trade. It closed up 437.56 points or 1.74 % at 25650.87. The Hang Seng Tech Index rose 101.32 points or 2.27 % to 4569.8; the Hang Seng China Enterprises Index added 169.79 points or 2.02 % to 8555.03; the Hang Seng Red‑Chip Index advanced 36.0 points or 0.86 % to 4213.46.

Major European equity indices opened lower this afternoon. Germany’s DAX 30 opened‑0.02 %, UK FTSE 100‑0.22 %, France’s CAC 40‑0.20 %, Euro Stoxx 50‑0.25 %, Spain’s IBEX 35‑0.25 %, Italy’s FTSE MIB‑0.31 %.
On the Shanghai Gold Exchange, Au(T+D) closed up 1.36 % at RMB 965.0 per gram, while Ag(T+D) finished 1.63 % higher at RMB 16245.0 per kilogram.
Overnight, Fed Governor Waller indicated he would favour keeping rates unchanged in September if inflation continues to improve in August. The remarks pulled short‑ and long‑dated Treasury yields lower, and the weaker US dollar lifted international gold prices. Oil prices remain elevated. Tonight’s upcoming US August Non‑Farm Payrolls release represents a critical input for Federal Reserve policy deliberations.
Analysts point to a notable contradiction within the US labour market: new job creation has clearly cooled, yet unemployment, lay‑off data and initial jobless‑claims figures remain stable. The ADP National Employment Report released overnight posted its smallest monthly gain since January this year, signalling soft corporate hiring appetite.
Under normal circumstances, such subdued job growth would stoke market fears of labour‑market deterioration. However, Fed Chairman Warsh has effectively reshaped market interpretations of payroll data, de‑emphASIsing employment metrics and shifting policy focus toward inflation.
Energy‑driven inflation may heat up further as conflicts involving Iran and Russia roil energy markets. Ahead of the global peak‑demand season, data from the American Automobile Association shows average US diesel prices have climbed to $5.85 per gallon, surpassing the prior peak set in June 2022.
The European Union formally announced its support this week for the US‑led “Operation Economic Pariah”, marking Washington’s escalation of pressure against Tehran from purely military posturing toward full‑fledged international financial blockade. Launched in late August by the Trump administration, the sanctions target Iran’s digital‑asset access, advanced‑technology procurement, gold reserves, commercial aviation and shipping sectors.
A spokesperson for Iran’s foreign ministry issued a sharp warning, labelling US sanctions “economic terrorism”. The EU’s move, he argued, amounts to capitulation to US coercion and a betrayal of its own sovereignty, legislation, values and moral standards.
Faced with threats of US military strikes and regional‑peace considerations, Oman has quietly rejected Iran’s proposal for joint collection of service fees from merchant vessels transiting the Strait of Hormuz, seeking to avoid exposure to potential US military action. The Strait of Hormuz ranks among the world’s most vital oil‑shipping chokepoints; any move to assert control over the waterway carries heavy geopolitical sensitivity.
Market focus falls on tonight’s US Non‑Farm Payrolls report. Consensus forecasts look for 53,000 new August non‑farm jobs, following a July reading of‑23,000; the unemployment rate is expected to hold steady at 4.1 %; labour‑force participation is projected to edge up from 61.4 % to 61.5 %; average hourly earnings are seen rising 0.3 % month‑on‑month. The release is likely to trigger substantial market swings. Investors are reminded to manage position‑size risks prudently.
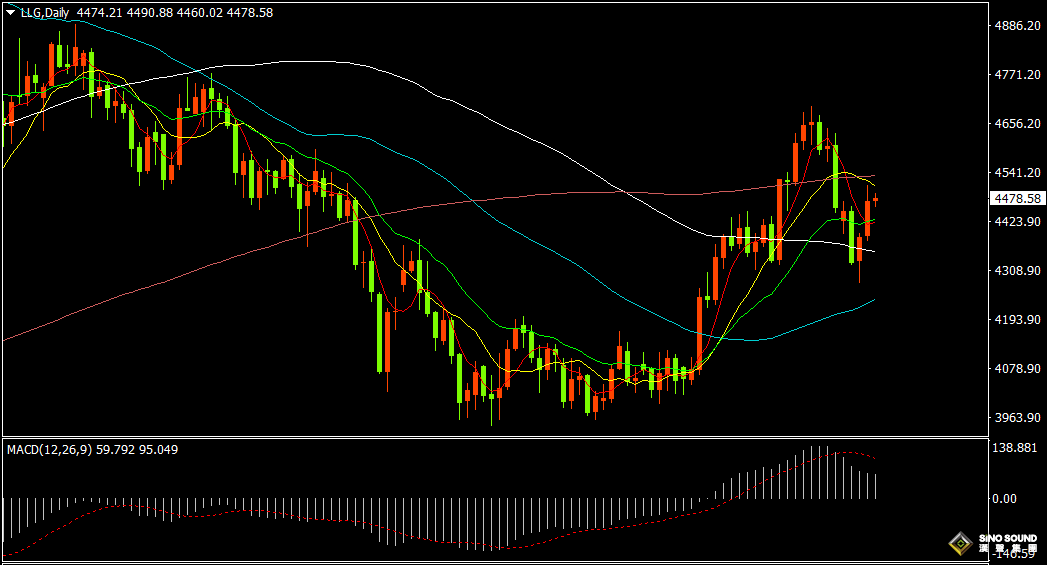
On the daily gold chart, intraday trading ranges have narrowed amid cautious sentiment ahead of tonight’s payroll print. Near‑term resistance lies near the 10‑day moving average ($4500) and the 200‑day moving average ($4535). Near‑term support sits around the 5‑day moving average ($4425) and the 100‑day moving average ($4360).
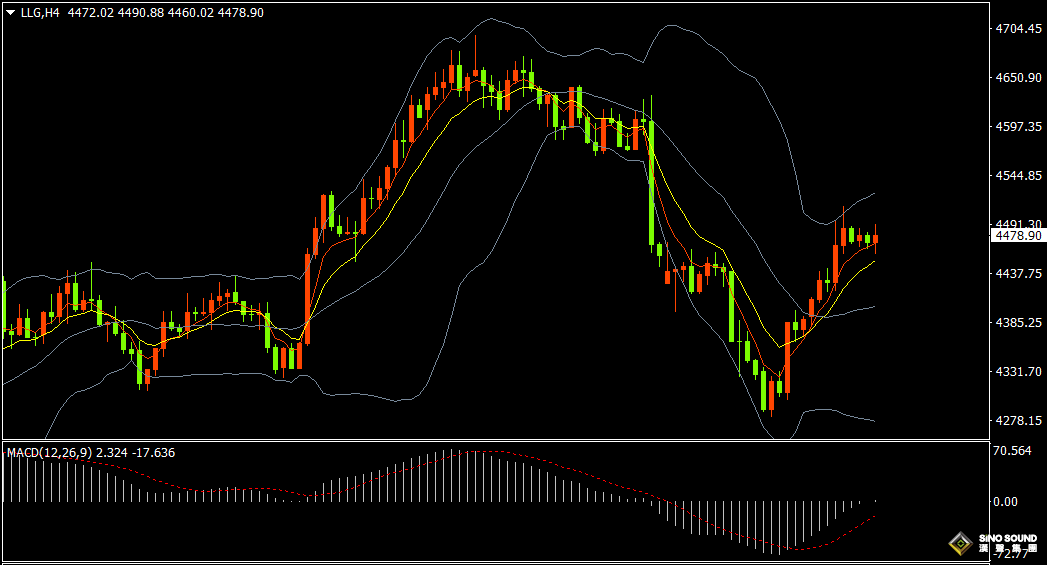
On the 4‑hour gold chart, prices are consolidating around the middle BOLLinger Band. Short‑term EMA5 and EMA10 maintain a bullish alignment. MACD negative histogram has shrunk toward the zero line, while RSI hovers near the 56 level. For near‑term trading tonight: markets await payroll prints. A breakout outside the $4445‑$4510 range could open upside objectives toward $4525‑$4545 or $4565. Downside targets are located at $4425‑$4400 and $4370.
Key upcoming economic data & events tonight:
20:30 Canada August Employment Change
20:30 US August Unemployment Rate
20:30 US August Seasonally‑Adjusted Non‑Farm Payrolls
20:30 US August Average Hourly Earnings YoY
20:30 US August Average Hourly Earnings MoM
22:00 US August Global Supply Chain Pressure Index
01:00 (next day) US Baker‑Hughes Oil Rig Count for the week ending Sep 4
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.