

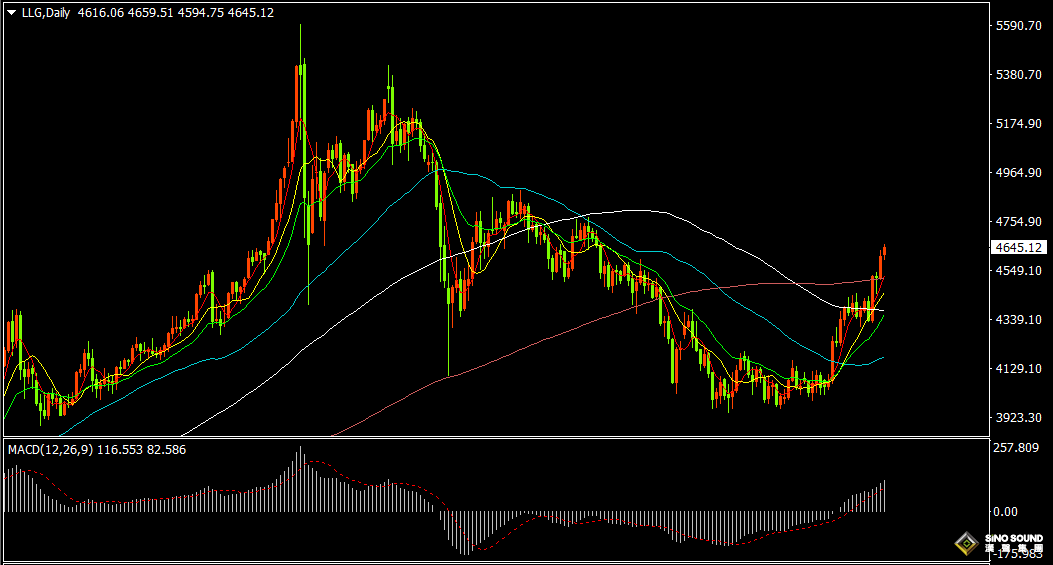
During Monday’s ASIan session, spot gold opened at $4616.06 per ounce and hit an intraday low of $4594.75 per ounce. Gold kept rallying in early ASIan trade and peaked at $4659.51 per ounce. Its upward momentum faded in the afternoon. At press time, gold was trading near $4645, with an intraday gain of roughly 0.81%.
Last week, the US Dollar Index broke below 99 and dropped to a low of 98.56 before closing at 98.85. The dollar index rebounded today, touching 99.03 and standing at 99.01, up 0.17%. The 2‑year US Treasury yield fell 1 bASIs point to 4.224%, while the 10‑year US Treasury yield declined 2.8 bASIs points to 4.71%.
After climbing for two consecutive weeks, crude oil retreated on Monday. WTI crude traded at $85.33 per barrel, down 1.44%. Brent crude stood at $91.44 per barrel, down 2.71%. US natural gas CFDs were quoted at $2.804 per MMBtu, gaining 0.322%.
In equities, China’s three major A‑share indexes drifted lower. The Shanghai Composite Index closed down 23.19 points or 0.59% at 3882.01. The Shenzhen Component Index fell 299.88 points or 2.13% to 13794.29. The ChiNext Index dropped 113.69 points or 3.21% to 3431.89.
Hong Kong’s main equity benchmarks traded lower. The Hang Seng Index closed 492.13 points or 1.89% lower at 25517.33. The Hang Seng Tech Index shed 172.12 points or 3.61% to 4594.04. The Hang Seng China Enterprises Index fell 162.98 points or 1.89% to 8471.36. The Hang Seng Red Chip Index lost 44.72 points or 1.04% to 4247.63.
Most European stock indexes opened lower this afternoon. Germany’s DAX 30 opened ‑0.15%, UK FTSE 100 ‑0.01%, France CAC 40 ‑0.06%, Euro Stoxx 50 ‑0.31%, Spain IBEX 35 +0.12%, Italy FTSE MIB ‑0.13%.
On the Shanghai Gold Exchange, Au(T+D) closed up 2.68% at RMB 1004.0 per gram. Ag(T+D) finished +0.68% at RMB 16750.0 per kilogram.
On the news front, US‑Canada trade talks collapsed last Friday. New US tariffs on Canada took effect over the weekend, and Canada announced retaliatory duties. The Canadian dollar keeps falling. Canada faces heavier losses, and the Prime Minister has signalled openness to more fiscal stimulus to support affected domestic businesses.
US Treasury Secretary Bessent will hold a press conference at 2:00 AM tonight. He has previewed “the harshest sanctions in history” against Iran. It remains unclear whether Washington’s economic‑isolation strategy will work. If implemented as planned, the sanctions could further disrupt Middle‑East oil supplies.
Iran’s foreign ministry stated Iran will not accept cease‑fire terms dictated by the aggressor. Under international law, Iran has the legitimate right to strike the sources of aggression and will show no leniency in defending national sovereignty. It added reports of millions of barrels of oil flowing daily through the Strait of Hormuz represent enemy psychological warfare, not facts.
The US has cancelled a scheduled joint amphibious landing drill with South Korea next month. Sources cite troop constraints stemming from the Iran conflict. Before this cancellation, Trump last Friday unexpectedly ordered scaling‑back of another annual joint exercise, citing high costs and Seoul’s refusal to join the war against Iran.
With US national debt surpassing $40 trillion, the US Treasury has frequently intervened in bond and foreign‑exchange markets recently. This risks sustained US‑dollar weakness and lifts safe‑haven assets. Crude oil stays elevated, global bond markets face stress, and yield curves across maturities are testing multi‑year highs. Markets are no longer focused solely on debt figures but increASIngly watch how policymakers respond to mounting pressure. This week’s US PCE inflation data and policy signals from the annual Jackson Hole Symposium will offer fresh guidance.
Fed Chair Walsh will speak at Jackson Hole on Friday. He may offer few clues on future policy. Without credible fiscal consolidation by then, the long‑end bond market could come under particular pressure, which would be another headwind for the US dollar. Analysts note that the more visible these price‑distorting interventions become, the greater the depreciation pressure on the dollar.
Dollar weakness, together with yield‑driven signals of latent economic pressure and policy uncertainty, underpin further upside for international gold. Gold hit its highest level in more than three‑months on Monday.
On the daily chart, gold rallied toward the $4660 psychological level, where notable resistance emerged. Nevertheless, prices are firmly above the 200‑day moving average. Holding above $4600 would target $4700 next. On daily indicators, MACD positive histogram keeps expanding, and the RSI hovers near 72 above the overbought threshold.
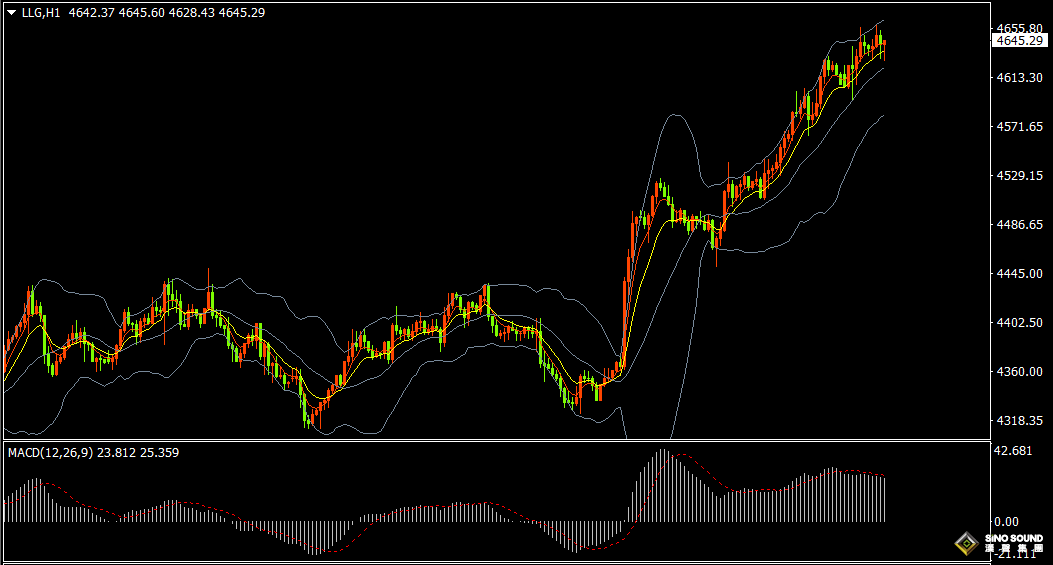
On the 1‑hour chart, gold oscillates between the middle and upper BOLLinger Bands. Short‑term EMA5 and EMA10 remain bullish, though their upward angle has flattened. MACD positive histogram shrinks gradually, and RSI has retreated to around 67. For evening short‑term trading, I maintain earlier intraday strategy: watch price action within the $4620‑4670 range. A breakout higher targets $4680‑4695 or near $4705. Downside objectives sit at $4610‑4600 or around $4592.
Reminder: No major economic data releases are scheduled for today.
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.