

Early in last night’s US session, spot gold rebounded from an intraday low of $4,450.90 per ounce and climbed back above the $4,500‑per‑ounce mark, hitting a high of $4,540.67 per ounce before closing at $4,519.03 per ounce, down 0.08%. Spot silver set another new high at $68.917 per ounce and closed at $68.019 per ounce, up 1.63%.
During today’s (Friday) ASIan session, spot gold opened at $4,518.84 per ounce with an intraday low of $4,508.70 per ounce. It edged higher in early ASIan trade to a peak of $4,543.54 per ounce. At press time, gold was trading near $4,537 per ounce, marking an intraday gain of 0.40%.
Last night, the US Dollar Index rebounded from the low of 98.56 to a high of 98.93 and finished at 98.87, up 0.07%. The 2‑year US Treasury yield rose 2.3 bASIs points to close at 4.189%; the 10‑year yield climbed 5.8 bASIs points to 4.705%; the 30‑year yield increased 5.6 bASIs points to 5.249%.

International crude oil has traded at elevated levels for three consecutive weeks amid the stalemate over Iran. WTI crude oil closed at $86.33 per barrel last night, up 2.38%. Brent crude oil settled at $93.37 per barrel, up 2.07%. US natural gas CFD closed at $2.792 per million British thermal units, up 0.072%.
The three major US stock indexes closed lower overnight. The Dow Jones Industrial Average fell 700.75 points or 1.31% to 52762.30. The S&P 500 dropped 66.42 points or 0.86% to 7641.56. The Nasdaq Composite declined 263.92 points or 1.00% to 26067.17.
Most major European equity indexes finished in negative territory. Germany’s DAX 30 fell 0.58% to 25978.46. UK FTSE 100 edged down 0.03% to 10740.15. France’s CAC 40 lost 0.57% to 8453.09. Euro Stoxx 50 dropped 0.35% to 6421.65. Spain’s IBEX 35 slipped 0.22% to 19803.59. Italy’s FTSE MIB rose 0.05% to 52645.00.
On the Shanghai Gold Exchange, Gold T+D closed 1.02% higher at RMB 976.38 per gram, while Silver T+D rose 2.28% to RMB 16535.0 per kilogram. In early Friday ASIan trade, SGE Gold T+D was up 1.02% at RMB 976.38 per gram; Silver T+D gained 2.1% to RMB 16506.0 per kilogram.
Holdings of SPDR Gold Trust, the world’s largest gold ETF, increased by 4.28 tonnes versus the previous trading day to 1038.934 tonnes. Positions in iShares Silver Trust, the world’s largest silver ETF, remained unchanged at 15275.59 tonnes.
Today’s RMB central parity rates: USD‑CNY 6.7817 (+9 pips); EUR‑CNY 7.8906 (+91 pips); HKD‑CNY 0.86466 (-1 pip); GBP‑CNY 9.2101 (+308 pips); AUD‑CNY 4.8058 (+17 pips); CAD‑CNY 4.8966 (+126 pips); 100JPY‑CNY 4.2516 (-120 pips); CNY‑RUB 12.3275 (-1844 pips); NZD‑CNY 4.0180 (+164 pips); CNY‑MYR 0.59817 (-14.7 pips); CHF‑CNY 8.4479 (-155 pips); SGD‑CNY 5.3115 (-13 pips).
Latest overnight data: Russia’s central‑bank gold and foreign‑exchange reserves stood at USD 755.6 billion for the week ending August 14, versus the prior reading of USD 740.0 billion. US Initial Jobless Claims for the week ending August 15 printed at 206,000 vs consensus 210,000; the previous figure was revised from 209,000 to 212,000. US August Philadelphia Fed Manufacturing Index came in at 47.4 versus expectation 25 and prior 41.4. US July Conference Board Leading Economic Index MoM rose 0.2% versus forecast 0.10%; the prior reading was revised from -0.20% to -0.1%.
US initial jobless claims edged lower and stayed near historic lows, pointing to limited layoffs across the labor market. The US leading index ticked higher in July for the fourth time in six months, signalling moderate ahead‑of‑trend economic expansion. The Conference Board continues to project US real GDP growth of 1.9% for both 2026 and 2027.
San Francisco Fed President Daly offered a positive assessment of current policy settings overnight. She noted that US Treasury markets signal monetary policy is well calibrated and she sees no risks to the Fed’s credibility. Inflation shocks are expected to fade gradually. She strongly supported keeping rates unchanged at the July FOMC meeting while warning against cumulative multi‑source inflation pressures.
US Treasury Secretary Bessent commented on bond buybacks: per‑operation buyback caps could exceed USD 4 billion, and yields do not reflect underlying fundamentals. Additional fiscal consolidation measures may be announced. We may well have passed the deficit peak, and the USD 40‑trillion‑debt figure carries limited standalone significance. Markets have got ahead of themselves. The Treasury will coordinate with the Federal Reserve for any balance‑sheet adjustments.
Analysts note that US July retail sales declined and employers unexpectedly cut jobs. These macro releases have materially reduced pressure for near‑term Fed rate hikes. Meanwhile, the US Treasury’s expanded long‑term bond buyback program is interpreted by markets as implicit quantitative eASIng. Market‑priced odds for a September rate hike stand at roughly 30%, down sharply from over 70% at end‑July.
On geopolitics: US President Trump has taken steps to avoid military escalation against Iran and expressed optimism that economic pressure can bring Tehran back to the negotiating table. He added that the US will impose sanctions on any country conducting business with Tehran.
Iranian sources stated that Yemen’s Houthi capabilities keep growing. In the event of renewed conflict, more destructive weaponry will be deployed. “We advance across all weapons categories. Should war resume, our arsenal will differ from the past; weapon R&D and production progress daily and all scenarios remain on the table.”
A Houthi spokesperson stated that Yemeni armed forces successfully carried out two drone‑based military operations and achieved operational objectives. The strikes were in response to Saudi drone violations over Saada province.
Due to reciprocal Russian‑Ukrainian strikes targeting ports and vessels, grain exports across the Black Sea and Sea of Azov have nearly ground to a halt, with export capacity down more than 97%. Civilian shipping in the Black Sea is largely paralyzed.
Gold fundamentals: gold strengthened sharply after the US Treasury expanded long‑dated Treasury buybacks. Support peRSIsts from dollar weakness, fiscal‑deficit concerns and ongoing central‑bank buying. Market expectations for gold to break $5,000 next year are rising.
As implied Fed‑hike probabilities recede, gold ETFs added 70 tonnes across July and August, reveRSIng the 93‑tonne outflow recorded in May‑June. Statistics show China has added 60 tonnes of gold so far this year, the highest comparable reading since 2023. Poland added 82 tonnes, lifting its gold reserves to 632 tonnes as it moves toward its 700‑tonne target.
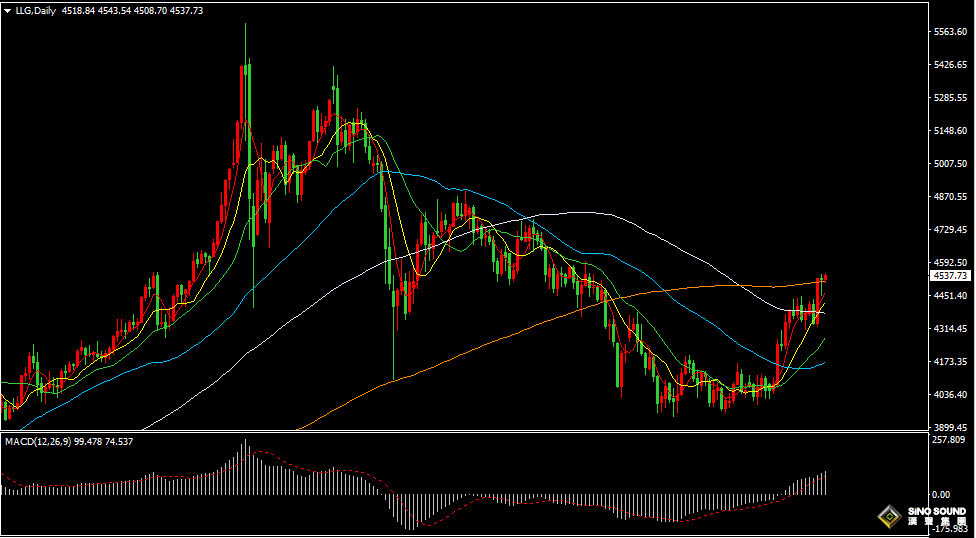
On the daily chart, gold printed a long‑lower‑wick candlestick yesterday, confirming support near $4,450. Prices have reclaimed $4,500 and trade above the 200‑day moving average. On daily indicators: the 5‑day and 10‑day moving averages maintain upward bullish momentum; MACD positive momentum bars keep expanding; the RSI flattens near the 67 level.
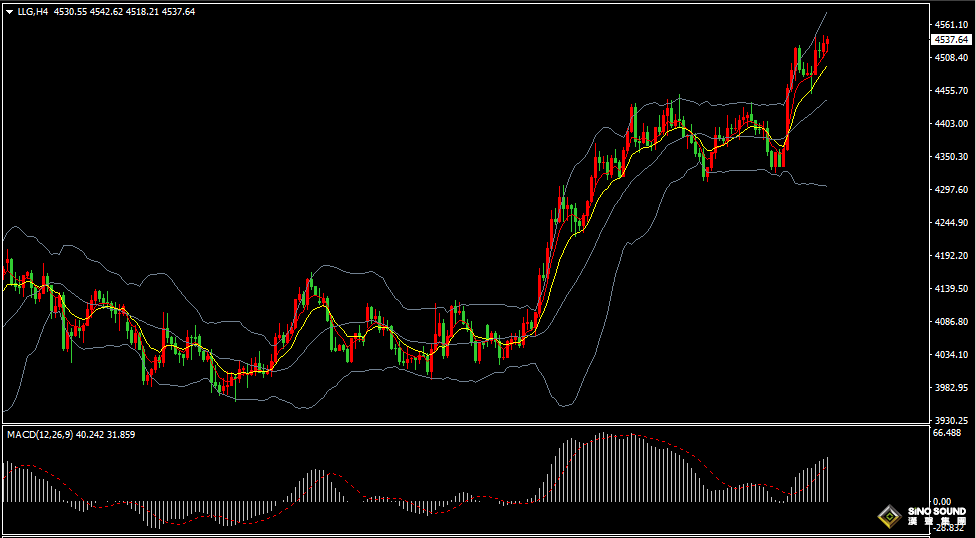
On the 4‑hour chart, gold drifts upward near the upper‑middle BOLLinger Bands. Short‑term EMA5 and EMA10 remain bullish‑sloped. MACD positive momentum bars keep growing and RSI approaches overbought territory near 69. Intraday outlook: expect range‑bound consolidation between $4,500‑4,550. A breakout higher targets $4,560‑4,570 or near $4,585. Downside objectives sit at $4,490‑4,480 or near $4,460.
Key economic data and events for today:
14:00 UK Public‑Sector Net Borrowing (July)
14:00 UK Retail Sales MoM (July, seasonally adjusted)
15:15 France Manufacturing PMI Flash (August)
15:30 Germany Manufacturing PMI Flash (August)
16:00 Eurozone Manufacturing PMI Flash (August)
16:30 UK Manufacturing PMI Flash (August)
16:30 UK Services PMI Flash (August)
20:30 Canada Retail Sales MoM (June)
21:45 US S&P Global Manufacturing PMI Flash (August)
21:45 US S&P Global Services PMI Flash (August)
22:00 Eurozone Consumer Confidence Flash (August)
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.