Spot gold opened at $4300.59 per ounce during Tuesday’s ASIan session. As the US dollar and US Treasury yields kept climbing intraday, gold briefly rallied to $4317.15 per ounce before pulling back. After the European market opened in the afternoon, gold dipped to an intraday low of $4263.66 per ounce. At press time, gold was consolidating near $4270, down 0.67% for the day.
The US Dollar Index extended its upward move, hitting a high of 99.69 and last trading at 99.61, up 0.14%. The 2-year US Treasury yield rose 1.3 bASIs points to 4.675%; the 10-year US Treasury yield climbed 3.8 bASIs points to 5.029%, marking the highest level since 2000; the 30-year US Treasury yield advanced 4.8 bASIs points to 5.394%, a fresh high since 2007.
WTI and Brent crude oil kept edging higher today. WTI crude was quoted at $103.33 per barrel, up 1.56%; Brent crude stood at $107.59 per barrel, up 1.48%. US natural gas CFD was at $3.052 per MMBtu, up 0.461%.
In equities, the three major A-share indices edged up slightly in early trading before weakening amid fluctuations. By the close, total turnover on the Shanghai and Shenzhen stock markets reached 1.61 trillion yuan, hitting the lowest level for the year and down 16.5 billion yuan from the previous trading session. The Shanghai Composite Index fell 21.05 points, or 0.54%, to 3864.28; the Shenzhen Component Index dropped 96.59 points, or 0.72%, to 13287.97; the ChiNext Index declined 37.66 points, or 1.15%, to 3247.92.
Hong Kong’s Hang Seng Index closed lower. At market close, total turnover for the Hang Seng market reached HK$187.201 billion. The Hang Seng Index fell 250.36 points, or 1.0%, to 24667.24; the Hang Seng Tech Index dropped 26.6 points, or 0.62%, to 4291.34; the Hang Seng China Enterprises Index shed 79.67 points, or 0.96%, to 8204.91; the Hang Seng Red Chip Index declined 61.52 points, or 1.49%, to 4068.59.
European stock markets opened mostly lower in the afternoon. Germany’s DAX 30 opened down 0.11%, France’s CAC 40 down 0.37%, the EURO STOXX 50 down 0.37%, Spain’s IBEX 35 down 0.27%, Italy’s FTSE MIB down 0.66%, and the UK FTSE 100 down 0.33%.
In the afternoon, Shanghai Gold Exchange’s Au(T+D) closed down 1.08% at 928.0 yuan per gram; Ag(T+D) closed down 1.08% at 15419.0 yuan per kilogram.
On the latest data front, China’s National Bureau of Statistics reported that total retail sales of consumer goods from January to August reached 32.7569 trillion yuan, a year-on-year increase of 1.1%. In August, the month-on-month sales price of new commercial residential buildings in first-tier cities rose 0.1%, reveRSIng the flat reading in the prior month. New home prices in second-tier cities fell 0.1% month-on-month, while those in third-tier cities dropped 0.2%. Value-added industrial output in August rose 5.2% year-on-year in real terms, 0.7 percentage points faster than the previous month.
UK August jobless claims stood at 27,800, with the prior reading revised from -11,000 to -11,800. The UK three-month ILO unemployment rate for July was 4.9%, versus an expectation of 5% and a prior reading of 4.90%. The UK August unemployment rate was 4.4%, compared with 4.30% previously. France’s final August CPI month-on-month reading came in at 0.7%, matching forecasts and the preliminary figure of 0.70%.
Weak UK employment data for last month showed employers cut more jobs. The figures indicate Britain remains trapped in what Bailey called a low-hiring, low-layoff economy. EU-harmonised consumer prices in France rose 2.6% year-on-year in August, below the earlier preliminary reading of 2.7%. The harmonised inflation rate for the eurozone’s second-largest economy, adjusted for comparison with other eurozone countries, accelerated from 2.4% in July to its highest level since May.
Institutional analysis estimates that household energy bills in the UK will jump roughly 25% in January as the Iran war pushes up wholesale electricity and gas prices, further adding to overall inflationary pressure. Forecasts show rising energy costs may lift UK inflation above 4% next year, double the Bank of England’s target.
Reports state that amid fiscal pressure from surging borrowing costs, the Bank of England will halt sales of 20-year and 30-year UK government bonds accumulated to stabilise the economy during the financial crisis. Sales of these long-dated securities since 2022 have cost taxpayers £22 billion. Halting long bond sales is estimated to save £2.5 billion annually.
Multiple global financial institutions have adopted a more hawkish outlook on Federal Reserve rates, predicting rate hikes later this year and another increase by the European Central Bank. Due to recently higher-than-expected inflation data, the Fed is expected to raise rates by 25 bASIs points at its September 15–16 meeting and deliver another 25-bASIs-point hike in December.
US officials have acknowledged ammunition shortages in the war with Iran and are working to streamline procurement processes and production lead times, stockpiling key materials, components and selected munitions for rapid response to emergencies. Data shows ammunition consumed in the war was valued at $22.3 billion by roughly the end of June, while total costs up to that point exceeded $33 billion.
Iranian Parliament Speaker Ghalibaf said the impact of US oil reserves has faded and can no longer control oil prices. US Energy Secretary Wright stated confidence that flows through the Strait of Hormuz will increase in the coming weeks; the US will begin refilling its Strategic Petroleum Reserve in the months ahead.
Russian authorities said the diesel export ban is intended to support domestic market supply. Russia will reconsider resuming diesel exports once domestic fuel supplies stabilise.
Russia’s Defence Ministry reported today that Russian forces struck a logistics centre in Ukraine’s Odesa region used for receiving, storing and distributing military supplies, as well as two vessels carrying supplies for Ukrainian troops at the port of Chornomorsk. In addition, Russia continued strikes on railway infrastructure in western Ukraine used to transport military equipment from Europe.
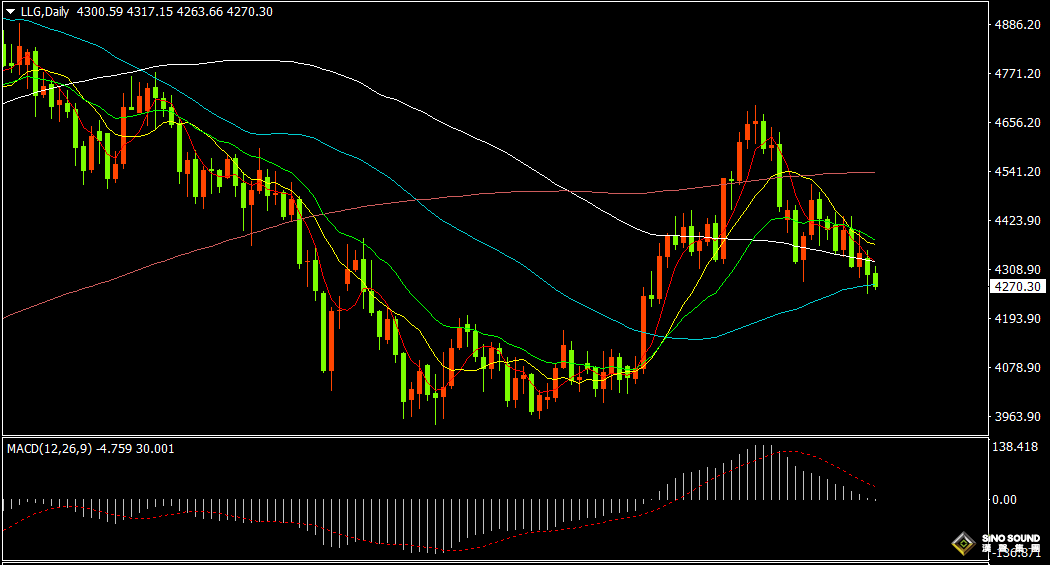
On the daily gold chart, gold rallied and retreated again intraday, showing resistance above $4300. The 5-day moving average crossed downwards with the 100-day moving average, indicating strong resistance here. Gold has broken below the 50-day moving average, and short-term daily support has shifted to around $4225 or the $4200 level. On daily indicators, the MACD histogram sits near the zero line, and the RSI has slipped to roughly 43.
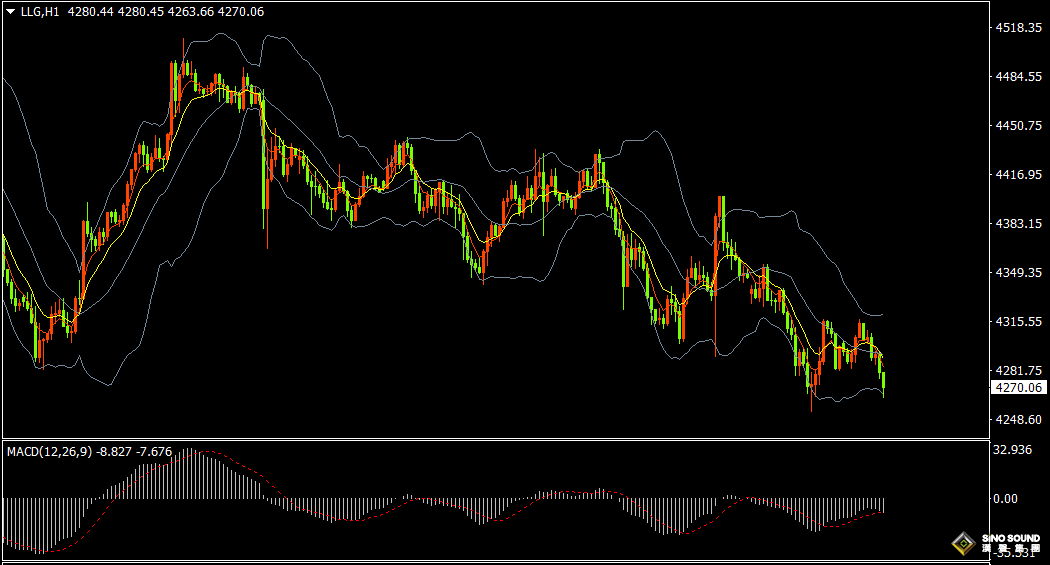
On the 1-hour gold chart, gold fell amid volatility to near the lower BOLLinger Band. Short-term EMA5 and EMA10 have formed another bearish downward crossover. The MACD negative histogram is gradually expanding, and RSI has retreated to roughly 36. For evening short-term trading, expect gold to oscillate within the $4225–$4300 range. A break higher targets $4315–$4335 or near $4350; a breakdown targets $4210–$4200 or near $4175.
Key economic data and events to watch tonight:
20:15 US ADP Employment Change for the week ending August 29
20:30 Canada July Wholesale Sales MoM
20:30 US September NY Fed Manufacturing Index
04:30 (Next Day) US API Crude Oil Inventories for the week ending September 11
[Disclaimer]The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of SinoSound. SinoSound remains neutral regarding the opinions and statements contained herein and makes no representations or warranties, whether express or implied, regarding the accuracy, reliability, or completeness of the information provided.
The content of this article is intended for informational and reference purposes only. Readers should exercise their own judgment and assume full responsibility for any decisions or actions taken based on the information contained herein.
[Copyright Notice]This article is original content and is protected by applicable copyright laws. Any reproduction, distribution, citation, or use of this content must clearly acknowledge the original source:
Gold2U
www.gold2u.com
We reserve all rights and may take legal action against any individual or entity that fails to comply with this notice or otherwise infringes our intellectual property rights.